Hi, How Can We Help You?
  • Planning for all of life's "What Ifs".

Blog


They say that to know where you are going, you first have to know where you came from. In the world of executive benefits and financial architecture, many people lead with spreadsheets, tax codes, and actuarial tables. But if you sit down with me for more than five minutes, you’ll realize that while I live and breathe the technicalities of IRC 409A and the complexities of deferred compensation, my "why" isn’t found in a ledger. It’s found in a legacy.


I’ve always viewed myself as an architect. Not of buildings, but of security. This mindset wasn’t something I picked up in a textbook; it was woven into the fabric of my life long before I founded Schiff Executive Benefits. It’s a mindset rooted in family, a passion for protection, and a deep respect for the hard work required to build a business that lasts.


The Multi-Generational Foundation


My journey in this industry isn’t just a career path; it’s a family tradition. Between my parents and myself, we represent nearly 150 years of collective experience in the financial services and insurance world.


Growing up, I watched my parents, Jayne and Bud Schiff, navigate the complexities of this business with a single-minded focus: taking care of people. They didn’t see clients as policy numbers; they saw them as families and businesses whose futures depended on the quality of our advice. That sense of responsibility stayed with me. It’s why I don’t just "sell" a plan: I architect a solution.


Jayne and Bud built more than a career legacy. They built a standard. Their example taught me that when you help protect a family, a business, or a future, you are doing deeply personal work. That legacy still shapes the way I serve clients today.


Today, that legacy continues with the unwavering support of my wife, Nancy, our CMO, The Ridgeback Group, our support team, and family legacy in our five children (Courtney and Jason, Alex, Ty, and Gavin).  They are the daily reminder that every decision has a human side. When we talk about protecting a business, we are really talking about protecting the people behind it and the families counting on them.


Bud, Jayne, Nancy, and Matt


Caption: The foundation of everything we do: the Schiff family legacy, built on protection, care, and continuity across generations.


The 2006 Pivot: Building Something Better


By the mid-2000s, I had achieved what many would consider the pinnacle of corporate success. As a Managing Director at NYLEX Benefits, I had helped grow a team from five to thirty-five people and was deeply entrenched in the high-level world of Executive benefits, Bank Owned Life Insurance (BOLI) and other corporate-owned strategies.


But I felt a pull toward something more personal, as well as a work/life balance. I wanted to build a firm where technical innovation met human-centric service: where we could be nimble enough to solve the most complex executive retention issues while remaining deeply connected to our clients' personal missions, and still be connected to my family. 


In May of 2006, I made the leap and founded Schiff Benefits Group. It was a pivotal moment. I wasn't just starting a company; I was creating a platform to implement the strategies that would eventually evolve into The Perfect Plan®.


Looking back, the timing was critical. The world was about to face the 2008 financial crisis, and the regulatory environment was shifting rapidly. My experience in the "big corporate" world gave me the technical expertise to navigate IRC 409A and other compliance minefields, but it was my passion for individual business owners that drove the firm forward.
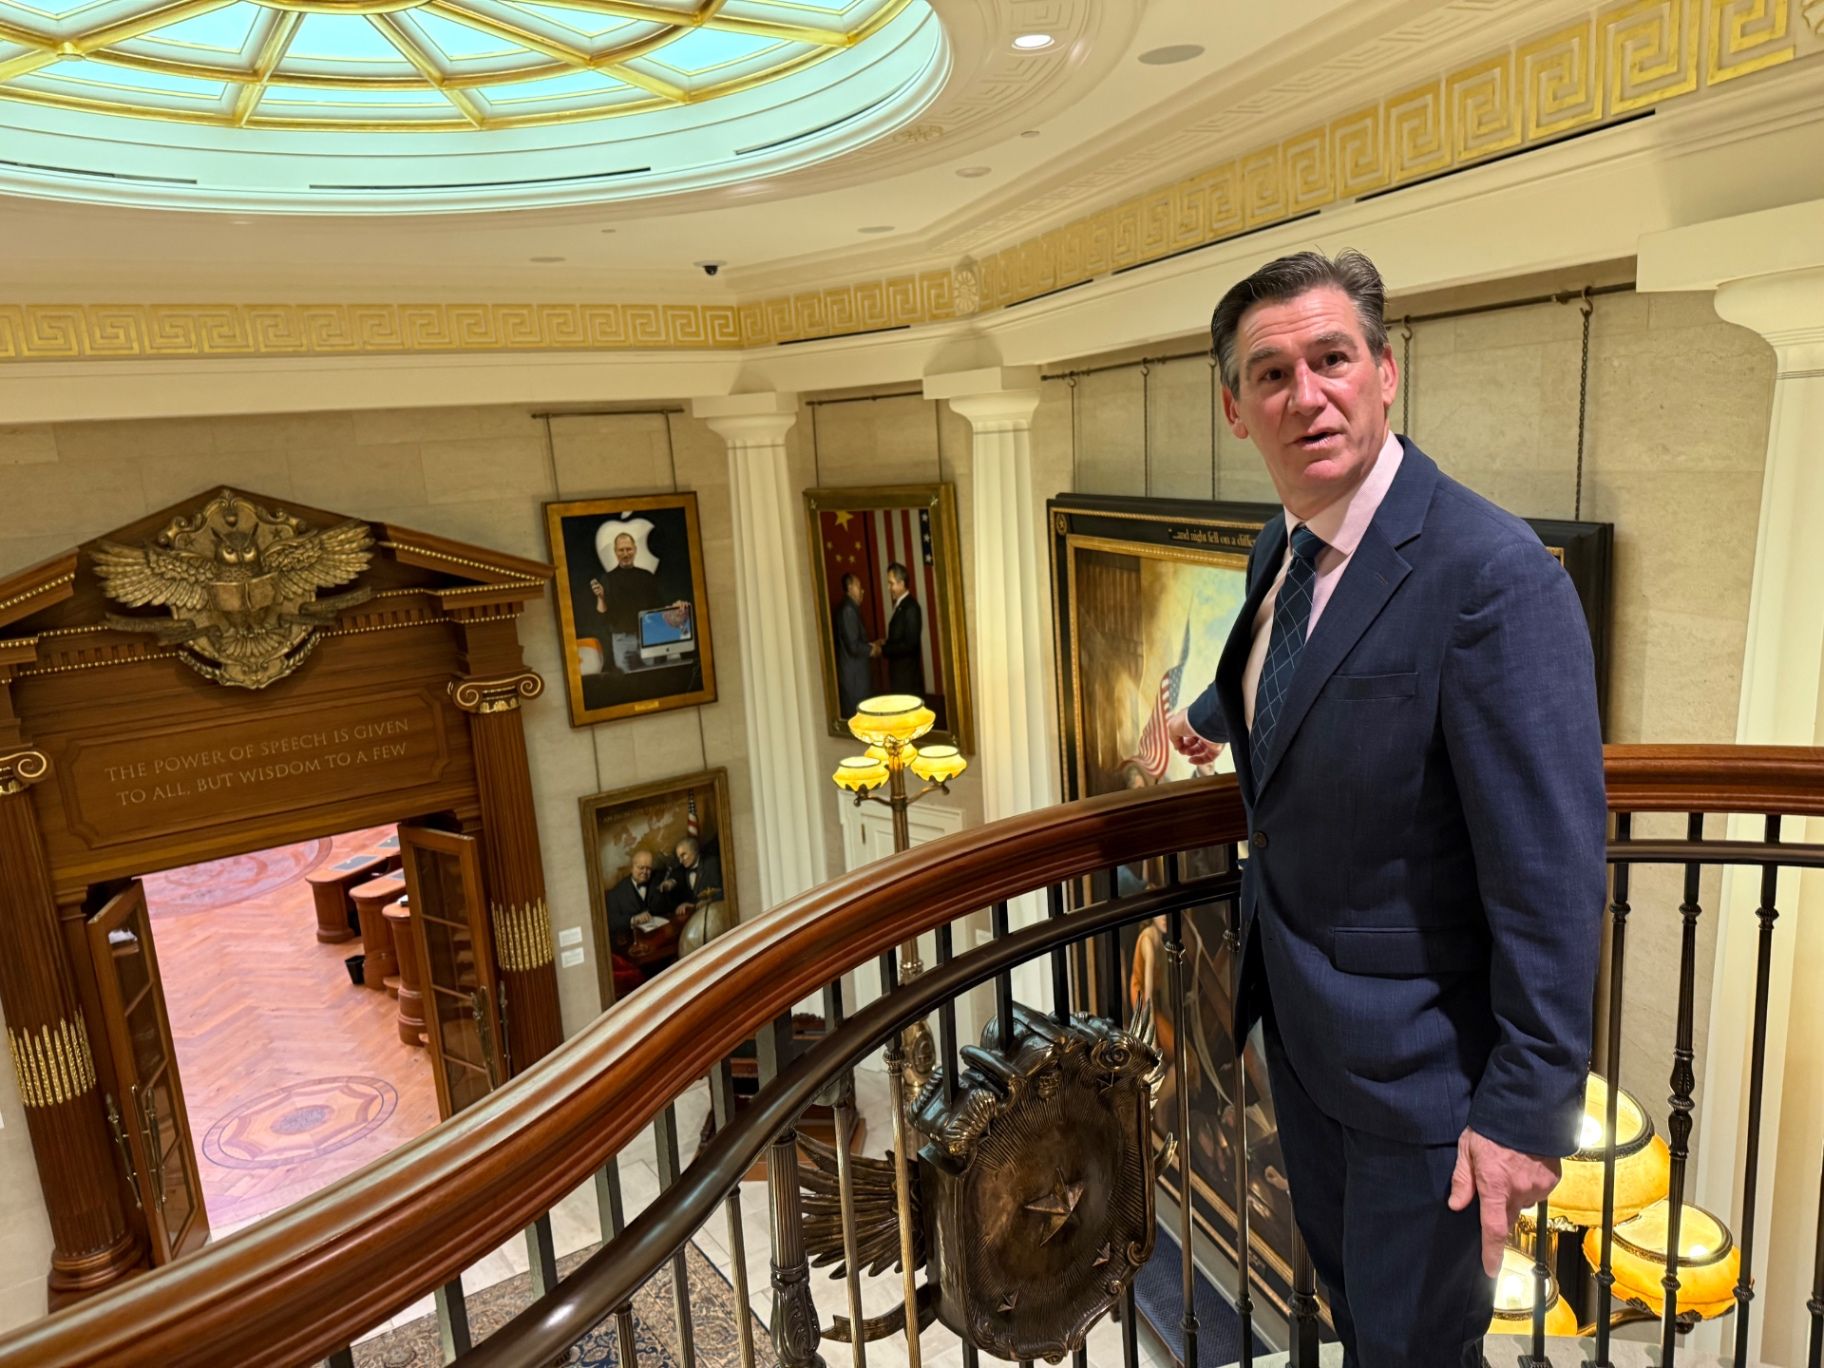

Matt Schiff - Grand Staircase Wisdom Inscription


A Passion Beyond the Spreadsheets


If you follow me on social media or listen to The Perfect Plan® Podcast, you know that my life isn't just about Corporate Owned Life Insurance (COLI) and ESOPs.


I am a lover of music, particularly the soulful, grounded sounds of "The Immediate Family." There is a rhythm to great music, a harmony where every instrument must be in sync to create a masterpiece. I see business planning the same way. If your estate plan isn't in harmony with your buy/sell agreement, or if your deferred compensation plan isn't aligned with your retention goals, the "music" of your business falls flat.


Matt Schiff at the Helm


Away from work, I stay busy with a few lifelong passions that have always kept me grounded: sailing, soccer, and golf. Sailing has long been a personal passion of mine. It teaches patience, awareness, adjustment, and respect for conditions you cannot control. Soccer brings energy, teamwork, and constant movement. Golf demands discipline, focus, and humility. Different games. Same lesson. You need a plan, and you need to stay aligned when conditions change.


Matt Schiff and soccer team


Caption: Fifteen years of friendship, teamwork, and shared passion for the game, reflecting Matt’s lifelong love of soccer and the bonds he builds along the way.


My goal is to bring that harmony to your professional and personal life. I want to help you solve what I call the "5 What Ifs" that keep business owners awake at night:


  1. What if you end up in business with a widow or widower? (Succession planning)

  2. What if a business buy-out is forced upon you at the worst time?

  3. What if your top talent walks across the street to a competitor?

  4. What if the cost of replacing a senior executive breaks the bank?

  5. What if you run out of money in retirement because you were too busy building the business?


Restoring alignment and retention isn't just our tagline; it's the rhythm we live by. We solve these "What Ifs" through technical mastery, but we frame them through the lens of protection for the families and legacies depending on you.


The Architect and The Perfect Plan®


When I call myself the "Architect of The Perfect Plan®," it’s not because I believe in a one-size-fits-all solution. Quite the opposite. Every architect knows that while the laws of physics (or tax codes) remain constant, the house must be built for the family living inside it.


The Perfect Plan® is a philosophy. It is a commitment to ensuring that every piece of your executive benefits package: from Executive Deferral Plans to Split Dollar arrangements to estate planning: is working toward a singular goal: your security.


We explore these concepts in depth on The Perfect Plan® Podcast, where we bridge the gap between technical strategies and real-world application. Whether we are discussing portable peace of mind or the nuances of business succession, the focus is always on the human element.
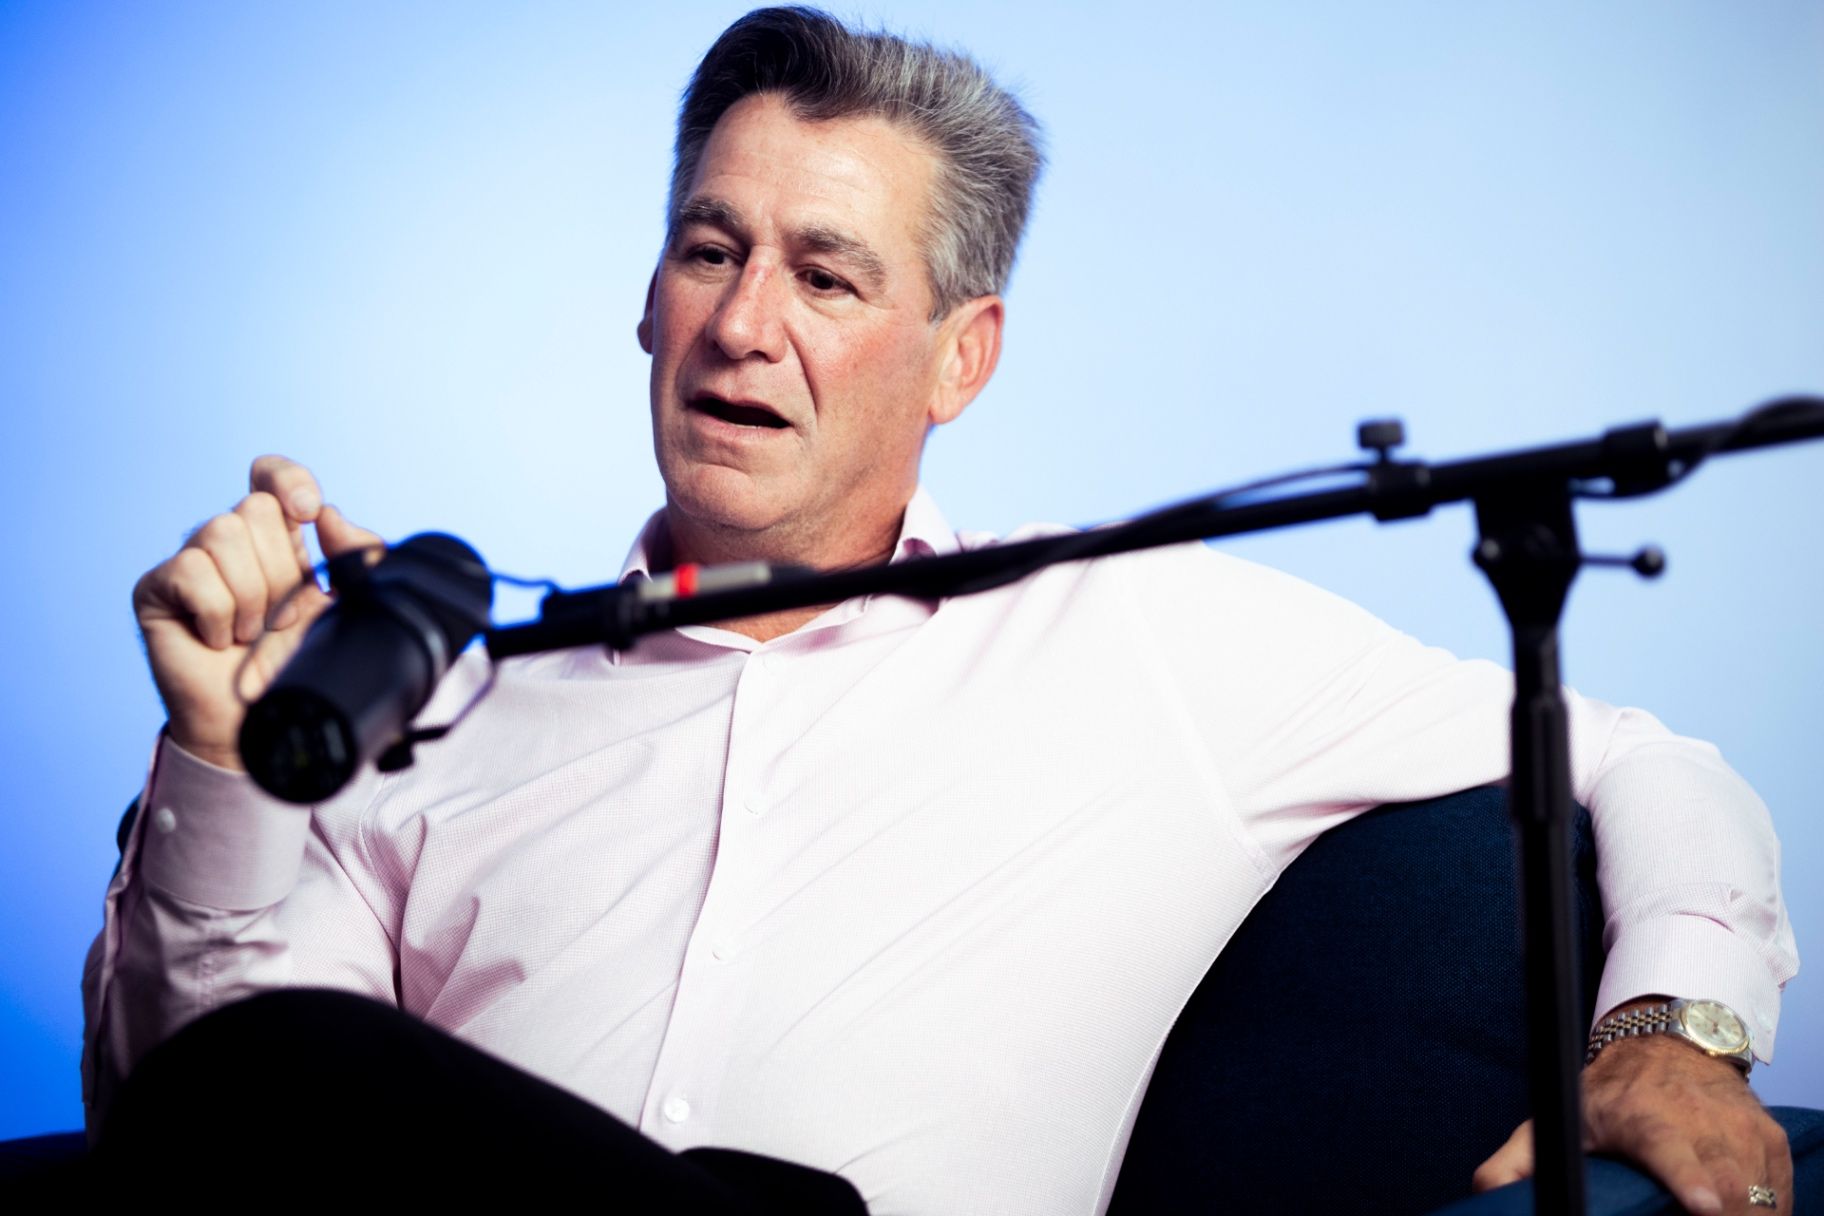

Matt Schiff - Podcast Setup


Why Experience Matters Now More Than Ever


We are currently navigating an era of "The 63% Exit Wave," where a massive generation of business owners is looking toward the horizon. At the same time, tax laws are in flux, and the competition for talent is fiercer than ever.


In this "unstable" environment, you don't just need a consultant; you need a guide who has seen the cycles before. Having been in this seat since 1992, and having lead Schiff Executive Benefits through two decades of economic shifts, I’ve learned that the best defense is a well-architected offense.


Whether we are working with a closely held family business on family wealth transfer and executive retention, a community bank on BOLI strategies or a global corporation on restoring executive alignment, the mission remains the same: Aligning a plan that fits the culture and legacy of the company tax efficiently, as well as is flexible for future needs.


Come Join Us


I often tell my clients to "sit back and grab your coffee" because these conversations shouldn't be stressful: they should be empowering. When you have a plan that addresses the technical "haunts" of the past and the "what ifs" of the future, you gain the freedom to focus on what you love: whether that’s growing your company, sailing, playing soccer or golf, or spending time with family.


My family legacy is one of protection. I’d love to help you secure yours.


If you’re ready to see how the "Architect" mindset can transform your business, I invite you to explore our latest insights or join the conversation over on The Perfect Plan® Podcast.


Let’s build something that lasts, together.


Matthew E. Schiff, CLU, ChFC, WMCP
President, Schiff Executive Benefits


Change is the only constant in life, yet we spend the majority of our professional careers trying to build a fortress of stability. We work late, we climb the ladder, and we take comfort in the "benefits package" listed in our employment contracts. But here is an undeniable truth that many executives realize too late: If you don't own it, you don't control it.


Most corporate benefits aren't actually yours. They are "leased" from your employer. And just like a leased car or a rented apartment, those benefits can be taken back the moment the lease is up, whether that’s through a job change, a layoff, or your eventual retirement.


At Schiff Executive Benefits, as we celebrate our 20th anniversary of Restoring Alignment and Retention, we’ve seen too many high-performers discover that their family’s financial safety net was tied to a desk they no longer sit at. If your peace of mind is contingent on your current HR department, you don't have peace of mind. You have a temporary arrangement.


The Illusion of the Corporate Safety Net


Let’s be real: when you look at your total compensation, the "group" benefits, life insurance, disability, and health coverage, look great on paper. They are often low-cost or even "free" to you. But in the world of high-stakes financial planning, free can be the most expensive price you’ll ever pay.


The problem with "leased" benefits is the lack of portability. We call these "weakest links" because they fail exactly when you need them most. Think about the Executive Sandwich: that decade where you are at your career peak, but also the "riskiest" decade for your family. You’re supporting aging parents and children’s tuition, all while maintaining a lifestyle that requires a high, steady income.


![Portable executive benefits and family security illustration]


What happens if you leave that role?


  • Your Group Term Life Insurance: Usually vanishes or offers a "conversion" option that is so prohibitively expensive it’s practically useless.

  • Your Group Disability: Gone. And if your health has changed during your tenure, you may find yourself uninsurable on the private market.

  • Your Retirement Gap: You might be hitting the 401(k) cap, leaving a massive void between your current lifestyle and what your "leased" plan will actually provide.


The Five "What Ifs" of Executive Security


In our two decades of consulting, we’ve narrowed the risks down to five core "What If" questions. If you can’t answer these with a definitive "I’m covered regardless of my employer," then your plan is in jeopardy.


  1. What if there’s a business buyout? If your company is sold, the new owners may not value the same benefit structures. Your "leased" security could disappear overnight in a merger.

  2. What if you are the top talent leaving? Whether you’re moving to a competitor or starting your own firm, you shouldn’t have to leave your family’s protection behind.

  3. What if you run out of money in retirement? Most leased benefits end at age 65. If you live to 95, who is covering the risk for those final 30 years?

  4. What if your successor costs more than expected? For the business owner, not having portable, owned benefits (like COLI) means the cost of replacing talent can skyrocket.

  5. What if you have to deal with a widow/widower (succession)? Without portable, owned life insurance structures like TOLI (Trust Owned Life Insurance), the transition of a business can be catastrophic for the surviving family.


Moving from "Leased" to "Owned" with The Perfect Plan®


![The five what-ifs of executive security planning]


So, how do we move from the fragility of "leased" benefits to the "Portable Peace of Mind" that ownership provides? It starts with a shift in philosophy. You need to treat your executive benefits with the same rigor you apply to your personal investment portfolio.


This is where The Perfect Plan® comes into play.


The Perfect Plan® isn't a single product; it’s a strategic framework designed to align the interests of the corporation and the executive. By utilizing structures like Corporate Owned Life Insurance (COLI) and Non-Qualified Deferred Compensation (NQDC), we can create benefits that are:


  • Portable: They stay with you, providing a continuous "security blanket" regardless of your employment status.

  • Tax-Efficient: They leverage the power of tax-deferred growth to solve the retirement gap created by 401(k) limits.

  • Discriminatory (In a good way): Unlike group plans, these can be customized specifically for the key leaders who drive the company’s success.


When we design The Perfect Plan®, we look at the "What Ifs" and solve them one by one. We ensure that the death benefit is there to protect your family, the cash value is there to supplement your retirement, and the disability coverage is own-occupation and portable.


The Corporate Perspective: Alignment and Retention


If you are a business owner or a board member, you might be wondering: "Why would I want my executives’ benefits to be portable? Doesn’t that make it easier for them to leave?"


It’s a fair question. But the reality is the opposite. Our tagline, Restoring Alignment and Retention exists because we know that top talent stays where they feel truly secure and valued.


When you provide a "leased" benefit, the executive knows it’s a temporary hook. When you facilitate "ownership" through a properly structured executive benefit plan, you are providing a sophisticated wealth-building tool that demonstrates a long-term commitment to that leader’s family. You aren't just giving them a job; you are helping them build a legacy.


Furthermore, using COLI (Corporate Owned Life Insurance) to fund these obligations allows the corporation to recover the costs of the benefits over time. It’s a win-win that "leased" group plans simply cannot match.


![Corporate alignment retention and family security meeting]


Why Now? The Point of No Return


We are currently in a shifting economic landscape. National debt is rising, tax laws are perpetually on the chopping block, and the "war for talent" has never been more intense.


If you wait until you are 60 to realize your life insurance is "leased," you may find that your health or the sheer cost of private coverage makes it impossible to pivot. There is a "point of no return" in financial planning where the math simply stops working in your favor.


Don't let your family’s security be the weakest link in your professional life. You’ve worked too hard to leave your peace of mind in someone else's hands.


Join the Conversation


As we celebrate 20 years at Schiff Executive Benefits, we invite you to take a closer look at what you actually own. Are your benefits a permanent foundation, or are they just a temporary arrangement?


Sit back, grab your coffee, and think about the five "What Ifs." If the answers make you a little uneasy, it’s time to start a different conversation. You can explore our video library to see how these strategies work in practice, or browse our latest insights to stay ahead of the curve.


Your career is about more than just a paycheck; it’s about the legacy you leave for those you love. Make sure that legacy is built on ownership, not a lease.


Come join us, and let’s build The Perfect Plan® for your future.


They say the view from the top is spectacular, but they rarely mention that the wind is a whole lot stronger up there.


There is a common aphorism in the business world: "Success breeds complexity." For most executives and business owners, this isn't just a catchy phrase; it’s a daily reality. You’ve spent twenty or thirty years climbing the ladder, building a legacy, and reaching the zenith of your earning potential. By all traditional metrics, you’ve "made it."


Yet, for many in the 40-to-55-year-old demographic, this peak professional moment coincides with what we call the "Critical Convergence." It is the moment when your professional influence is at its highest, but your family’s financial and emotional security is at its most vulnerable.


Welcome to the Executive Sandwich.


The Weight of the "Critical Convergence"


The Executive Sandwich isn't just about being busy; it’s about being squeezed from both ends by the people you love most. On one side, you have children entering their most expensive years: think elite university tuitions, housing, and the "failure to launch" buffer. On the other side, you have aging parents whose health may be declining, requiring specialized care, assisted living, or significant financial oversight.


Nearly one in four adults in this age bracket is now providing financial support to both children and parents simultaneously. When you layer this on top of the high-end lifestyle costs consistent with executive status and the desperate need to maximize your own retirement contributions, the "squeeze" becomes a vice grip.


Have you ever stopped to ask yourself: What if I’m the one who runs out of retirement money because I was too busy funding everyone else’s life?


This is one of the core questions we address at Schiff Executive Benefits. In our mission of Restoring Alignment and Retention, we recognize that an executive who is financially stressed at home is an executive who cannot be fully present in the boardroom.


![Warm multigenerational family scene showing the sandwich generation squeeze]


The Financial Paradox of High Earners


It seems counterintuitive. How can someone making mid-to-high six figures (or seven figures) be at risk?


The reality is that the "401(k) Cap" creates a massive college funding gap for high earners. If you are limited in what you can put away in traditional tax-qualified plans, you are often forced to fund these "sandwich" expenses out of cash flow or after-tax savings.


When a $100,000-a-year tuition bill hits at the same time as a $10,000-a-month memory care bill for a parent, even a healthy executive salary starts to look thin. This is the decade where the "What Ifs" start to feel very real.


  1. What if you run out of retirement money? (The fear of the "wealth gap").

  2. What if top talent leaves? (The fear that you, as the engine of the business, are too burned out to lead).

  3. What if the business faces a buyout? (The fear that your personal financial "sandwich" makes you vulnerable during a transition).


The Human Toll: Burnout is a Business Liability


We can talk about the numbers all day, but we also have to talk about the person behind the desk. Research shows that 64% of "sandwich generation" professionals are at high risk for burnout. For women in the 40-54 age bracket, that number is even more staggering, with nearly half falling into the most severe burnout categories.


When an executive is struggling to balance a high-stakes career with caregiving responsibilities, the business suffers. We see it in unplanned absences, attrition, and a loss of institutional knowledge. In 2025 alone, nearly half a million women exited the US workplace due to caregiving pressures.


As a business owner, you have to ask: What is the cost of senior exec retirement or replacement efficiency? If your top people are leaving because they can't manage the "sandwich," your company is losing its most valuable asset: its human capital.


![Calm leadership reflection in a sunlit executive office or library]


Strategies for the Squeezed Executive


So, how do we fix it? How do we take an unstable financial environment and create a "security guarantee"?


At Schiff Executive Benefits, we don't believe in "one-size-fits-all" solutions. We look at the intersection of corporate health and personal legacy. For corporations and partnerships, this often involves sophisticated tools like Corporate Owned Life Insurance (COLI) and Non-Qualified Deferred Compensation (NQDC) plans.


The Power of COLI


Corporate Owned Life Insurance (COLI) is a powerful tool that allows a business to fund executive benefits while creating a tax-advantaged asset on the balance sheet. Unlike traditional plans, COLI doesn't have the same restrictive contribution limits, making it an ideal vehicle for bridging the retirement gap for those in the Executive Sandwich. It allows the company to support its mission of Restoring Alignment and Retention by providing the executive with a specialized benefit that addresses their unique family risks.


The Perfect Plan®


Everything we do is centered around The Perfect Plan®. This isn't just a catchy name; it’s our proprietary approach to ensuring that every piece of the financial puzzle fits together. Whether we are discussing buy/sell arrangements or 409A compliance, The Perfect Plan® is designed to ensure that the business can survive the "What Ifs."


For example, consider the "What If" of doing business with a widow. If a business partner passes away during their career peak: right in the middle of their family's riskiest decade: is the business prepared to buy out the heirs? Or are you about to find yourself in business with your late partner's spouse?


![Modern architectural shield protecting a home and office building as a financial security moat]


Why Now is the Point of No Return


As we celebrate our 20th Anniversary at Schiff Executive Benefits, we’ve seen how economic shifts can turn a manageable "sandwich" into a financial crisis. With the national debt rising and tax laws in a constant state of flux, the strategies that worked for the previous generation may not work for you.


You are in your peak earning years. This is the "make or break" decade for your legacy. You cannot afford to wait until the kids graduate or the inheritance clears to start planning. The "point of no return" is closer than you think.


If you are a business owner, you have a dual responsibility. You must protect your family from the "sandwich" while protecting your company from the loss of key talent who are facing the same pressures.


A Consultative Dialogue


I want you to take a second and think about what keeps you up at night. Is it the market volatility? Is it the thought of your top VP leaving for a competitor? Or is it the mounting pile of tuition bills and healthcare invoices sitting on your kitchen island?


These aren't just "personal problems." They are strategic business challenges.


When you work with a team of advisors who understand the nuances of executive benefits, you aren't just buying a policy; you are building a moat around your life's work.


Let’s Talk


The Executive Sandwich is a reality of modern success, but it doesn't have to be a recipe for disaster. By utilizing The Perfect Plan® and exploring strategies like COLI and tailored deferred compensation, you can navigate this "riskiest decade" with confidence.


You’ve worked too hard to let the "Critical Convergence" derail your future. It’s time to move from anxiety to security.


So, grab your coffee, sit back, and really look at your current plan. Is it actually protecting you? Or is it just a collection of various products that don't talk to each other?


If you’re ready to see how we can help align your corporate goals with your personal legacy, we’d love to have a conversation. You can explore more of our insights on our blog feed or reach out to us directly.


Let’s make sure your career peak is remembered for your achievements, not for the risks you didn't see coming.


Schiff Executive Benefits: Restoring Alignment and Retention.


For more information on our specific services and how we handle executive legacy planning, visit our services page.


Money doesn’t come with an instruction manual, but it certainly comes with a lot of noise. If you’ve spent any time watching cable news or scrolling through financial blogs, you’ve heard the "experts" shouting the same scripts. They tell you to pay off your mortgage, max out your 401(k), and avoid insurance like the plague because "commissions are evil."


For 95% of the population, that advice is perfectly fine. It’s the financial equivalent of "eat your vegetables and go for a walk." It’s safe. It’s generic. And for a high-net-worth business owner, it’s a recipe for massive tax leakage and missed opportunities.


There is a fundamental truth in the world of high-level finance: What works for the masses will often fail the masters. If you are running a successful company, managing a complex balance sheet, and looking at a legacy that spans generations, you aren't playing the same game as the person Suze Orman is talking to. You need your money to work harder. You need what I call "Double Duty Dollars."


The Mass-Market Trap


Early in my career, I started to notice a pattern. I’d sit down with business owners who were incredibly savvy in their own industries but were following "safe" retail financial advice. They had millions sitting in taxable accounts, getting clipped by the IRS every single year. They had significant "What If" risks: what if a partner dies? What if they need long-term care? What if their top talent gets poached? — but they were trying to solve those problems with separate, inefficient buckets of money.


The mass-market advice says: "Buy term and invest the rest." That sounds great on a bumper sticker. But for a business owner, "investing the rest" in a taxable environment means you’re essentially volunteering to give the government a 30% to 40% cut of your growth every year.


I realized early on that the truly wealthy don't look at their assets as isolated piles of cash. They look for ways to make one dollar do the work of two or three. They look for the "wrapper."


A confident business owner in a modern office contemplating high-net-worth asset protection strategies.


What Are Double Duty Dollars?


The concept of Double Duty Dollars is actually quite simple, though the execution requires precision. Think about an asset you already own: perhaps a high-yield savings account, a bond portfolio, or a taxable brokerage account. That dollar is currently doing "Single Duty." It’s providing some growth or liquidity, but it’s also creating a tax bill, and it’s doing nothing to protect your business or your family.


Now, imagine taking that same dollar and putting a "wrapper" around it.


By using a Corporate Owned Life Insurance (COLI) structure or a similar strategic vehicle, you take that taxable asset and transform it. Suddenly, that single dollar is doing "Double Duty" (or even Triple Duty):


  1. Tax Efficiency: The asset now grows tax-deferred. When structured correctly, the gains can be accessed tax-free. You’ve just plugged the tax leak.

  2. The Death Benefit: That same dollar now provides a significant infusion of liquidity to the business or family upon your passing. This solves the "What If" of a business surviving a widow or funding a buy-out.

  3. Living Benefits (LTC): This is the one that keeps most people up at night. If you need long-term care, you can often access that same death benefit while you’re still alive to pay for it.


You haven't spent more money. You’ve just changed the nature of the money you already had. You’ve moved it from a "Single Duty" bucket to a "Double Duty" bucket.


Addressing the Stigma: Design Over Product


I know what some of you are thinking. "Matt, you’re talking about insurance. I’ve heard insurance is a bad investment."


I get it. The insurance industry has a bit of a reputation problem, and frankly, it’s often earned. Many people have been sold a "product" by a guy who was just looking for a commission. They were sold a "policy" that didn't fit their needs or wasn't structured for maximum efficiency.


But here is our mantra at Schiff Executive Benefits: Design Over Product.


A hammer is a product. In the hands of a toddler, it’s a disaster. In the hands of a master carpenter, it builds a mansion. The "product" (the insurance contract) is just the tool. The "design" is the architectural blueprint that ensures the tool is doing exactly what you need it to do: minimizing costs, maximizing tax-free growth, and providing the protection your specific business requires.


When we talk about Double Duty Dollars, we aren't talking about "buying a policy." We are talking about engineering a financial structure that provides Restoring Alignment and Retention. We are talking about using COLI to fund a 409A plan to keep your top talent from leaving for a competitor. We are talking about Split Dollar arrangements that provide massive value to executives without the immediate tax sting.


A financial advisor discussing customized executive benefit plans with a business owner couple.


The 5 "What Ifs" That Keep You Up At Night


As a business owner, your mind is constantly scanning the horizon for threats. We’ve distilled these anxieties into five core questions. These are the "What Ifs" that Double Duty Dollars are designed to answer:


  1. The Widow Factor: What happens if your business partner passes away? Are you prepared to run the company with their spouse as your new partner?

  2. The Buy-Out: If you need to exit, where is the liquidity coming from? Can the business survive a massive cash drain to buy out a departing owner?

  3. The Talent Drain: If your "right-hand person" leaves tomorrow, what does that cost you in lost revenue and replacement expenses?

  4. The Efficiency Gap: Are you funding executive retirements in the most cost-effective way possible, or are you just burning cash?

  5. The "Running Out" Fear: Will you actually have enough to maintain your lifestyle, or will a 10-year stint in long-term care wipe out the legacy you spent 40 years building?


Mass-market advice doesn't have a cohesive answer for these. It tells you to "save more." Double Duty Dollars tell you to "save smarter."


Moving Beyond the "Safe" Advice


If you’re still following the advice meant for someone with a $50,000 salary and a 15-year mortgage, you are leaving your business vulnerable. You are likely overpaying the IRS, and you are definitely leaving your "What If" risks unaddressed.


Think about the "wrapper" concept. If you have cash sitting on your corporate balance sheet or in your personal accounts that is currently being taxed, you have a candidate for Double Duty. By moving that asset into a designed structure, you aren't "spending" the money: you’re protecting it. You’re giving it a job description that includes growth, protection, and tax-free access.


This isn't just about wealth; it’s about certainty. It’s about knowing that whether you live a long, healthy life or face a sudden health crisis, your "Perfect Plan®" is already in motion.


Why Design Matters Now


We are living in an era of shifting tax codes and economic uncertainty. The national debt isn't getting smaller, and the likelihood of taxes going down for high-earners in the long run is, let's face it, slim.


The time to put the "wrapper" on your assets isn't when the crisis hits. It’s now, while you are healthy and your business is thriving. It’s about taking control of the narrative before the government or the market does it for you.


At Schiff Executive Benefits, we don't start with a product. We start with a conversation. We look at your "What Ifs," analyze your current asset structure, and then — and only then: do we look at the tools. Whether it's a Split Dollar arrangement for your key execs, an ESOP transition strategy, or a COLI-funded retirement plan, the goal is always the same: efficiency and protection.


Your Next Step


If you’ve reached a point where you realize the "safe" advice isn't doing the job anymore, it’s time to look at your dollars differently. You’ve worked too hard to build your business to let it be dismantled by inefficient planning or unforeseen risks.


Let’s stop the tax leakage. Let’s protect your top talent. Let’s make sure your legacy is secure.


Sit back, grab your coffee, and let’s talk about how to get your money doing Double Duty.


Are you ready to build The Perfect Plan®?


Click here to schedule a consultation with Schiff Executive Benefits and let’s start restoring alignment to your business and your future.


Ready to talk?


If you’re thinking about how to protect your business, retain your top talent, and bring more certainty to your long-term plan, let’s have a conversation.


Schedule your initial NQDC meeting


A business is only as strong as the people who power it. It’s a universal truth that every CEO and business owner understands deep down: your top 10% of talent usually accounts for 90% of your forward momentum. But here is the paradox of modern business: the more valuable an employee becomes, the harder it is to reward them through traditional channels.


If you’ve ever felt the frustration of wanting to write a significant "thank you" check to a key executive, only to have your HR director or CPA tell you that "IRS non-discrimination rules" won't allow it, you’re not alone. The standard tools we use to reward the masses: like the 401(k) or traditional profit sharing: are designed to be broad, not deep. They are built for equality, not for equity.


At Schiff Executive Benefits, we believe in Restoring Alignment and Retention. Sometimes, the most "fair" thing you can do for your business is to be strategically "discriminatory."


The 401(k) Cap Problem: When "Fair" Isn't Enough


We often talk about the 401(k) cap problem. For your average employee, a 401(k) is a fantastic tool. But for your high-earners: the people navigating your company through choppy economic waters: those IRS contribution limits are a drop in the bucket. When someone earning $350,000 is capped at the same contribution level as someone earning $75,000, their "replacement ratio" at retirement plummets.


This creates a massive gap. And that gap is exactly where your competitors look when they try to headhunt your best people. It leads us to one of the central "What If" questions we ask our clients: What if your top talent leaves?


If you can’t reward them significantly more than the person in the cubicle next to them, why should they stay when a competitor offers a 20% bump and a signing bonus? This is where the Restricted Executive Bonus Plan (REBP) enters the chat.


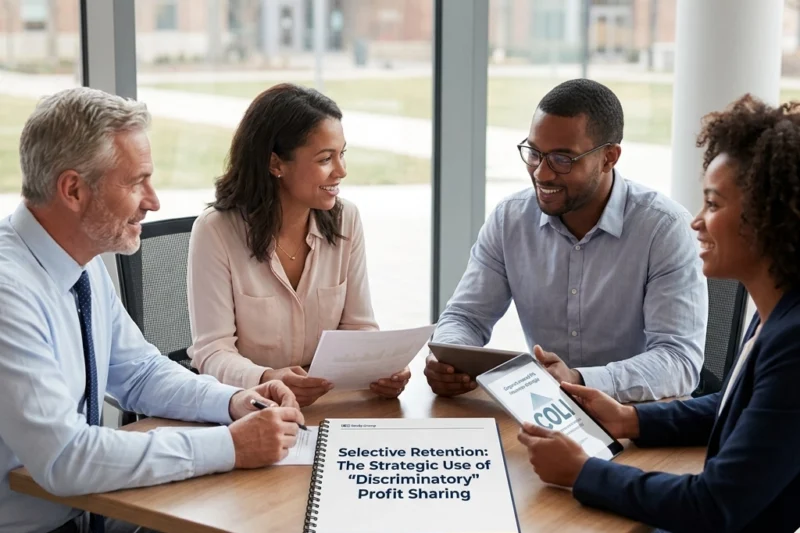
Strategic planning session for executive retention using a Restricted Executive Bonus Plan in a modern office.


Enter the Restricted Executive Bonus Plan (REBP)


"Discriminatory" is usually a dirty word in corporate America, but in the world of executive benefits, it’s a strategic superpower. A Restricted Executive Bonus Plan (REBP), often referred to as a Section 162 Plan, allows you to pick and choose exactly who you want to reward.


No testing. No filings. No "top-heavy" worries.


How It Works (The Technical "Why")


The REBP is a non-qualified plan that uses a life insurance contract (typically Corporate Owned Life Insurance or COLI) as the funding vehicle. Here’s the simplified flow:


  1. The Bonus: The company pays a bonus to the executive.

  2. The Policy: That bonus is used to pay the premium on a permanent life insurance policy owned by the executive.

  3. The Tax Treatment: The bonus is tax-deductible to the employer as compensation. The executive pays income tax on the bonus amount (though many companies "double-bonus" to cover the tax hit).

  4. The Growth: Inside the policy, the cash value grows on a tax-deferred basis.

  5. The Access: Later in life, the executive can access that cash value through tax-free loans and withdrawals to supplement their retirement.


It sounds simple because, compared to a qualified plan, it is. But the "Restricted" part of the REBP is where the magic happens for the employer.


The "Golden Handcuffs": Putting the 'Restricted' in REBP


A standard executive bonus plan is great, but it doesn't solve the retention problem. If you give someone a bonus today and they leave tomorrow, you’ve just funded their exit.


The Restricted Executive Bonus Plan adds a specialized endorsement to the policy. This legal agreement restricts the executive’s access to the policy’s cash value for a specific period: say, five, ten, or fifteen years. This is what we call "Golden Handcuffs."


If the executive stays, the restrictions are eventually lifted, and they gain full control of a valuable, tax-advantaged asset. If they leave early? They walk away from a significant portion of that wealth.


Does this sound like a more effective way to handle the "What If" of top talent leaving? It creates a "stay" incentive that grows more valuable every single year the executive remains with the firm.


NQDC Panel NYC 2026


Why Employers Love the REBP


When Matt Schiff sits down with a President or business owner, the conversation usually turns to the bottom line. From an employer's perspective, the REBP offers three major wins:


  • Immediate Tax Deductibility: Unlike many deferred compensation plans where you have to wait until the employee retires to take the deduction, REBP bonuses are deductible now.

  • Simple Administration: You don’t need an army of actuaries. There is no ERISA reporting (in most cases) and no complex non-discrimination testing.

  • Total Control: You decide who participates, how much they get, and how long the "handcuffs" stay on. You can reward your VP of Operations differently than your CFO.


Why Executives Love the REBP


For the high-performing executive, the REBP solves the "tax-heavy" retirement problem.


  • Tax-Deferred Growth: The policy grows without a 1099 every year.

  • Portability: This is a huge selling point. The executive owns the policy. If the company is sold or if they fulfill their vesting period and move on, they take the plan with them. It isn’t tied to the company’s general creditors like a traditional deferred compensation plan might be.

  • Death Benefit: It provides immediate protection for their family, which is often a secondary but highly valued benefit.


Integrating the Strategy into The Perfect Plan®


We don't look at these tools in a vacuum. A Restricted Executive Bonus Plan is just one piece of the puzzle. When we design The Perfect Plan®, we look at your entire corporate structure.


Are you a partnership looking for succession planning? Are you a corporation worried about the cost of senior executive retirement?


The goal is to move from a state of uncertainty to a state of security. Many business owners lie awake at night wondering if their key people are happy. They wonder if the business could survive a sudden departure. By implementing a selective, discriminatory profit-sharing strategy, you aren't just "paying people more": you are building a fortress around your most valuable assets.


Collaborative Meeting Session


Is It Time to Be Selective?


The transition from a standard "everyone gets the same" mentality to a "strategic retention" mentality can feel like a big shift. But in an unstable economic environment, the risk of doing nothing is far greater than the risk of being selective.


Think about your "top five." The five people whose absence would cause your phone to ring at 3:00 AM. Are they currently incentivized to stay for the next decade? Or are they one LinkedIn message away from a new zip code?


If you want to explore how to reward your best people without the constraints of qualified plans, we should talk. It’s about more than just numbers; it’s about your professional legacy and the long-term health of your company.


Grab a coffee, sit back, and think about what your "Perfect Plan" looks like. When you're ready to stop worrying about the "What Ifs" and start building a strategy that restores alignment, come join us.


We’ve been doing this for over 20 years, and we’d love to help you build it your way.


Ready to see how a Restricted Executive Bonus Plan fits into your business? Explore our services or reach out to Matt and the team today.


It is often said that the hardest part of any journey isn’t the climb to the summit; it’s the descent back to the bottom. For decades, you’ve poured every ounce of your energy, your capital, and your identity into building your business. You’ve reached the peak. But as you look out over the horizon, a new reality is setting in: 63% of U.S. entrepreneurs are planning to exit their businesses in the next few years.

We call this the "Exit Wave." It’s a massive transfer of wealth and leadership that is currently reshaping the American landscape. But here is the undeniable truth that keeps many owners up at night: building a business is a completely different skill set than exiting one.

If you find yourself staring at the calendar and wondering what the next chapter looks like, you aren't alone. You’re facing the Business Owner’s Dilemma. It’s a complex web of financial strategy, personal identity, and legacy. So, sit back, grab your coffee, and let's talk about how to navigate the descent safely and successfully.

The Reinvestment Trap


For years, your business has been your most reliable ATM. Whenever you had extra cash flow, the logical move was to put it back into the company. New equipment, better talent, bigger marketing budgets: it all fueled the growth that got you to where you are today.

But there’s a tipping point. Many founders admit they haven't accumulated as much personal wealth as they could have because they’ve been "doubling down" on their own equity for thirty years. This leads to the first part of the dilemma: Reinvestment.

When do you stop feeding the machine and start feeding your future?

The Exit Wave is being driven by owners who realize that having 90% of their net worth tied up in a single, illiquid asset is a high-stakes gamble. As we move closer to the "point of no return," the goal shifts from maximizing enterprise value to maximizing net proceeds and personal security.

Matt Schiff - Podcast Setup

The Three Dilemmas of the Modern Founder


In a recent conversation on The Perfect Plan® Podcast, we broke down the three specific dilemmas every business owner must face before they sign the closing documents.

1. The Reinvestment Dilemma


As mentioned, this is the struggle of cash flow. Do you keep growing, or do you start diversifying? If you sell tomorrow, what does that cash do for you? Many owners fear that once they sell, they lose their greatest "engine" for wealth. We help clients look at strategies like Corporate Owned Life Insurance (COLI) or deferred compensation plans to create a transition that doesn't feel like a cold-turkey stop to their financial momentum.

2. The Purpose Dilemma


What is the wealth actually for? This sounds like a simple question, but for a founder whose identity is "The Boss," "The Innovator," or "The Provider," the answer is often elusive. Is the wealth for your children? Is it for a second act in philanthropy? Or is it simply to buy back your time? Without a clear purpose, the "Exit Wave" can feel more like a wipeout.

3. The Exit Dilemma


This is the "Identity Crisis." When you walk into a room and people no longer ask you about the company, who are you? The Exit Dilemma is about lifestyle. It’s about the "Return on Life Experience" (ROLE) rather than just the "Return on Investment" (ROI).

Business owner enjoying a serene landscape, representing the Return on Life Experience after a successful business exit.

ROI vs. ROLE: A Shift in Perspective


In the world of finance, we are trained to obsess over ROI. We look at the multiples, the EBITDA, and the tax efficiency. And while those are vital, they aren't the whole story.

At Schiff Executive Benefits, we talk a lot about ROLE: Return on Life Experience.

Think about it this way: If you sell your business for $20 million but lose your connection to your community, your health, or your sense of purpose, was it a good trade? The Exit Wave is forcing owners to ask: "What does my 'Perfect Plan®' look like for the next 30 years?"

It’s about restoring alignment between your bank account and your heartbeat.

The Family Business Maze


If you are running a family business, the complexity of the Exit Wave multiplies. You aren't just dealing with a buyer and a seller; you’re dealing with Thanksgiving dinner.

The dilemma here is three-fold:

  • Ownership Dynamics: Who owns the shares?

  • Family Dynamics: Who gets the "say" in how things are run?

  • Non-Family Dynamics: How do you retain the key executives who aren't in the family but are essential to the company's value?


This is where things like buy/sell arrangements and retention strategies become critical. If your top talent sees the "Exit Wave" coming and fears for their job security, they might jump ship before you can even get the business to market.

We often ask our clients one of our core "What If" questions: What if your top talent leaves right when you are trying to sell? Your valuation would crater. Protecting that talent through Split Dollar or 409A plans is how you ensure the mountain descent remains stable.

Collaborative Meeting Session

The Mountain Climbing Analogy: Planning the Descent


I often tell my clients that they are world-class mountain climbers. You’ve braved the storms, you’ve navigated the crevasses, and you are standing on the peak. But most climbing accidents happen on the way down.

Why? Because the descent requires a different kind of focus. You’re tired. The weather is changing. And you might be rushing because you can see the finish line.

Planning for your business exit is your descent. You need a team of advisors: a "Sherpa" of sorts: to make sure you don't slip. This means coordinating your legal team, your tax professionals, and your executive benefit specialists.

Are you prepared for the "5 What Ifs"?

  1. What happens to the business with a widow at the helm?

  2. Is your buy-out agreement funded and up to date?

  3. How do you stop your top talent from leaving for a competitor?

  4. Can you replace a senior executive without it costing you a fortune?

  5. Are you at risk of running out of money in retirement because you didn't plan the tax-efficient distribution?


These aren't just technical questions; they are the anchors that keep you attached to the mountain.

Matt Schiff - Grand Staircase Wisdom

Restoring Alignment and Retention


As the President of Schiff Executive Benefits, my mission is simple: Restoring Alignment and Retention.

When you are caught in the 63% Exit Wave, alignment is the first thing to go. You’re pulled between the needs of the business and the needs of your family. You’re pulled between your legacy and your liquidity.

By using sophisticated tools like COLI and tailored executive benefit packages, we help you lock in the value of your company while simultaneously preparing your personal balance sheet for the "ROLE" you’ve earned.

Whether you’re looking at an ESOP, selling to a strategic buyer, or passing the torch to the next generation, you need a strategy that considers the human element as much as the financial one.

Ready to Talk?


The Exit Wave is coming. You can either be swept away by it, or you can ride it to the shore of your next great adventure.

Don't wait until the "point of no return" to start thinking about these dilemmas. Let’s start the conversation now. We can help you look at your current setup, stress-test your retention plans, and ensure your The Perfect Plan® is actually perfect for you.

Ready to talk? Book an initial meeting here.

To learn more about how we help business owners navigate these complexities, feel free to explore our video library of services or browse our latest insights.

Success is a journey, but the exit is a choice. Make sure yours is a choice you can live with — and enjoy: for the rest of your life.


"An ounce of prevention is worth a pound of cure."


Benjamin Franklin said that over two centuries ago, and while he wasn’t specifically talking about nonqualified deferred compensation (NQDC), he might as well have been. In the world of executive benefits, the "cure" for a compliance failure isn't just expensive: it’s often catastrophic for the very people you are trying to reward.


If you are a CEO, a CFO, or a Board Member, what keeps you up at night? Is it the fear of losing your top talent to a competitor? Is it the complexity of your succession plan? Or is it the "What If" of an IRS audit landing on your desk and revealing that the benefit plans you put in place 15 or 20 years ago are actually ticking tax bombs?


We often see companies that established their executive benefit structures during the massive regulatory shift of 2008 and 2009. At the time, everyone scrambled to comply with the then-new IRC Section 409A rules. But here is the problem: a plan that was "compliant" on paper in 2008 has likely suffered from "operational drift" in the decades since.


If you want a surprisingly mainstream illustration of just how technical this gets, this short Suits clip is worth watching near the start of this conversation: https://youtu.be/tcx3zwhEIOw?si=9uCcfcCFS3AqfwdF. In the scene, Mike Ross correctly points out that backdating stock options is not automatically illegal by itself. The real legal landmines are the disclosure requirements and the downstream IRC Section 409A consequences. That’s exactly the point. 409A is so complex, so technical, and so unforgiving that it becomes a litmus test for a truly world-class legal mind. And for any company that has not had technical experts audit its plan design and administration, it is also a major source of hidden risk.


At Schiff Executive Benefits, we call this the 2008 Plan Trap. It’s the dangerous assumption that because a plan was set up correctly once, it remains healthy today.


The Ghost of 2008: Why 409A Still Matters


For those who need a refresher, Internal Revenue Code Section 409A was born out of the Enron scandal. It governs how and when deferred compensation is elected and paid out. The rules are notoriously rigid. By January 1, 2009, every nonqualified plan in America had to be amended to meet these strict requirements.


The penalties for missing the mark are some of the most punitive in the entire tax code. If a plan fails to comply with 409A: either in its written form or in how it is actually operated: the consequences include:


  1. Immediate Taxation: All amounts deferred under the plan (including all previous years' deferrals and earnings) become immediately taxable to the executive.

  2. 20% Penalty Tax: A flat 20% additional income tax is levied on the executive.

  3. Interest Penalties: The IRS tacks on premium interest rates for the underpayment of taxes.


Note that these penalties fall on the executive, not the company. Imagine telling your top performer: the person you are trying to "attract, retain, and reward": that because of an administrative error, they suddenly owe the IRS 60% or more of their total deferred savings. That is the ultimate way to ensure your top talent leaves, and it completely undermines our mission of Restoring Alignment and Retention.


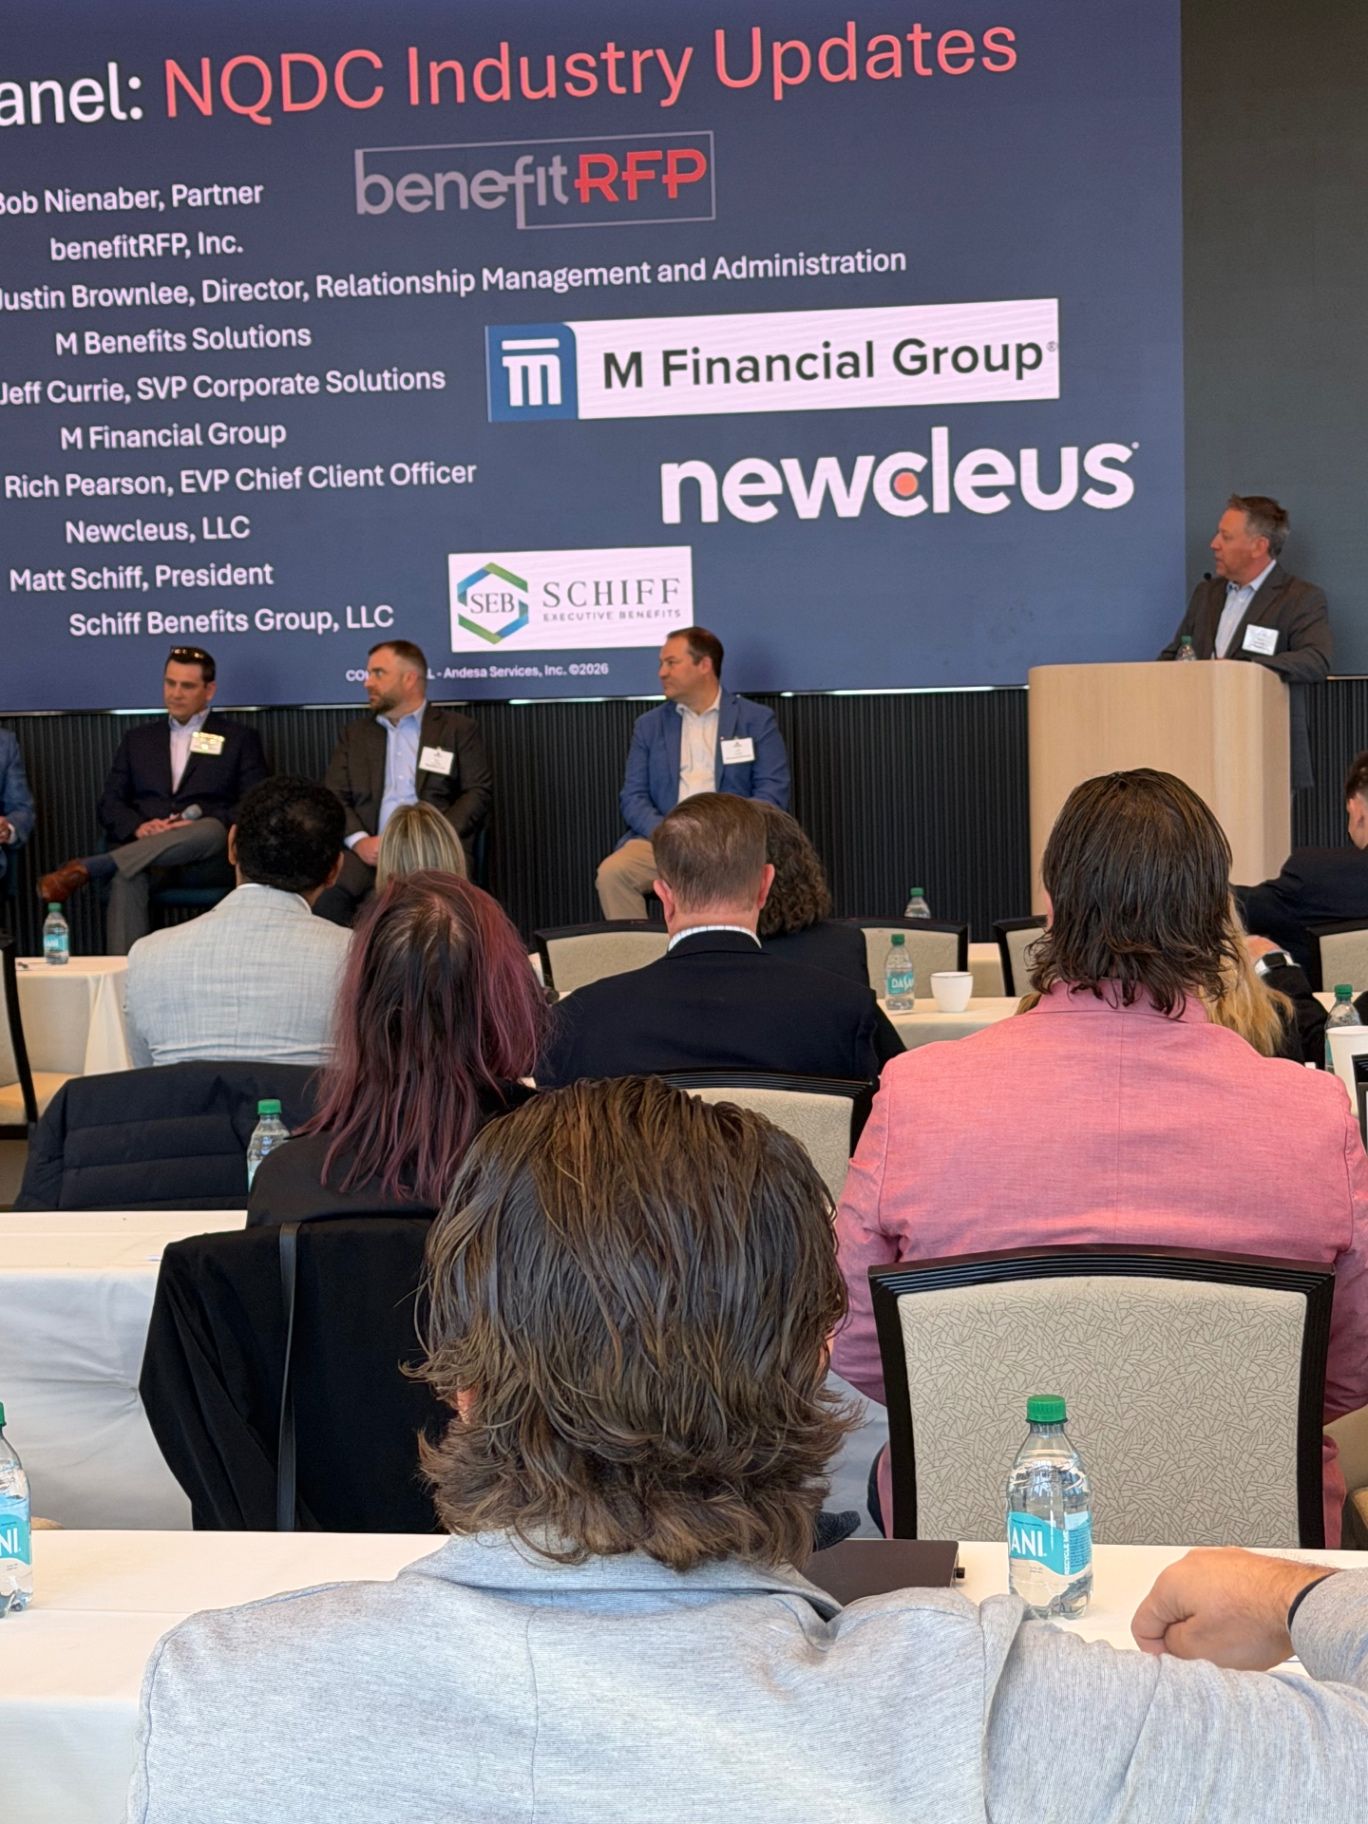
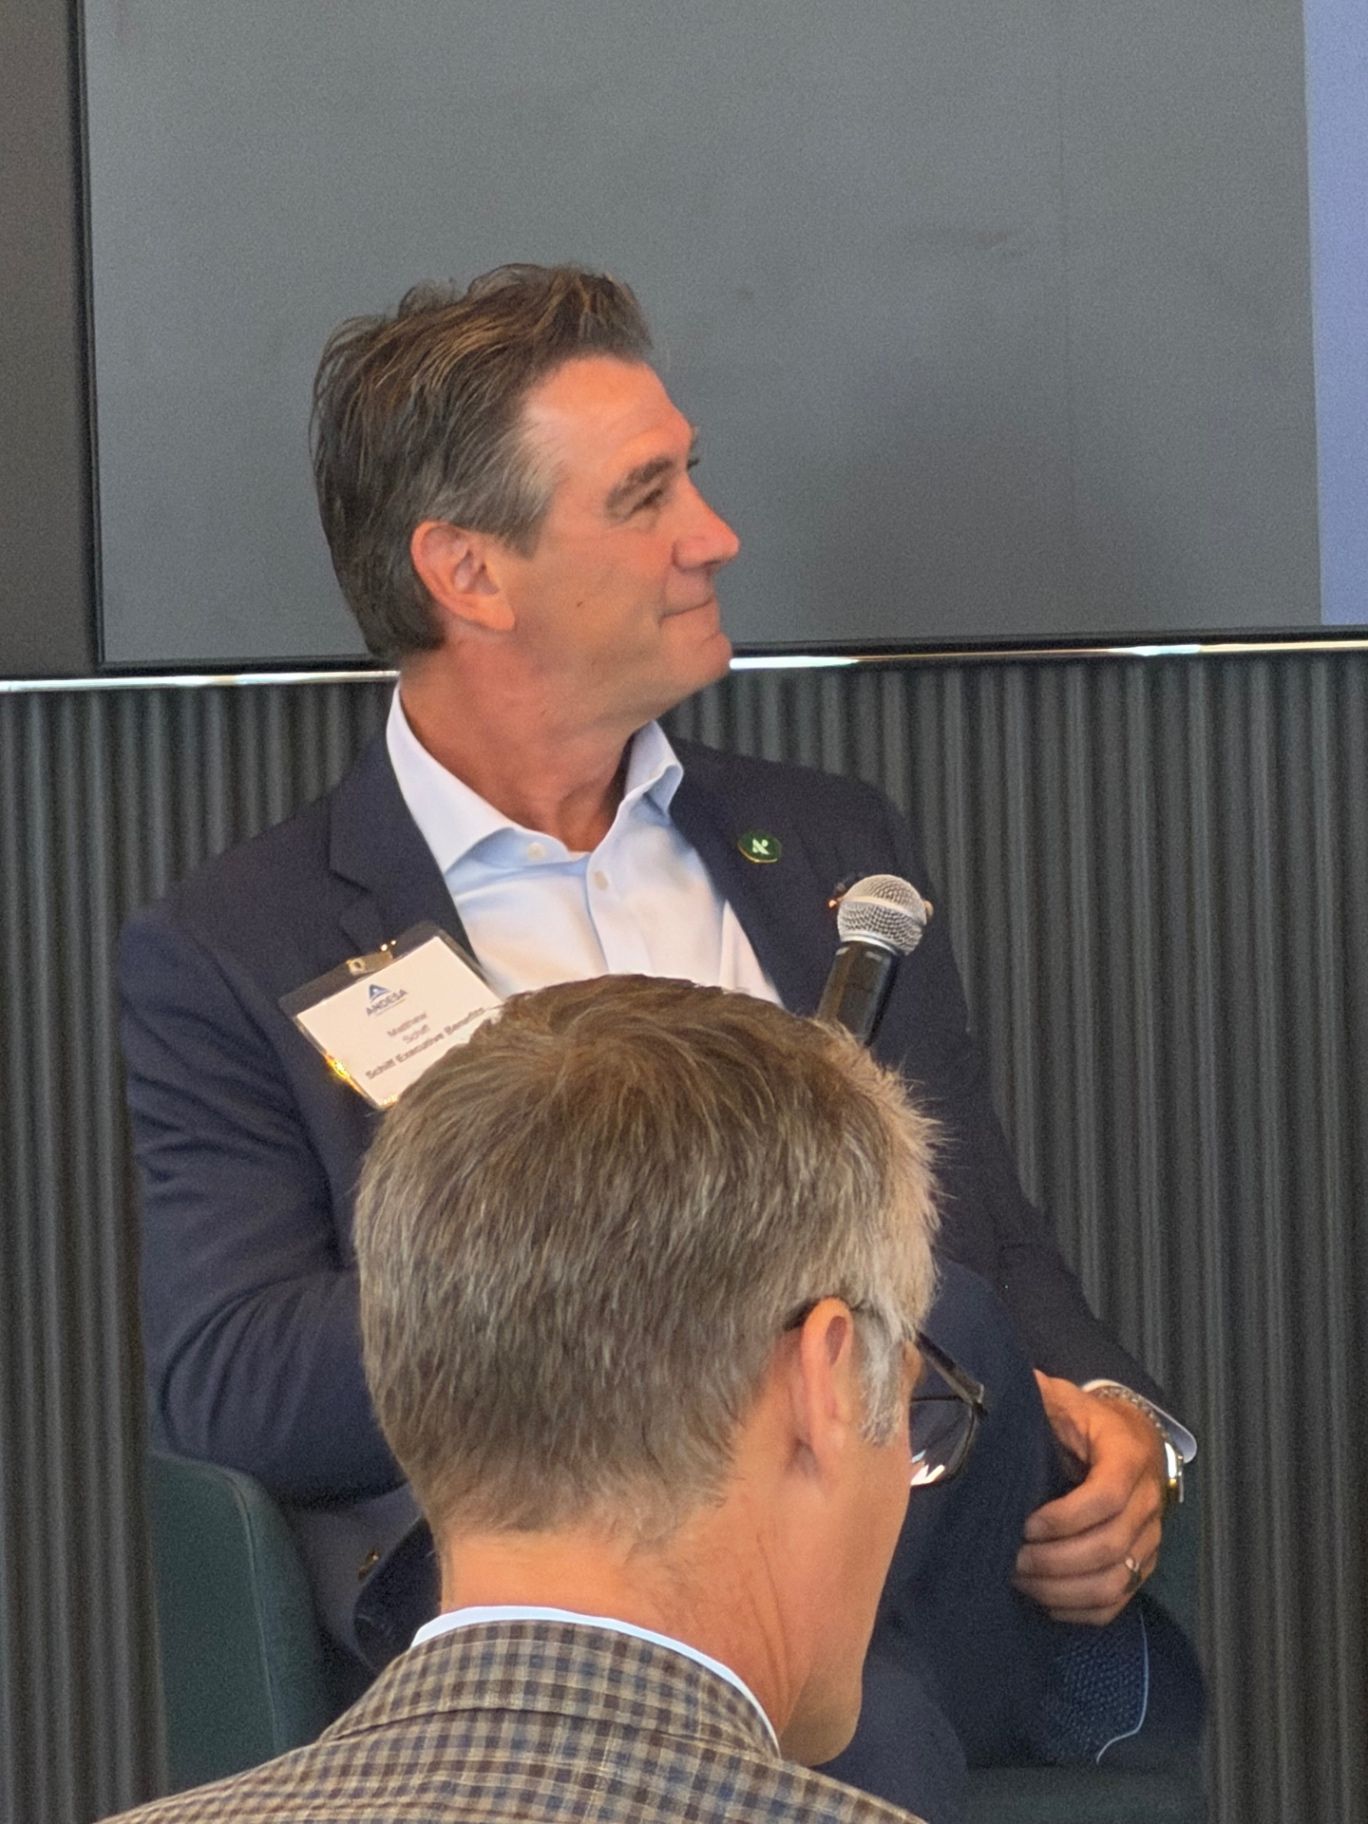
Matt Schiff Speaking NQDC Matt Schiff speaking at the NQDC Industry Updates panel in NYC.


The Danger of Operational Drift


During my time serving as a member of the AALU's (now Finseca) NQDC Committee, I had the opportunity to provide technical input on and provide feedback on these very regulations. I saw firsthand the intent behind the law. The goal was transparency and consistency.


However, 15 to 20 years is a long time in the corporate world. Administrators change, HR departments turn over, and CFOs retire. Over time, the "operational drift" begins.


You might have a plan document that says payouts occur upon "Separation from Service." But then, a retiring executive asks for their payout three months early to buy a vacation home, and a well-meaning HR manager approves it. That is a 409A violation.


Or perhaps your plan document defines "Disability" using a specific insurance carrier’s definition, but you changed carriers five years ago, and the new definition doesn’t match. That is a potential 409A violation.


When was the last time you actually audited the operation of your plan against the written document? If it was more than three years ago, you are likely caught in the trap.


The 101(j) Compliance Hole: A COLI Nightmare


While 409A is the big monster in the room, there is another technical pitfall that often haunts older plans: IRC Section 101(j).


Most executive benefit plans are informally funded using Corporate Owned Life Insurance (COLI). In 2006, Congress enacted Section 101(j) to ensure that employees were notified and consented to the company owning a policy on their life.


If you don’t have a signed "Notice and Consent" form before the policy is issued, the death benefit: which is normally tax-free: becomes fully taxable to the corporation.


We frequently audit plans from the 2006–2010 era and find that while the policies were purchased, the 101(j) documentation is either missing, unsigned, or lost in a filing cabinet from two mergers ago. If your COLI portfolio isn't 101(j) compliant, you aren't just losing a tax benefit; you are creating a massive liability for the business.


NQDC Panel NYC 2026 Panel discussion: NQDC Industry Updates at the 2026 National COLI Directors Meeting in NYC.


Why Older Plans Need a "Technical Audit" Today


If your plan is a teenager (15+ years old), it’s time for a checkup. Economic environments shift, and your business goals have likely evolved. The plan you designed when you had 50 employees may no longer serve a company of 500.


Beyond the threat of IRS penalties, there are strategic reasons to audit these legacy structures:


  • Tax Efficiency: Tax laws regarding corporate owned life insurance and deferred compensation have evolved. You might be using an "Old School" design that is significantly less efficient than current structures.

  • The "What If" Questions: Does your plan address what happens if a senior executive retires unexpectedly? Does it clearly define the replacement cost efficiency? (One of our core five "What Ifs").

  • Participant Communication: Do your executives actually understand the value of what they have? If they don't value it, it's not retaining them.


Professional review of executive benefit plan documents during a 409A compliance technical audit.


Moving Toward The Perfect Plan®


At Schiff Executive Benefits, we don't believe in "set and forget." We believe in constant alignment. When we step in to rescue a plan from the 2008 Trap, we guide clients through a transition to The Perfect Plan® structure.


What makes a plan "Perfect"? It’s a design that is:


  1. Technically Sound: Rigorous compliance with 409A and 101(j) so you can sleep at night.

  2. Flexible: Built to adapt to your company’s growth and changing tax landscapes.

  3. Transparent: Executives clearly see the wealth they are building, which keeps them locked into your organization’s long-term success.


We help you move away from the clunky, high-risk designs of the past and into a modern framework that actually delivers on its promise: realizing your dream value while protecting your legacy.


Are You Sitting on a Ticking Tax Bomb?


The IRS doesn't care if a mistake was accidental. They don't care if your previous consultant told you it was "fine." When an audit happens, the numbers speak for themselves.


Don't let a plan designed in 2008 become your biggest liability in 2026. Whether it’s a 401(k) excess plan, a 457(f) for a non-profit, or a complex COLI-funded deferred comp arrangement, the details matter.


You’ve spent years building your business and your reputation. Don't let a technicality in a 20-year-old document take a 20% bite out of your executives' hard-earned savings — or a massive chunk out of your corporate balance sheet.


Ready to talk?


If you haven't had a technical audit of your executive benefits in the last few years, let’s sit down and grab a coffee. We can look under the hood and see if your current structure is still aligned with your goals, or if you’re caught in the 2008 Plan Trap.


Come join us and schedule your NQDC initial meeting here.


Let’s ensure your plan is working for you, not against you. After all, your professional legacy is too important to leave to chance.


Learn more: 409A compliance, design, and strategy.


It is a universal, undeniable truth that the roles we play in our families eventually come full circle. We spend the first quarter of our lives being cared for by our parents, and if we are fortunate enough to reach our professional peak, we often spend the third quarter returning the favor.


For many high-achieving leaders, this isn’t just a personal transition; it’s a strategic collision. You are currently in what I call the Executive Sandwich.


In Part 1: The Executive Sandwich: Why Your Career Peak is Often Your Family’s Riskiest Decade, we explored how the height of your earning years is simultaneously the height of your financial vulnerability. In Part 2: Beyond the 401(k) Cap: Solving the Executive College Funding Gap, we looked at the pressure of launching the next generation. Today, we face the most emotionally taxing and financially unpredictable layer of the sandwich: caring for aging parents.


How do you provide the dignity and care your parents deserve without siphoning away the wealth you’ve spent decades building? How do you manage a C-suite schedule when a midnight phone call changes everything?


At Schiff Executive Benefits, we believe in Restoring Alignment and Retention, and that includes the alignment of your personal peace of mind with your professional legacy.


The Hidden Cost of Longevity


We often talk about market risk or interest rate risk, but for the modern executive, the greatest "What If" is often Longevity Risk.


In our framework of the "5 What Ifs," we frequently ask: What if you run out of money in retirement? But long before you face that question for yourself, you may face it for your parents. Modern medicine is a miracle, but it has created a financial paradox: our parents are living longer, but not necessarily healthier.


Matt Schiff - Professional Smile Blue Suit


The cost of long-term care: whether home health aides, assisted living, or skilled nursing: is rising at a rate that far outpaces general inflation. For an executive, the cost isn't just the invoice from the facility. It is the "opportunity cost" of your time and the potential "leakage" from your investment portfolio to cover gaps in their care.


Are you prepared to liquidate a portion of your estate to cover a $15,000-a-month nursing bill that could last five or ten years? Most executives aren't. They assume they can "cash flow" it, only to realize that doing so compromises their own retirement goals and the legacy they intended to leave for their children.


The Emotional Vice


Caregiving is a full-time job. When you are managing a global team or overseeing a complex merger, the emotional weight of a parent’s declining health can be paralyzing. You find yourself in a consultative dialogue with doctors, siblings, and care coordinators, all while trying to maintain the "authoritative presence" required in the boardroom.


I recently spoke with a client: let's call him David: a CEO who was in the middle of a major acquisition. His mother suffered a stroke. Suddenly, David wasn't just managing a billion-dollar deal; he was navigating Medicare gaps and searching for a memory care facility that didn't feel like a hospital. The stress didn't just affect his sleep; it affected his decision-making.


David’s story is not unique. It is the reality of the sandwich generation. The question is: do you have a plan that protects your focus as much as it protects your capital?


Executive reflecting on aging parents photo, highlighting the financial strain of the sandwich generation.


The Strategy: Shifting the Burden to the Business


One of the most overlooked solutions in executive wealth planning is the use of Long-Term Care (LTC) riders and business-paid policies.


Many executives assume that LTC is an individual expense, paid with after-tax dollars. However, for business owners and key executives, there is a much more efficient way.


1. The Business-Paid Deductible Policy


If structured correctly through a corporation or partnership, the business can pay the premiums for a Long-Term Care policy. In many cases, these premiums are tax-deductible to the business and are not considered taxable income to the executive. This is a powerful tool for attracting and retaining top talent who are feeling the squeeze of the sandwich generation.


2. COLI with LTC Riders


Corporate Owned Life Insurance (COLI) is a cornerstone of The Perfect Plan®. By adding a Long-Term Care rider to a COLI or specialized life insurance policy, you create a "multipurpose" asset. If you (or your parents, depending on the structure) need the care, the death benefit is accelerated to pay for those expenses tax-free. If the care is never needed, the death benefit remains intact for your heirs.


3. Protecting the Portfolio


By using an insurance-based solution, you create a "firewall" around your investments. Instead of selling stocks in a down market to pay for a home health aide, you leverage the insurance company's capital. This ensures that your personal legacy: your "dream value": remains untouched.


Longevity Risk and The Perfect Plan®


When we design The Perfect Plan®, we don't just look at your balance sheet; we look at your life’s timeline. We integrate these "What If" scenarios into a cohesive strategy.


If you are a business owner, providing LTC benefits to your senior executive team is one of the most empathetic and strategic moves you can make. It rewards your best people by solving a problem that keeps them up at night, ensuring they stay focused on the business because their home life is secure.


Modern Meeting Work Scene


Starting the Conversation: A Consultative Approach


Caring for aging parents requires more than financial products; it requires a team of advisors. You need to have honest, often difficult conversations today to avoid a crisis tomorrow.


Here are three steps you can take right now:


  • Audit Your Parents' Documents: Do they have a clear Power of Attorney and a Healthcare Proxy? Without these, your ability to manage their care will be legally hamstrung.

  • Evaluate the "Care Gap": Look at their current assets versus the cost of care in their area. Where is the shortfall?

  • Explore Hybrid Solutions: Look into life insurance policies with LTC riders. These are often more palatable than "use-it-or-lose-it" traditional LTC insurance because they guarantee a payout in one form or another.


The Point of No Return


The window of opportunity to put these protections in place is often smaller than we realize. Once a diagnosis is made or a health event occurs, many of the most efficient financial strategies are off the table.


Waiting is the greatest risk to your legacy. By acting now, you aren't just buying insurance; you are buying the ability to be a daughter or a son again, rather than just a care manager. You are buying the peace of mind to sit back, grab your coffee, and focus on the people who matter most.


At Schiff Executive Benefits, we specialize in navigating these complexities. Whether it’s through Trust Owned Life Insurance (TOLI) to manage estate taxes or building a robust executive benefit suite, our mission is to ensure that your success isn't eroded by the natural cycles of life.


Conclusion: Join the Conversation


The Executive Sandwich doesn't have to be a source of constant anxiety. With the right structure, it can be a season of your life where you demonstrate your values through your actions and your foresight.


If you’re feeling the pressure of the sandwich generation and want to see how The Perfect Plan® can protect your legacy while providing for your parents, I invite you to reach out. Let’s look at your specific "What Ifs" and build a plan that restores alignment to your world.


Come join us at our next NQDC Panel or listen to The Perfect Plan® Podcast for more insights into securing your professional and personal future.


Sit back, grab your coffee, and let’s start building it your way.


: Matt Schiff
President, Schiff Executive Benefits

To explore more about our strategies for executives and corporations, visit our services page.


They say that a bird in the hand is worth two in the bush, but when you are standing at the threshold of retirement, you start wondering exactly which bush you should reach into first. For decades, you’ve been focused on one thing: accumulation. You’ve watched the numbers grow, checked your statements, and contributed to your 401(k) with the discipline of a marathon runner.


But then, the finish line appears. Suddenly, the game changes. You aren't just putting money away anymore; you have to figure out how to take it out without the tax man taking a massive bite or, even worse, running out of it before you run out of breath.


At Schiff Executive Benefits, we often talk about the five core "What If" questions that keep executives and business owners up at night. The big one we’re tackling today is the fifth: What if you run out of retirement money?


Solving that "What If" isn't just about how much you’ve saved; it’s about the design of your retirement paycheck.


The Story of Ruth: A Study in Transition


To make this real, let’s look at a case study we recently handled. Let’s call her Ruth. Ruth is a single nurse who spent her entire career caring for others. She’s been incredibly diligent, building up a solid nest egg. But as she approached her mid-60s, she felt a sense of paralysis.


Ruth had several different "buckets" of money, but no clear map on how to spend them. She was worried about whether she should take Social Security now or later. She was worried about her traditional IRA vs. her Roth. And as a single person, she was particularly concerned about the long-term: who would care for her if her health declined?


Ruth’s situation is common. Whether you are a high-level executive or a dedicated professional like Ruth, the transition from "saver" to "spender" is a psychological and mathematical hurdle. We needed to create The Perfect Plan® for her, one that turned her pile of assets into a predictable, sustainable stream of income.


Matt Schiff - Professional Smile


Understanding Your Tax Buckets


Before you can decide where your income should come from first, you have to categorize your assets. Not all dollars are created equal. In the eyes of the IRS, they live in very different neighborhoods:


  • The Pre-Tax Bucket (Traditional IRA/401(k)): This is where most people have the bulk of their savings. It’s "forever taxed" money. Every dollar you take out is taxed as ordinary income.

  • The Tax-Free Bucket (Roth IRA/401(k)): This is the holy grail. You’ve already paid taxes on this money, so it grows and comes out tax-free.

  • The Non-Qualified Bucket (Brokerage Accounts): This is money sitting in stocks, bonds, or mutual funds outside of a retirement account. You only pay taxes on the gains (capital gains), not the "cost basis" (the money you originally put in).

  • The Cash Bucket (Bank Accounts/CDs): Highly liquid, but the interest is taxed annually. In a low-interest environment, this bucket often loses purchasing power to inflation.


The goal of Retirement Paycheck Design is to coordinate these buckets so you aren't paying more to Uncle Sam than is absolutely necessary.


The Social Security Tug-of-War: 62 vs. 67 vs. 70


One of the first questions Ruth asked was, "When should I start my Social Security?"


There is a lot of "conventional wisdom" out there, but "conventional" rarely means "perfect." Here is how we look at the Social Security timeline:


Age 62: The Liquidity Play


Taking Social Security at 62 gives you immediate cash flow. For some, this is a "protection" move. If you have concerns about your health or you want to preserve your investment principal during a market downturn, taking it early might make sense. However, you are locking in a permanently reduced benefit, roughly 30% less than your full retirement age amount.


Age 67: The Full Retirement Age (FRA)


For most people retiring today, this is the "baseline." You get 100% of your promised benefit.


Age 70: The Max Benefit


If you wait until 70, your benefit increases by about 8% for every year you delay past your FRA. This is a massive "guaranteed" return that is hard to find anywhere else. However, there’s a catch: to wait until 70, you have to live off your other assets for those intervening years. You are essentially "spending down" your IRAs or brokerage accounts to "buy" a higher Social Security check later.


For Ruth, we had to weigh the math. Does she drain her liquid investments now to get a bigger check at 70? Or does she take the check now to keep her investments growing? There is no one-size-fits-all answer, which is why a customized design is essential.


Executive desk with financial planning documents for retirement income and Social Security strategy.


Beware the Age 73 "Tax Bomb"


There is a ticking clock in your retirement plan called the Required Minimum Distribution (RMD). Currently, once you hit age 73 (and moving to 75 in the future), the government forces you to take money out of your pre-tax accounts.


If you’ve been a great saver and your IRA has grown to $2 million or $3 million, those mandatory withdrawals can be huge. They can push you into a higher tax bracket, increase the cost of your Medicare premiums, and make your Social Security benefits more taxable.


We call this the RMD Tax Bomb. One of the primary goals of our design process is to "defuse" this bomb by strategically taking distributions before you are forced to, or by utilizing Roth conversions during lower-income years.


Managing the Silent Killer: Inflation


Ruth was worried about inflation, and rightly so. But we look at inflation through two different lenses: fixed costs and rising lifestyle costs.


  1. Fixed Costs: If Ruth has a mortgage with a fixed 3% interest rate, her "inflation" on that expense is effectively 0%. The payment stays the same while the value of the dollar drops.

  2. Rising Costs: Healthcare and general lifestyle expenses (travel, dining, gas) do not stay fixed. Healthcare inflation, in particular, often runs much higher than the standard Consumer Price Index (CPI).


In Ruth’s design, we ensured that her guaranteed income sources (Social Security and potential annuities) covered her fixed "must-pay" bills, while her investment portfolio was positioned to provide the "inflation-adjusted" raises she would need for her lifestyle over the next 20 to 30 years.


The Single Professional’s Risk: Long-Term Care


As a single nurse, Ruth knew better than anyone that "hope is not a strategy" when it comes to aging. Without a spouse to provide "informal" care at home, the financial burden of a long-term care event is much higher for singles.


We incorporated a strategy that looked at her assets not just as an income source, but as a reserve for care. By Restoring Alignment and Retention of her capital, we could ensure that if she ever needed help, she wouldn't have to rely on the state or be a burden on her extended family.


Modern Meeting Work Scene


Designing Your Perfect Plan®


Retirement shouldn't feel like a series of stressful guesses. It should feel like a well-earned victory lap. Whether you are concerned about your own retirement or you are an employer looking at how to attract, retain, and reward the top talent in your firm by helping them solve these same problems, the framework remains the same.


We help executives and professionals navigate the complexities of:


If you are wondering which bucket you should dip into first, don't guess. The difference between an accidental retirement and a designed one can be hundreds of thousands of dollars in taxes saved and a lifetime of peace of mind.


At Schiff Executive Benefits, we specialize in helping you find that clarity. We invite you to explore our services and video library to see how we’ve helped others in your shoes.


Ready to talk about your specific situation?


Sit back, grab your coffee, and let’s start a conversation. We can help you design a paycheck that lasts as long as you do.


Ready to talk? Click here to schedule your initial meeting.


Restoring Alignment and Retention.


Disclaimer: This blog post is for educational purposes only and does not constitute financial, legal, or tax advice. Please consult with your professional advisors before making any significant financial decisions.


Learn more: See how decanting assets turns your portfolio into retirement income you can’t outlive.


A parent’s greatest ambition is to provide a better life for their children than the one they had. It is a universal, undeniable truth that spans generations and tax brackets. We work late, we climb the corporate ladder, and we navigate high-stakes environments, often with the singular goal of ensuring our children have every opportunity: starting with a world-class education.


But for the modern executive, that ambition often runs head-first into a "math problem" that most people don’t even realize exists.


In Part 1 of our "Sandwich Generation" series, we looked at the emotional and financial toll of caring for aging parents while raising children. Today, in Part 2, we are getting tactical. We are looking upward at the looming cost of higher education and how the current legislative environment actually penalizes the highest earners in the room.


If you are an executive making $450,000 or more, you aren't just facing higher tuition bills; you are facing a structural disadvantage in how you are allowed to save for them.


The 401(k) Math Problem: A 10% Disadvantage


Most people view the 401(k) as the gold standard of retirement and savings. For the average American worker, it is. If an employee earns $150,000 a year and contributes the 2026 limit of $24,500 (plus any catch-up contributions), they are shielding roughly 16% of their income from taxes and growing it for the future.


Now, let’s look at the C-suite.


If you are an executive earning $460,000, that same $24,500 contribution represents only about 5% of your income. While your peers are saving 15% to 20% of their earnings in a tax-advantaged environment, you are capped at 5%. The remaining 95% of your income is subject to the highest marginal tax rates.


This creates a massive "Savings Gap." When the time comes to write a check to Tulane, Harvard, or Michigan, most executives are forced to do so with "expensive" dollars: money that has already been taxed at 37% or higher.


Furthermore, if you try to tap into your 401(k) to cover a tuition spike, you aren't just hit with the tax; you’re hit with a 10% early withdrawal penalty if you are under age 59½. For the Sandwich Generation executive, whose children hit college age while they are in their peak earning years (usually their 40s or 50s), the 401(k) is a locked box that is too small to begin with.


An executive reviewing university brochures while considering college funding strategies beyond the 401k cap.


The 401(k) Mirror Plan: A Pre-Tax Tuition Solution


At Schiff Executive Benefits, we focus on Restoring Alignment and Retention. One of the most powerful ways to do that is through a Nonqualified Deferred Compensation (NQDC) plan, often referred to as a "Mirror Plan."


A Mirror Plan allows executives to defer a much larger percentage of their compensation: sometimes up to 80% or 90%: into a tax-deferred account. Unlike a 401(k), there are no IRS-mandated contribution caps on NQDC plans. If you need to save $100,000 a year for your children’s education, a Mirror Plan allows you to do that with pre-tax dollars.


But the real "magic" for college funding lies in the Specific Date Withdrawal feature.


Navigating 409A: The Specific Date Strategy


Under Internal Revenue Code Section 409A, NQDC plans allow participants to schedule distributions for specific times. Unlike a 401(k), where you generally have to wait until retirement or 59½ to avoid penalties, an NQDC plan can be structured to pay out while you are still working.


Imagine your daughter is 10 years old. You know that in eight years, you will need to start paying tuition. Under a Mirror Plan, you can elect to defer a portion of your salary or bonus today and schedule that distribution to hit your bank account in exactly eight years.


The benefits are twofold:


  1. Pre-Tax Funding: You are funding the "College Fund" with gross dollars, not net dollars. This significantly increases your "buying power" for tuition.

  2. No 10% Penalty: Because these plans are designed for flexibility, you avoid the early withdrawal penalties associated with traditional retirement accounts.


It is a tactical, solution-oriented way to ensure that your "Sandwich" years don't result in you running out of retirement money: one of the core "What Ifs" we help business owners and executives solve.


Matt Schiff Speaking NQDC


Why Companies Offer the "College Funding" Benefit


You might ask, "Why would my company set this up for me?"


The answer is simple: Executive Retention.


In today’s market, losing a top-tier executive costs a company significantly more than just their salary. It costs institutional knowledge, client relationships, and momentum. By offering a Mirror Plan, a company provides a "Golden Handshake" that solves the executive's most pressing personal anxiety: paying for their children’s future without sacrificing their own retirement.


When a company helps an executive solve the "401(k) Math Problem," they aren't just providing a benefit; they are building a bridge of loyalty. We call this The 401(k) Cap Problem: How a Mirror Plan Rewards Your Best People.


Integrating the Mirror Plan into The Perfect Plan®


At Schiff Executive Benefits, we don't look at these tools in a vacuum. A Mirror Plan is one piece of a larger puzzle we call The Perfect Plan®.


Whether we are discussing Corporate Owned Life Insurance (COLI) to informally fund these obligations or structured buy/sell arrangements, the goal is always the same: clarity.


We often see executives who are "over-funded" in their 401(k) but "under-saved" for their specific life goals. They have the assets, but they don't have the liquidity or the tax efficiency they need when the tuition bill arrives.


By utilizing a Mirror Plan, you can keep your 401(k) on track for your 70s while using your deferred compensation to handle your 50s.


Executive couple meeting with a consultant to discuss a Mirror Plan for retirement and education savings.


The Professional’s Legacy


We often talk about the "5 What Ifs" that keep business owners awake at night. When it comes to the Sandwich Generation, the fear of Senior exec retirement/replacement cost efficiency and running out of retirement money are top of mind.


But there is a deeper, more personal "What If": What if I can't provide the same level of education for my kids that my parents provided for me?


Economic shifts and rising tuition costs have made the "standard" path: saving in a 529 and maxing out a 401(k): insufficient for high earners. You need a strategy that reflects your income level. You need a strategy that recognizes that as an executive, the rules of the game are different for you.


Tactical Summary for the Executive


If you are looking at your 401(k) and realizing it won't cover the gap, consider these steps:


  • Audit your "Savings Gap": Calculate what percentage of your total income is actually protected by tax-advantaged accounts. If it's less than 10%, you have a cap problem.

  • Review the Plan Documents: Does your company offer an NQDC or Mirror Plan? If so, does it allow for "In-Service" or "Specific Date" distributions?

  • Coordinate with your Team: Ensure your tax advisor and financial consultant are looking at your deferrals as part of a holistic education funding strategy, not just a retirement strategy.


Join the Conversation


Solving the college funding gap is about more than just numbers; it’s about peace of mind. It’s about knowing that while you are leading your company toward its goals, your family’s future is being secured with the same level of executive precision.


If you are a business owner looking to reward your top talent, or an executive trying to navigate the "Sandwich" years, we invite you to sit back, grab your coffee, and explore how we can help.


Check out our latest insights on The Perfect Plan® Podcast or reach out to our team to discuss how a Mirror Plan can work for your organization.


Stay tuned for Part 3 of our series, where we will dive into the "Downstage" of the Sandwich: Caring for Aging Parents without Derailing Your Corporate Legacy.


Official SEB Mini Logo


Restoring Alignment and Retention.