Hi, How Can We Help You?
  • Planning for all of life's "What Ifs".

Category Archives: Employee Retention

A business is only as strong as the people who help build it. That truth is simple, but its consequences are not.

The best way to retain key employees is to combine meaningful leadership, competitive total compensation, visible career opportunity, and a carefully designed executive benefits strategy that connects the employee’s future to the company’s future.

That does not mean offering every possible perk. It means understanding what your most valuable people need, identifying what keeps them committed, and building a plan around the goals of your business.

Why does this matter? Because your best employees are usually the most recruitable. Competitors know their value. Recruiters know their names. And if one of them leaves, the cost may extend far beyond replacing a salary. You may also lose institutional knowledge, client relationships, revenue, culture, and momentum.

Here are seven practical strategies to help you retain key employees and restore alignment between your people and your business.

1. Identify Which Employees Are Truly Essential


Retention begins with clarity.

Not every employee needs an executive benefits plan. Not every high performer is a mission-critical employee. Your first step is to identify the people whose departure would materially affect your company’s value, growth, succession, or client relationships.

Ask yourself:

  • Who drives a significant portion of revenue?

  • Who owns important client or vendor relationships?

  • Who possesses knowledge that would be difficult to replace?

  • Who is being prepared for a future leadership or ownership role?

  • Who would be expensive or disruptive to replace?

  • Who could leave and create a succession problem?


This is where a business owner must look beyond job titles. A key employee may be a senior executive, technical specialist, physician, partner, producer, or operating leader.

Once you know who matters most, you can focus resources where they will have the greatest effect. A targeted plan is often more effective: and more cost-efficient: than adding generic benefits for everyone.

Our Executive Benefits Guide for Business Owners explains how selective benefits can be designed for owners, executives, and other key people who drive the company’s value.

2. Listen Before You Design the Benefit


Many retention efforts fail because the employer assumes it already knows what employees want.

You may believe your top executive wants a larger bonus. They may be more concerned about retirement income. You may think an equity grant is the answer. They may want family protection, liquidity, or a clearer path to future ownership.

The right question is not simply, “What can we afford to offer?”

The better question is, “What would make this person feel valued, protected, and invested in staying?”

Have direct conversations. Use stay interviews. Ask what your key employees value now and what they want their future to look like. Their priorities may include:

  • Supplemental retirement income

  • Life insurance for a spouse or family

  • Greater protection from income disruption

  • A meaningful connection to company growth

  • Additional compensation beyond qualified-plan limits

  • A path toward ownership or succession

  • More certainty about their long-term role


This conversation creates a foundation for a benefit that feels personal rather than manufactured. It also helps you avoid spending money on an arrangement that looks impressive on paper but does not change behavior.

3. Close the Retirement Income Gap


A standard 401(k) is important, but it may not be enough for your most highly compensated employees.

Contribution limits, nondiscrimination rules, and the structure of qualified plans can create a significant gap between an executive’s current income and the income they may need in retirement. That gap can become a source of frustration: especially when the executive is contributing aggressively but still cannot maintain their intended lifestyle.

A nonqualified deferred compensation plan, or NQDC plan, can help address that problem.

Depending on the design, an NQDC arrangement may allow a select group of executives to defer compensation beyond qualified-plan limits. It can also include vesting schedules and distribution elections that support long-term retention.

Common approaches include:

  • Employee-funded NQDC: Allows executives to defer additional salary or bonus.

  • Employer-funded NQDC: Provides a discretionary benefit tied to service, performance, or retirement.

  • 401(k) Mirror Plan: Helps restore contribution opportunity for executives who have reached qualified-plan limits.

  • SERP: Provides a supplemental executive retirement benefit based on a defined formula or objective.


You can review the broader structure in this complete guide to deferred compensation and NQDC plans. For employer-funded arrangements, see our overview of Employer-Funded NQDC Plans, as well as the dedicated guide to a 401(k) Mirror Plan.

These plans must be designed carefully. Section 409A compliance is essential. Improper elections or distribution provisions can create accelerated taxation, penalties, and unnecessary risk for the executive.

This is one reason technical expertise matters.

Matt Schiff helped draft the laws governing these arrangements from 2003 to 2005 as a ranking member of the AALU’s NQDC Committee, alongside Michael Goldstein. He was in the room where the rules were being shaped: not simply reading them after the fact.

You can also hear Matt discuss these issues with Dan Hogans, formerly of IRS Treasury, through The Perfect Plan® Podcast and official YouTube channel.

4. Create an Ownership Feel Without Giving Away Control


People often work harder when they feel connected to the outcome.

That does not mean every business should issue actual equity. Ownership can create dilution, governance complications, valuation questions, and future disagreements. For many business owners, the goal is to create the economic feeling of ownership while preserving control.

That is where phantom stock may be appropriate.

A phantom stock plan can provide a future cash benefit based on the value or performance of the company. The executive does not receive actual shares or voting rights, but the arrangement can help them participate in the value they help create.

This can be powerful for:

  • Privately held corporations

  • Partnerships

  • Professional practices

  • Family businesses

  • Companies preparing for a future sale

  • Businesses developing a future leadership team


The benefit is usually tied to specific conditions, such as continued service, performance, a change in control, retirement, or another defined event.

Read more about Phantom Stock and creating an ownership feel without giving away the farm.

5. Align Benefits With the Company’s Culture and Intent


A retention plan should feel consistent with the way your business operates.

If your culture values long-term service, the plan may use a vesting schedule. If your company emphasizes measurable performance, benefits may be connected to defined goals. If family protection is central to your values, life insurance and survivor benefits may be more important than a purely cash-based arrangement.

There is no universal best benefit. There is only the best structure for your goals, your employees, your entity type, and your culture.

Split Dollar and Restricted Executive Bonus Arrangements can sometimes help create a benefit that is personal to the executive while remaining structured for the business. These arrangements may address life insurance protection, future income, retention, and employer cost recovery: but they require careful coordination.

Our guide to The Perfect Plan®, Split Dollar, and REBA explains the broader concept.

The plan must also account for employer-owned life insurance rules, including IRC Section 101(j), when applicable. Notice, consent, documentation, and policy design should be addressed before implementation. Your attorney, accountant, TPA, and benefits advisor should work together from the beginning.

6. Give Key Employees a Future They Can See


A talented employee may leave because they cannot see what comes next.

Retention improves when a key employee understands how their role can develop over time. That future may include increased responsibility, participation in strategic decisions, leadership development, ownership transition, or a defined retirement benefit.

This is especially important when your company is approaching a transition. What happens if a senior executive retires? What happens if the person expected to replace them is not ready? What happens if a partner dies and the business is suddenly dealing with a surviving spouse?

A benefits strategy should connect to your broader succession plan. Our guide on how executive benefit needs evolve from startup to succession explores these questions.

You should also consider a Supplemental Executive Retirement Plan when the goal is to provide a defined future benefit for a senior leader.

The message is clear: “We see your future here, and we are willing to invest in it.”
Senior business executive considering long-term retirement and key employee retention planning with professional guidance

7. Review the Plan Before Circumstances Force You To


Retention plans should not be created once and forgotten.

Your business changes. Your employees change. Tax laws change. Ownership goals change. The person who was once your second-in-command may become your successor. A high performer may become a partner. A company may move from growth mode into acquisition or succession planning.

Review your arrangements regularly with your advisory team. Look at:

  • Whether the key employee’s role has changed

  • Whether the benefit still matches the employee’s priorities

  • Whether vesting and distribution terms remain appropriate

  • Whether the company can recover or fund the intended cost

  • Whether the arrangement continues to support succession

  • Whether compliance requirements are being met

  • Whether the plan reflects current business value


For corporate entities, Corporate Owned Life Insurance may be considered as part of a broader funding and cost-recovery strategy. It should never be treated as a substitute for thoughtful plan design, proper documentation, or professional advice.

Executive leadership team discussing long-term retention strategy and coordinated employee benefits in a modern office

The best retention strategy is not a single product. It is a coordinated system.

The Best Retention Strategy Starts With Your Goals


So, what is the best way to retain key employees?

Start by identifying the people who are essential to your future. Listen to what they value. Build a visible path forward. Then coordinate compensation, retirement income, ownership feel, family protection, and succession planning into a structure that works for both the executive and the business.

That is the essence of The Perfect Plan®: reverse-engineer the solution from the outcome you want.

Your goal may be to keep a top executive, prepare a successor, protect a family, fund retirement, or preserve the value you have spent decades building. The right plan can help you address more than one of those goals at the same time.

The five questions are worth asking now:

  1. What if I end up in business with a widow?

  2. What if I need a business buy-out?

  3. What if my top talent leaves?

  4. What if a senior executive retires and replacement costs are much higher?

  5. What if I run out of retirement money?


Sit back, grab your coffee, and take an honest look at what keeps you up at night. Then, when you are ready, begin with a business valuation and planning assessment through RISR or schedule an initial conversation with Matt Schiff.


Meta description: What is the best way to retain key employees? Learn seven practical strategies using executive benefits, NQDC plans, and long-term incentives.

Focus keyphrase: What is the best way to retain key employees through coordinated executive benefits and long-term retention strategies?
Business owner and executives comparing phantom stock, stock options, and equity options in a boardroom meeting

Choosing between phantom stock, stock options, SARs, and real equity is one of the most consequential retention decisions a closely held business owner makes. (Photo: Pexels)

Every business owner I sit down with eventually asks some version of the same question: "How do I make my best people think like owners without actually making them owners?"

That question has more than one answer. And most of the confusion I see in the market comes from owners who have heard four different terms — stock options, restricted stock, SARs, phantom stock — used almost interchangeably by four different advisors. They are not the same thing. They do not carry the same risks. And picking the wrong one is expensive to unwind.

So let's put them side by side.

Start with the real question


Before comparing instruments, get clear on what you are actually trying to solve. In my experience it is almost always one of three things:

  1. Retention. You have one to three people whose departure would genuinely hurt, and you want a reason for them to stay.

  2. Alignment. You want their financial outcome tied to enterprise value, not to this year's revenue number.

  3. Succession. You are building toward an exit and you need a management team that survives the transaction.


The instrument you choose should follow from the answer. If you're not sure which of these is driving you, my pillar piece on creating an ownership feel without giving away the farm walks through that diagnostic in more depth.

The four main options


Real equity (restricted stock or direct grants)


The executive becomes an actual shareholder. They get a certificate, a seat at the cap table, and, depending on your governance documents, voting rights. Could be done through Restricted Stock Units.  For more information on RSU's: Click Here

Upside: Nothing signals commitment like the real thing. It's also the cleanest story to tell a recruit.

Downside: Dilution is permanent. You inherit minority shareholder obligations, information rights, and fiduciary duties. Every strategic decision now has an audience. And if that person leaves — or divorces, or dies — you are living inside your buy-sell agreement, hoping you drafted it well.

Best fit: True partnership tracks in professional firms, or a co-founder who was always going to be a co-founder.

Stock options


The executive gets the right to buy shares later at today's price.

Upside: No cash outlay for the company at grant. Genuine upside participation.

Downside: In a closely held company, options are often a promise the executive can't cash. There's no market for the shares. Exercising means writing a check for stock they cannot sell. Meanwhile you still face eventual dilution, and you carry the valuation and administrative burden the whole time.

Best fit: Companies with a realistic liquidity path — a planned sale, a strategic buyer, or a market for the shares.

Stock appreciation rights (SARs)


A cash (or stock) payment equal to the growth in share value from grant to exercise. No purchase required.

Upside: Pure upside participation with no check to write and no cap table change.

Downside: SARs reward appreciation only. If your company is a stable, profitable, slow-growth enterprise, a SAR may pay very little even though the executive is doing exactly what you hired them to do.

Best fit: Growth-stage companies where enterprise value is the scoreboard.

Phantom stock


A contractual promise to pay cash in the future, tied to the value of a notional number of shares. No stock is issued. No dilution. No voting rights.

Upside: You keep 100% of control while the executive's economics move with yours. The plan is private — you are not publishing your cap table to your management team. Design is flexible: full value or appreciation only, vesting on time or performance, payment at a liquidity event or on a schedule.

Downside: It is a company liability, not a share of the company. That liability needs funding (more on that below), and the payout is ordinary income to the employee rather than capital gain.

Best fit: Closely held businesses where the owner is not ready — and may never be ready — to share the cap table. This is the category most of my clients land in, which is why I wrote the full phantom stock overview as a standing resource.

The comparison at a glance


Real equity Stock options SARs Phantom stock
Dilutes ownership Yes Yes, at exercise No No
Voting rights Usually At exercise No No
Employee cash required Sometimes Yes No No
Company cash required No No At payout At payout
Rewards total value Yes Appreciation only Appreciation only Your choice
Employee tax treatment Often capital gain Varies Ordinary income Ordinary income
Governed by IRC 409A Generally no Often exempt if structured properly Often, depending on design Yes
Reversible if it isn't working Difficult Difficult Moderate Easiest

That last row deserves more attention than it usually gets. Equity is close to permanent. A phantom plan is a contract you designed, and the next plan can be designed differently.

Two things owners underestimate


The funding problem. A phantom stock plan creates a future obligation. If the company doubles, so does what you owe. Owners who ignore this end up successful and cash-poor at the same time. Properly structured corporate owned life insurance can pre-fund the liability and, in many designs, deliver full cost recovery over the life of the plan.

IRC 409A. Phantom stock is deferred compensation, and the IRS treats it accordingly. Vague valuation methods, flexible payment timing, or informal amendments can trigger immediate taxation to the employee plus a 20% penalty — a spectacular way to turn a retention tool into a resentment tool. Our 2026 guide to 409A compliance covers what the rules actually require.

How to choose


Ask three questions, in order:

  1. Am I willing to have this person as a legal co-owner ten years from now? If no, you are choosing among SARs and phantom stock, and the conversation gets much simpler.

  2. Do I want to reward total company value, or only the growth from here? Full-value phantom units reward the former. SARs and appreciation-only phantom units reward the latter.

  3. How will I pay for it? If you don't have an answer, you don't have a plan yet — you have an intention.


Most closely held business owners who work through those three questions honestly arrive in the same place. They want the alignment without the entanglement. That is precisely what phantom stock was built to do, and it's the core of what we call The Perfect Plan®.

Ready to compare these against your actual numbers?


phantom stock vs stock options

A side-by-side chart is useful. A design built around your valuation, your key people, and your exit timeline is better. If you'd like to see how each of these would look inside your business, schedule a conversation — bring your coffee and your questions.


Matt Schiff is the President of Schiff Executive Benefits and the host of The Perfect Plan® Podcast. He specializes in helping business owners navigate the complex world of executive retention and benefit security.

Related Resources


The greatest asset of any successful business doesn't appear on the balance sheet; it walks out the door every evening at 5:00 PM. As a business owner, you’ve likely felt that late-night anxiety: What happens if your top executive : the one who keeps the wheels turning and the culture thriving : is recruited by a competitor? Or worse, what happens if they simply feel they’ve hit a ceiling and decide to move on because their current retirement plan is "capped out"?

In the world of executive retention, standard benefits are rarely enough. If you want to keep your best people happy and aligned with your long-term vision, you need something more sophisticated. You need NQDC Executive Benefits.

At Schiff Executive Benefits, we specialize in reverse-engineering these solutions. We don't just sell products; we design structures that protect your business while providing life-changing security for your key talent.

What Are NQDC Executive Benefits?


Nonqualified Deferred Compensation (NQDC) plans are specialized arrangements that allow employers to provide benefits to a select group of management or highly compensated employees. Unlike traditional 401(k) plans, which are "qualified" under ERISA rules and subject to strict contribution limits, NQDC plans are "nonqualified." This means they are exempt from many of those restrictive caps, allowing for much larger deferrals and more flexible design.

Essentially, NQDC executive benefits are a promise: the company agrees to pay the executive a certain amount of money at a future date (usually retirement, disability, or death) in exchange for their service today. Because these plans are discretionary, you can choose exactly who participates. You don't have to offer them to everyone : just the "Top Hat" group that truly drives your bottom line.

How NQDC Executive Benefits Work for Business Owners


For the business owner, an NQDC plan is a powerful tool for restoring alignment and retention. It allows you to create a "golden handcuff" effect that keeps executives focused on the company’s long-term growth.

The mechanics are straightforward:

  1. The company and the executive enter into a legal agreement.

  2. The executive (or the employer) contributes a portion of compensation into a deferred account.

  3. These funds grow tax-deferred until they are distributed.

  4. The company typically uses a funding vehicle, like Corporate-Owned Life Insurance (COLI), to ensure the cash is there when it’s time to pay out.


This structure allows you to answer the critical "What If" questions that keep owners awake. What if your top talent leaves? What if a senior executive retires and the replacement cost is prohibitive? By having an NQDC plan in place, you’ve already pre-funded those liabilities while creating a massive incentive for the executive to stay.

The Difference Between Qualified and Nonqualified Plans


If you’ve ever felt frustrated by 401(k) testing or the $24,500 (plus catch-up) contribution limits for your high earners, you already understand the limitation of qualified plans.

Qualified plans (401(k), Profit Sharing, etc.) must be non-discriminatory. You have to offer them to everyone, and the government limits how much your top earners can put away. For an executive making $300,000 or $500,000, a standard 401(k) barely moves the needle for their retirement lifestyle.

NQDC executive benefits, however, are discriminatory by design. You can:

  • Select specific individuals for the plan.

  • Allow for much higher contribution amounts (often up to 100% of bonus or a large % of salary).

  • Set custom vesting schedules that align with your business goals.


Why NQDC Executive Benefits Are Essential for Retaining Key Talent


In a competitive market, salary is just the entry fee. True retention comes from building a bridge between the executive's personal success and the company's long-term health.

Custom Vesting Schedules and Golden Handcuffs


One of the most powerful features of NQDC executive benefits is the ability to use "golden handcuffs." Through employer-funded NQDC plans, you can contribute additional compensation that only vests over a long period : say, 5 or 10 years : or upon reaching a specific age.

If the executive leaves early, they leave the money on the table. This provides a tangible reason for them to ignore the siren song of a competitor. It’s not about holding them hostage; it’s about rewarding their loyalty with a benefit they simply cannot get anywhere else.

Types of NQDC Executive Benefit Plans


Not all plans are created equal. Depending on your goals : whether you want to provide "ownership feel" or simply a retirement bridge : we select from several different structures.

[INLINE] Two business owners reviewing NQDC executive benefits and deferred compensation plan documents in a modern office meeting.

Employer-Funded NQDC Plans


Also known as discretionary plans, these are funded entirely by the company. This is a powerful "bonus" tool. Instead of giving a cash bonus that is taxed immediately at the highest brackets, you put that money into an NQDC account. It grows tax-deferred, and the executive only pays taxes when they receive the money in retirement.

Employee-Funded NQDC Plans (401(k) Mirror)


An Employee-Funded 401(k) Mirror Plan allows your executives to defer their own salary or bonuses beyond the 401(k) limits. This is purely a tax-planning tool for the executive, but it provides immense value by allowing them to save for retirement in a way that the government typically restricts.

SERP : Supplemental Executive Retirement Plans


A SERP is a "defined benefit" version of an NQDC plan. It promises a specific monthly or annual payout at retirement. It’s essentially a private pension for your most critical leaders.

Phantom Stock Plans


Want to give your key people the "ownership feel" without actually diluting your equity or giving them voting rights? Phantom Stock tracks the value of your company. If the company value goes up, the executive’s account balance goes up. It aligns their daily decisions with the total value of the business.

Split Dollar Life Insurance


Split Dollar programs are a sophisticated way to provide life insurance and retirement income using a shared-cost or shared-benefit arrangement. It’s one of the most cost-effective ways for a corporation to provide 100% protection to an employee's family while recovering every dollar the company spent on the program.

REBA : Restricted Executive Benefit Arrangements


A REBA uses a restricted executive bonus structure to build a tax-free retirement bucket for the executive, while still maintaining corporate control over the asset until certain conditions are met.

How to Fund NQDC Executive Benefits


Designing the plan is only half the battle. The other half is ensuring the plan is funded so the company can meet its future obligations without creating a cash flow crisis.

Corporate-Owned Life Insurance (COLI) as a Funding Vehicle


COLI is the "gold standard" for funding NQDC executive benefits. The company owns a life insurance policy on the executive. The cash value grows tax-deferred, and the company can borrow against or withdraw from that cash value to pay the deferred compensation benefits.

Crucially, when the executive eventually passes away, the death benefit flows back to the company tax-free, allowing for "full cost recovery" of every dollar paid out in benefits plus the cost of the premiums.

The Perfect Plan® Funding Strategy


We utilize The Perfect Plan® methodology to ensure these programs are structured for maximum efficiency. Our goal is to achieve "Retirement Made Simple": a fixed dollar amount, a fixed period, and a fixed cash flow for the executive, with total cost recovery for the employer.

409A Compliance and NQDC Executive Benefits


If you are going to play in the world of NQDC, you must understand the rules. IRC Section 409A is the federal law that governs how these plans must be structured, documented, and operated. The penalties for a 409A violation are draconian: the executive is taxed immediately on all deferred amounts, plus a 20% penalty tax and premium interest.

This is where technical expertise matters. Matt Schiff, the President of Schiff Executive Benefits, has a unique authority here. Between 2003 and 2005, Matt served as a ranking member of the AALU's NQDC Committee. Alongside industry legend Michael Goldstein, Matt was "in the room where it happened," helping to draft the very regulatory frameworks that became IRC 409A and IRC 101(j).

We don't just read the law; we understand the intent behind it. You can hear more about this "insider" perspective in The Perfect Plan® Podcast interview with Dan Hogans, the former IRS/Treasury official who was the principal author of the 409A regulations.

Understanding what is a 409A plan and the cost of getting it wrong is vital for any business owner considering these benefits.

[INLINE] Diverse executive team collaborating on a 409A-compliant NQDC plan for key employee retention and retirement benefits.

Tax Advantages of NQDC Executive Benefits


The beauty of NQDC executive benefits lies in the tax arbitrage:

  1. For the Executive: They defer income during their highest-earning years and take distributions in retirement, potentially in a lower tax bracket, all while the money grows tax-deferred.

  2. For the Employer: While the company doesn't get a tax deduction until the money is actually paid to the executive, the use of COLI allows the company to grow the funding assets tax-efficiently and eventually recover the costs through tax-free death benefits.


Is an NQDC Executive Benefit Plan Right for Your Business?


Every business is different, but the core questions remain the same. Are you prepared for the "What Ifs"?

  • What if your business ends up with a widow as a partner?

  • What if you need a buy-out strategy for a departing key executive?

  • What if your top talent leaves for a 15% raise because you didn't have "golden handcuffs" in place?


If you are an established business owner with a team of high-performing executives, NQDC executive benefits are not a luxury: they are a strategic necessity. They allow you to reward the people who built your dream while protecting the future of the company you’ve worked so hard to create.

At Schiff Executive Benefits, we help you realize your dream value by building it your way. We work alongside your existing team of advisors: your accountant, attorney, and TPA: to ensure the plan is integrated and compliant.

Are you ready to see what your business is worth and how you can better protect its future?

Sit back, grab your coffee, and let’s start the conversation. You can begin by getting a clear picture of your business valuation and identifying the gaps in your executive retention strategy.

Get Your Business Valuation & Executive Assessment Here

Ready to discuss how NQDC Executive Benefits can transform your retention strategy? Schedule a Teams Meeting with Matt Schiff Here.


The only constant in the world of high-stakes business is change, yet one truth remains universal: your business is only as strong as the people who lead it. For decades, the most successful organizations have understood that attracting and retaining top-tier talent isn't just about a competitive salary: it’s about creating a sense of ownership and securing a legacy.

But as you scale, the tools you use to build that security become increasingly complex. You move from simple "handshakes" to sophisticated financial structures. Among these, few are as powerful: or as misunderstood: as Split Dollar life insurance. When built correctly, it is a masterpiece of financial engineering. When built poorly, it can trigger a regulatory nightmare.

At Schiff Executive Benefits, we specialize in reverse-engineering these solutions to ensure they match your company culture and intent while "Restoring Alignment and Retention." To navigate this landscape, you need to understand the "architecture" of the plan: the interaction between tax regimes, the impact of the Sarbanes-Oxley Act (SOX), and the technical nuances of Internal Revenue Code (IRC) Section 409A.

The Two Foundations: Collateral Assignment vs. Endorsement


Think of a Split Dollar arrangement as a partnership between an employer and a key executive to share the costs and benefits of a life insurance policy. However, the way you structure that partnership determines everything from who owns the policy to how the IRS views the transaction.

1. The Loan Regime (Collateral Assignment)


In a Collateral Assignment Split Dollar (CASD) arrangement, the executive owns the policy. The employer pays the premiums, but those payments are treated as a series of loans to the executive. To secure the repayment of these loans, the executive assigns the policy’s cash value or death benefit to the employer as collateral.

This is often the preferred route for private companies because it allows for a more efficient transfer of wealth. However, because it is technically a loan, it must follow the rules of IRC Section 7872, requiring a market-rate interest or the imputation of income to the executive.

2. The Economic Benefit Regime (Endorsement)


In an Endorsement Split Dollar arrangement, the employer owns the policy. The employer "endorses" a portion of the death benefit to the executive’s beneficiaries. Here, the executive is not receiving a loan; they are receiving a taxable "economic benefit" (the value of the current life insurance protection).

While this is simpler from a documentation standpoint, it is often less flexible for long-term retirement planning than the loan-regime approach.

Architectural shot of a modern glass and steel office building, symbolizing the structural integrity required in benefit design.

The SOX 402 Hurdle: A Warning for Public Companies


If you are a decision-maker at a public company (or a company planning to go public), the architecture of your Split Dollar plan faces a significant regulatory roadblock: Section 402 of the Sarbanes-Oxley Act.

Passed in the wake of major corporate scandals, SOX Section 402 made it unlawful for any public issuer to extend or maintain credit in the form of a "personal loan" to any director or executive officer. Because a Collateral Assignment Split Dollar plan is legally structured as a loan, it falls squarely into the crosshairs of this prohibition.

For the top five employees in a public company, the loan-regime approach is generally a "no-go." Implementing a CASD plan for these individuals could lead to severe legal and civil penalties. In these environments, we typically pivot toward Endorsement structures or other Non-Qualified Deferred Compensation (NQDC) models that avoid the "loan" definition entirely.

409A and the Strategic Loan: Planning for the "What If"


One of the most attractive features of a Split Dollar loan is the possibility of loan forgiveness. Imagine a scenario where, after 15 years of exceptional service, the company forgives the executive's debt, effectively turning the life insurance policy into a tax-efficient retirement windfall.

However, if you don't plan for this from the start, you are walking into a trap set by IRC Section 409A.

Section 409A governs nonqualified deferred compensation. If a company decides on a whim to forgive a Split Dollar loan at retirement, the IRS may view that forgiveness as a "deferral of compensation." If the arrangement wasn't drafted to comply with 409A from day one, the executive could face immediate income inclusion, a 20% penalty tax, and premium interest charges.

"In the Room Where It Happened"


This is where technical expertise becomes your greatest asset. Our President, Matt Schiff, doesn't just read these laws; he was "in the room" when they were being shaped. In 2003 and 2005, Matt served as a ranking member of the AALU’s NQDC Committee alongside Michael Goldstein. Together, they helped draft the very laws: IRC 409A and 101(j): that govern these plans today.

When we talk about "Split Dollar Architecture," we aren't just following a template. We are using the same deep technical insight that helped establish the regulatory framework.

An executive desk with professional documents and a high-end pen, reflecting the technical and regulatory precision required for 409A compliance.

The History of Deferred Compensation


To truly understand why these rules exist, it helps to look back at the history of the industry. We recently sat down with Dan Hogans, formerly of the IRS Treasury and one of the primary architects of the 409A regulations, to discuss how we got here.

You can watch that full conversation, "The History of Deferred Compensation," on The Perfect Plan® Podcast. It’s a masterclass in how regulatory shifts changed the way businesses protect their key people.

At Schiff Executive Benefits, we integrate these lessons into every Perfect Plan® we design. Whether it's ensuring 100% protection for employee families or creating a 100% income stream in retirement, the goal is always the same: security through precision.

Why "Reverse Engineering" Matters


Most brokers start with a product. They have a policy they want to sell, and they try to fit your company into it. We take the opposite approach. We reverse-engineer the solution based on your specific goals.

  • Are you a public company? We avoid the SOX 402 traps.

  • Are you a private firm looking for a "Golden Handshake"? We structure the CASD with 409A-compliant forgiveness triggers.

  • Are you worried about cost recovery? We design the Cost Recovery Engine to ensure the business eventually receives every dollar it put into the plan.


We work as an integrated part of your advisory team, collaborating with your accountants and attorneys to ensure that the plan we build today doesn't become a liability tomorrow.

Two professionals in a modern collaborative space, highlighting the integrated approach of working with existing advisors.

Realizing Your Dream Value


Your business is your legacy. The people who help you build it deserve a plan that is as robust and well-thought-out as the company itself.

Are you asking the right "What If" questions?

  1. What if your top talent leaves for a competitor tomorrow?

  2. What if a senior executive retires and the replacement cost exceeds your budget?

  3. What if you could provide "Ownership Feel" to non-owners without giving away equity?


The answers to these questions lie in the architecture of your benefits. By utilizing The Perfect Plan®, you aren't just buying insurance; you are implementing a strategic retention tool that scales with your success.

Come Join Us


Navigating SOX, 409A, and Split Dollar regimes can feel like walking through a minefield. But you don't have to do it alone. Sit back, grab your coffee, and let’s look at how we can reinforce your company's foundation.

Whether you are a small business with 10 employees or a large corporation with 10,000, the principles of retention and alignment remain the same.

Ready to see what your business is truly worth and how you can protect it?

Get your professional business valuation here using the RISR tool.

Let’s build something that lasts.

A premium, minimalist library representing the peace of mind and long-term legacy provided by a well-architected executive benefit plan.


Learn more: 409A compliance, design, and strategy and Split Dollar architecture for executive wealth.


The Short Answer


Corporate Owned Life Insurance (COLI) is life insurance a company buys on the lives of selected employees, where the company owns the policy, pays the premium, and is named beneficiary. Businesses use COLI as a tax-advantaged balance sheet asset to informally finance executive benefit obligations — deferred compensation, supplemental retirement promises, split dollar arrangements — with the goal of recovering the cost of those benefits over time. Cash value inside the policy generally grows tax-deferred, and death proceeds are generally received income-tax-free, provided the company satisfies the notice and consent requirements of IRC 101(j) before the policy is issued.


COLI is also called company owned life insurance or employer-owned life insurance. When the buyer is a bank, the same structure is called BOLI. When the buyer is an insurance carrier, it is called iCOLI. The mechanics are largely the same; the regulator and the accounting context differ.


What Is Corporate Owned Life Insurance?


At its core, COLI is employer-owned life insurance placed on eligible employees for a legitimate business purpose. The structure has four moving parts:


  • The company owns the policy. It holds every incident of ownership — the right to borrow, surrender, change the beneficiary, and direct any investment allocation.

  • The company pays the premium. Premiums are not deductible. This is a capital allocation decision, not an expense strategy.

  • The company is the beneficiary. Proceeds are payable to the business, though many designs share a portion with the insured's family as an added benefit.

  • The insured employee gives written notice and consent before issue. This is not a formality. Miss it and the tax treatment of the death benefit changes permanently.


The planning value is not in the insurance itself. It is in what the asset does inside the business. A properly designed COLI case takes capital that would otherwise sit in taxable short-term instruments and repositions it into a vehicle whose growth is tax-deferred, whose eventual proceeds are generally tax-free, and whose timing can be matched to a liability the company has already promised to pay.


How COLI Life Insurance Works as a Balance Sheet Asset


COLI should be evaluated as a long-term corporate asset, not as a current-year tax play. The policy's cash surrender value is carried as an asset on the company's books. Growth inside the contract is generally not currently taxable. For a business comparing alternatives, that can create a materially more efficient holding environment than fully taxable fixed income or short-term corporate cash.


The analysis that matters is a comparison, not an absolute. The question is never "is COLI a good asset?" It is "compared to the taxable alternative this company would otherwise hold for the same duration, what is the after-tax outcome?" That comparison depends on the company's marginal tax rate, its holding period, its liquidity needs, and its tolerance for an asset that is not marked to market daily.


What COLI Is Typically Used to Finance


The common thread is duration. Every one of these is a promise the company has made that comes due years from now. COLI is a way to hold an asset whose characteristics resemble the liability it is meant to support.[HERO] Abstract technical business dashboard with financial charts, data layers, and analytical visuals, emphasizing the balance sheet structure and quantitative role of COLI.


COLI vs. BOLI vs. iCOLI: Which Applies to You


The three acronyms describe the same fundamental structure under three different owners, and they are frequently confused.


  • COLI — Corporate Owned Life Insurance. Bought by an operating company, professional firm, or partnership. Governed by the general tax rules discussed on this page.

  • BOLIBank Owned Life Insurance. Same structure, bank buyer, plus a layer of banking regulation. Federal regulators expect banks to conduct a pre-purchase analysis and to observe concentration guidance relative to capital.

  • iCOLIInstitutional Corporate Owned Life Insurance. Bought by insurance carriers to optimize capital and surplus. Different accounting regime, different risk framework.


If you are trying to decide which structure fits your institution, our companion piece on choosing between BOLI and COLI covers the decision in detail.


IRC 101(j): The Rule That Makes or Breaks a COLI Case


This is the single most important technical rule in employer-owned life insurance, and it is where most damaged cases go wrong.


Before the Pension Protection Act of 2006, employer-owned death benefits were generally income-tax-free with few conditions. The Act added IRC 101(j), which reversed the default. For an employer-owned life insurance contract, death proceeds are now taxable income to the employer above the premiums paid unless the arrangement satisfies both a notice-and-consent requirement and one of several exceptions.


The Notice and Consent Requirement


Before the policy is issued, the employee must:


  1. Be notified in writing that the employer intends to insure their life, and be told the maximum face amount for which they could be insured at the time the contract is issued;

  2. Give written consent to being insured, and to the coverage continuing after the insured terminates employment; and

  3. Be informed in writing that the employer will be a beneficiary of any proceeds payable on the employee's death.


The timing word is before. Consent obtained after issue does not cure the defect, and there is no general retroactive fix. A signature missing from a file years ago can convert a tax-free death benefit into ordinary income at the worst possible moment.


The Exceptions


Assuming notice and consent were properly completed, proceeds remain generally income-tax-free if the insured falls into a qualifying category — broadly, an insured who was an employee within twelve months of death, or who at the time the contract was issued was a director, a highly compensated employee, or a highly compensated individual as those terms are defined in the Code. There is also an exception for proceeds paid to the insured's heirs or used to purchase an equity interest from them.


This is why COLI is not a rank-and-file product. The eligible insured class is narrow by design, and confirming eligibility at issue is part of the underwriting discipline, not an afterthought.


Annual Reporting: IRS Form 8925


An employer holding employer-owned life insurance contracts generally files Form 8925 with its annual tax return, reporting the number of employees insured, the total amount of insurance in force, and confirming that valid consent is on file for each insured. Companies that acquire businesses often inherit policies without inheriting the consent documentation. If you have grown through acquisition and hold policies you did not originate, that file review should happen now rather than at a claim.[HERO] Abstract analytical business interface with layered charts, financial metrics, and technical data visualization, reflecting the investigative and compliance-driven structure of COLI.


Accounting Treatment


Under U.S. GAAP, an investment in a life insurance contract is generally reported at the amount that could be realized under the contract as of the balance sheet date — in practice, cash surrender value, net of any applicable surrender charges the company would actually incur. Changes in that realizable amount flow through income. Death proceeds in excess of carrying value are recognized when the claim is realizable.


Two practical consequences follow. First, the reported asset in early policy years is the cash surrender value, not the premium paid, and in some designs those differ meaningfully at the outset. Second, your auditor will want to see the carrier's annual statement supporting the carrying value. Neither is a problem in a well-designed case, but both should be discussed with your CPA before the first premium is paid, not after the first audit.


Cost Recovery: The Mechanic That Justifies the Structure


Cost recovery is the reason most companies use COLI rather than simply accruing the liability and paying benefits from operating cash.


The sequence works like this:


  1. The company makes a benefit promise — a deferred compensation account, a SERP, a phantom stock award — that comes due in the future.

  2. Rather than leaving that liability unmatched, the company allocates capital to a COLI policy on the insured executive.

  3. Cash value accumulates on a tax-deferred basis over the working career.

  4. When benefits become payable, the company can access policy values, subject to policy terms, to help fund them. Benefit payments to the executive are generally deductible to the company when paid and taxable to the executive when received.

  5. At the insured's death, the carrier pays proceeds to the company. Subject to compliance with 101(j) and the transfer-for-value rules, those proceeds are generally income-tax-free and can substantially restore the capital the company committed.


That final step is what advisors mean by "cost recovery." It does not make the benefit free, and any projection of full recovery depends on assumptions — policy performance, mortality timing, tax rates, and the discipline of leaving the structure intact — that should be stress-tested rather than accepted. A design that only works at an illustrated rate is not a design. Ask to see it at guaranteed assumptions before you commit capital.


Where COLI Cases Go Wrong


In thirty years of reviewing existing programs, the same failures recur:


  • Missing or late 101(j) consent. The most common and the most expensive. Almost always discovered at claim.

  • Transfer-for-value exposure. Moving a policy between entities in a reorganization, or to a partner or shareholder, can taint the tax-free death benefit under IRC 101(a)(2) unless it lands in a recognized safe harbor.

  • Orphaned policies. The producer retired, nobody has reviewed performance in a decade, and the carrying assumptions no longer hold.

  • Asset and liability that don't match. The benefit promise was designed by one advisor and the funding by another, and the two were never reconciled.

  • Design that ignores 409A. The insurance can be perfect and the underlying deferred compensation plan can still fail. See our guide to 409A compliance.


If you already hold COLI or BOLI and have not had it independently reviewed, our piece on the seven most common portfolio mistakes is a reasonable place to start.


Designing COLI Around the Liability


A COLI case should be engineered around the obligation it is intended to support — never the reverse. That means identifying the liability, measuring when it comes due, selecting the appropriate insureds, and evaluating how policy performance interacts with the broader benefit design.


At Schiff Executive Benefits we start with the technical objective and reverse engineer the structure around the company's financial intent, its liability profile, and its compliance requirements. Whether the goal is to support deferred compensation, coordinate with a split dollar program, or finance a phantom stock payout, the financing has to match the promise. That methodology is the core of The Perfect Plan®.


The Technical Advantage


Compliance in this field is not a checkbox. It is the difference between a tax-free asset and a serious tax problem. In 2003 and 2005, our President, Matt Schiff, served as a ranking member of the AALU's NQDC Committee alongside Michael Goldstein, working on the industry response to the regulations that became IRC 409A and IRC 101(j). When we discuss COLI compliance, we are drawing on direct involvement in how these rules took shape.


You can hear more on the technical history in Matt's interview with Dan Hogans, formerly of the Treasury Department, on The Perfect Plan® Podcast.[HERO] Technical financial analytics scene with structured reports, chart overlays, and corporate data review visuals, reinforcing the cost recovery mechanics behind COLI.


Frequently Asked Questions About COLI


What is the difference between COLI and company owned life insurance?


Nothing. They are two names for the same structure. "Corporate owned life insurance" and "company owned life insurance" are used interchangeably, and the Code refers to it as employer-owned life insurance. Some advisors reserve "company owned" for non-corporate entities such as partnerships and LLCs, but the tax rules under IRC 101(j) apply to all of them.


Are COLI premiums tax deductible?


No. Premiums paid on a policy where the company is a direct or indirect beneficiary are not deductible under IRC 264. The tax advantage of COLI is on the accumulation and death benefit side, not the premium side. Any presentation that suggests otherwise should be a red flag.


Is the COLI death benefit tax-free?


Generally yes, but only if the arrangement satisfies IRC 101(j) — proper written notice and consent before issue, plus a qualifying insured — and does not run afoul of the transfer-for-value rules. If those conditions are not met, proceeds above the premiums paid are taxable as ordinary income to the company.


Can a company buy COLI on any employee?


Practically, no. The 101(j) exceptions effectively limit favorable treatment to directors, highly compensated employees and individuals as defined in the Code, and recent employees. Broad-based coverage of rank-and-file employees — the practice that drew scrutiny in the 1990s and prompted the 2006 legislation — is not how modern COLI is designed.


Does the employee need to consent to COLI?


Yes, in writing, before the policy is issued. The employee must be told the maximum face amount, must consent to coverage continuing after employment ends, and must be informed that the employer will be a beneficiary. Consent cannot be obtained retroactively.


What happens to a COLI policy when the insured leaves the company?


The company continues to own the policy and may keep it in force, which is precisely why the consent language must disclose that possibility up front. Whether keeping it makes sense is an economic question that depends on the policy's performance and the liability it was purchased to support.


How is COLI different from key person insurance?


Key person insurance is one use case for COLI. It covers the economic loss to the business when a critical individual dies. Most COLI programs go further, using the asset to informally finance an ongoing benefit obligation rather than only to indemnify a death.


What is the minimum size for a COLI program to make sense?


There is no statutory minimum, but the structure has fixed administrative and compliance costs. The question to ask is whether the company has a real, durable benefit obligation and capital it can commit for the long term. A company with neither is better served by simpler tools.


Who regulates COLI?


COLI is governed primarily by the Internal Revenue Code — 101(j), 264, 7702, and 409A where a deferred compensation plan is involved — along with state insurance law. Banks buying BOLI face an additional layer of federal banking supervision that does not apply to ordinary corporate buyers.


The Next Step


If you are evaluating COLI, the right starting point is a technical review of four things: the objective, the insured class, the liability design, and the compliance process. The structure has to fit the business purpose, the accounting posture, and the long-term benefit obligation — in that order.


If you already hold policies, the starting point is different: a file review to confirm that 101(j) consent exists for every insured and that the carrying assumptions still hold.


To begin, use our RISR business valuation tool for an instant baseline, or schedule a conversation to talk through whether COLI belongs on your balance sheet.


Related Resources


External References


Designing COLI Around the Liability


A COLI case should be engineered around the obligation it is intended to support. That means identifying the liability, measuring the timing of the obligation, selecting appropriate insureds, and evaluating how policy performance interacts with the employer's broader benefit design. At Schiff Executive Benefits, that planning process starts with the technical objective. We reverse engineer the structure around the company's financial intent, the liability profile, and the compliance requirements. Whether the objective is to support deferred compensation or coordinate with Split Dollar Programs, the financing should match the promise. This methodology is central to The Perfect Plan®.


The Technical "Insider" Advantage


When it comes to executive benefits, compliance isn't just a checkbox, it's the difference between a tax-free asset and a major IRS headache. This is where our expertise is unmatched. Our President, Matt Schiff, didn't just study the laws; he helped write them. In 2003 and 2005, Matt served as a ranking member of the AALU's NQDC Committee alongside Michael Goldstein. Together, they worked in the "room where it happened," helping to draft the very regulations that govern IRC 409A and IRC 101(j) today. When we talk about COLI compliance, we are coming from a place of deep technical authority. We understand the nuances of IRS Form 8925 and the strict notice-and-consent requirements that must be met before a policy is issued. If you miss a single signature under IRC 101(j), your tax-free death benefit could suddenly become taxable income. Can you afford that risk? You can hear more about these technical "deep dives" and the history of these regulations by listening to Matt's interview with Dan Hogans (formerly of the IRS Treasury) on The Perfect Plan® Podcast.[HERO] Close-up technical business visualization with financial graphs, reporting layers, and strategic data analysis elements, underscoring the quantitative planning behind COLI. 


It is a universal truth in business that your company is only as strong as the people who keep the lights on and the wheels turning when you aren’t in the room. You’ve spent years: perhaps decades: building a culture, a brand, and a client list. But the real engine of that growth is your key talent. They are the architects of your strategy and the executors of your vision. So, here is the question that keeps many owners up at night: What if your top talent leaves? This isn't just a hypothetical scenario; it’s one of the core "What Ifs" we help business owners navigate every day. When a key executive walks out the door, they don't just take their laptop; they take institutional knowledge, client relationships, and a piece of your company’s momentum. Traditional retention tools like the 401(k) are great for the "rank and file," but for your high-earning leaders, they are often insufficient. The contribution caps are too low, and the "security" they provide isn't enough to stop a competitor from dangling a larger paycheck in front of them. You need something stronger. You need "Golden Handcuffs." But here’s the twist: you need the kind of handcuffs your executives actually want to wear. Enter the Restricted Executive Bonus Arrangement, or REBA.


What is a REBA? (Restoring Alignment and Retention)


At its simplest level, a REBA (also known as a Restricted Executive Bonus Plan or REBP) is a way for a company to provide a select group of key employees with a powerful, life-insurance-based benefit. Unlike a standard bonus that gets spent on a new car or a summer vacation, a REBA is designed for long-term security. The employer pays the premiums on a permanent life insurance policy that is owned by the employee. Because the employee owns the policy, they have a sense of security and "ownership feel" that a traditional deferred compensation plan can’t always match. However, since the company is footing the bill, they want to ensure that the "bonus" serves its purpose: keeping the executive at the desk. This is where the "Restricted" part of the name comes in. Through a Restrictive Endorsement, the employer limits the employee’s access to the policy’s cash value for a specific period of years. A high-end, sophisticated executive boardroom symbolizing stability and corporate success


The Mechanics: How the "Handcuffs" Actually Work


The beauty of the REBA lies in its simplicity and its technical elegance. It operates under IRC Section 162, which is the same tax code that allows businesses to deduct ordinary and necessary business expenses: like salaries and bonuses. Here is the step-by-step breakdown of how we design The Perfect Plan® using a REBA:


  1. The Policy: The employer selects a permanent life insurance policy (often a Corporate Owned Life Insurance or COLI product designed for high-cash-value growth). The employee is the owner and the insured.

  2. The Bonus: The company pays the annual premium directly to the insurance carrier. The IRS treats this payment as a bonus to the employee.

  3. The Tax Treatment: The premium payment is 100% tax-deductible for the employer as a compensation expense. On the flip side, however, the employee reports it as taxable income. (Many companies choose to "gross up" the bonus to cover the tax liability for the employee, making it a "zero-cost" benefit to them).

  4. The Restrictive Endorsement: This is the legal "handcuff." The employer and employee sign an agreement and then file it with the insurance company. It prevents the employee from borrowing against or withdrawing the cash value of the policy without the employer’s written consent for a set number of years (e.g., 10 years or until retirement).


If the executive leaves early? They take the policy with them, but they still can't touch that cash value until the restriction period expires. If they stay? They eventually gain full control over a significant pool of tax-advantaged capital.


Why Executives Actually Want This


Usually, when people hear the term "Golden Handcuffs," they think of something restrictive or punitive. But a REBA is a different beast entirely. It provides three things that every high-level executive craves: Security, Tax Efficiency, and Portability.


1. 100% Protection for Families


One of the "What Ifs" we often discuss is the "Business with a widow" scenario. If something happens to a key executive, their family needs to be protected. Because the REBA is funded with life insurance, there is an immediate, tax-free death benefit that goes to the executive's family from day one. This provides a level of peace of mind that a 401(k) balance simply cannot match in the early years.


2. Retirement Made Simple


We focus on retirement plans that offer a fixed cash flow and a fixed rate of return. The cash value inside a properly structured REBA grows on a tax-deferred basis. When the executive reaches retirement, they can often access that cash value through tax-free loans and withdrawals, providing them with a supplemental "tax-free" income stream. As we like to say, it’s about ensuring they don’t "run out of retirement money."


3. Personal Ownership


In many deferred compensation (409A) plans, the money technically belongs to the company, so the company’s creditors can reach it. In a REBA, the employee is the owner. Even with the restrictive endorsement, the policy is theirs. Therefore, even if the company goes bankrupt or changes hands, the policy stays with the executive. That is a massive security feature for a top-tier leader. A professional collaborative scene between a senior owner and a key executive


The Employer’s Perspective: Why It’s a Win


For the business owner, the REBA is an incredibly flexible tool.


  • Discriminatory Benefits: Unlike a 401(k), you don't have to offer this to everyone. You can pick and choose exactly which key people you want to reward and retain.

  • Simple Administration: There are no "Top Hat" filings, no complex annual ERISA reporting, and no 409A valuation headaches. It’s a bonus plan with an endorsement.

  • Cost Recovery: Because the premiums are deductible, the net cost to the company is lower than many other types of benefits.

  • Succession Planning: A REBA can even be tied into a buy/sell agreement or a succession plan, ensuring that the next generation of leadership has the liquidity they need when it’s time for the founder to exit.


Implementing Life Insurance for Executives


As Sonny mentions in his recent video, "Implementing Life Insurance for Executives," the key to success isn't just buying a policy; it’s the design. You have to reverse engineer the solution based on the intent. Are you trying to provide a retirement supplement? Are you looking for pure retention? Or is this part of a larger estate planning strategy for a partner? At Schiff Executive Benefits, we don't start with the product. We start with the goal. We work alongside your existing team of advisors: your CPA, your attorney, your TPA: to ensure the REBA fits perfectly into your corporate structure. We want to help you realize your dream value while keeping your best people happy and aligned with your long-term mission. A high-end fountain pen on a professional document, signifying the technical precision of a REBA


Is REBA Part of Your Perfect Plan®?


Every business reaches a point where "standard" isn't enough. When you are looking at the "What Ifs" of your business: whether it's the cost of replacing a senior exec or the fear of a key player being poached: you need a strategy that creates true alignment. The REBA is more than just a bonus; it’s a commitment. It tells your key people: "We value you, we want you here for the long haul, and we are willing to invest in your family’s future to prove it." If you are ready to move beyond basic benefits and start building a retention strategy that actually works, we invite you to sit back, grab your coffee, and join us for a conversation. Let’s look at your numbers, your culture, and your goals to see if a Restricted Executive Bonus Arrangement is the right fit for your organization. Building The Perfect Plan® doesn't happen by accident. Instead, it happens by design. Restoring Alignment and Retention. To see more about how we structure these programs, you can browse our latest insights on our posts feed or dive into the technical side of COLI strategies here. A serene retirement scene representing the ultimate peace of mind provided by a well-designed plan


Learn more: See how this fits into the bigger picture in our guide to executive benefits for business owners.


Learn more: Learn how a Section 162 Bonus Plan complements golden-handcuff retention strategies.


They say that the only constant in life is change, but in the world of high-stakes banking and executive leadership, the only constant is the relentless need for top-tier talent. Without the right people in the right seats, even the most storied financial institutions are just buildings with impressive vaults.
We’ve all felt the shift. The landscape of executive benefits is evolving faster than a New Orleans jazz solo. Tax codes shift, regulatory scrutiny tightens, and the "Great Reshuffle" has turned the hunt for executive retention into a strategic arms race.

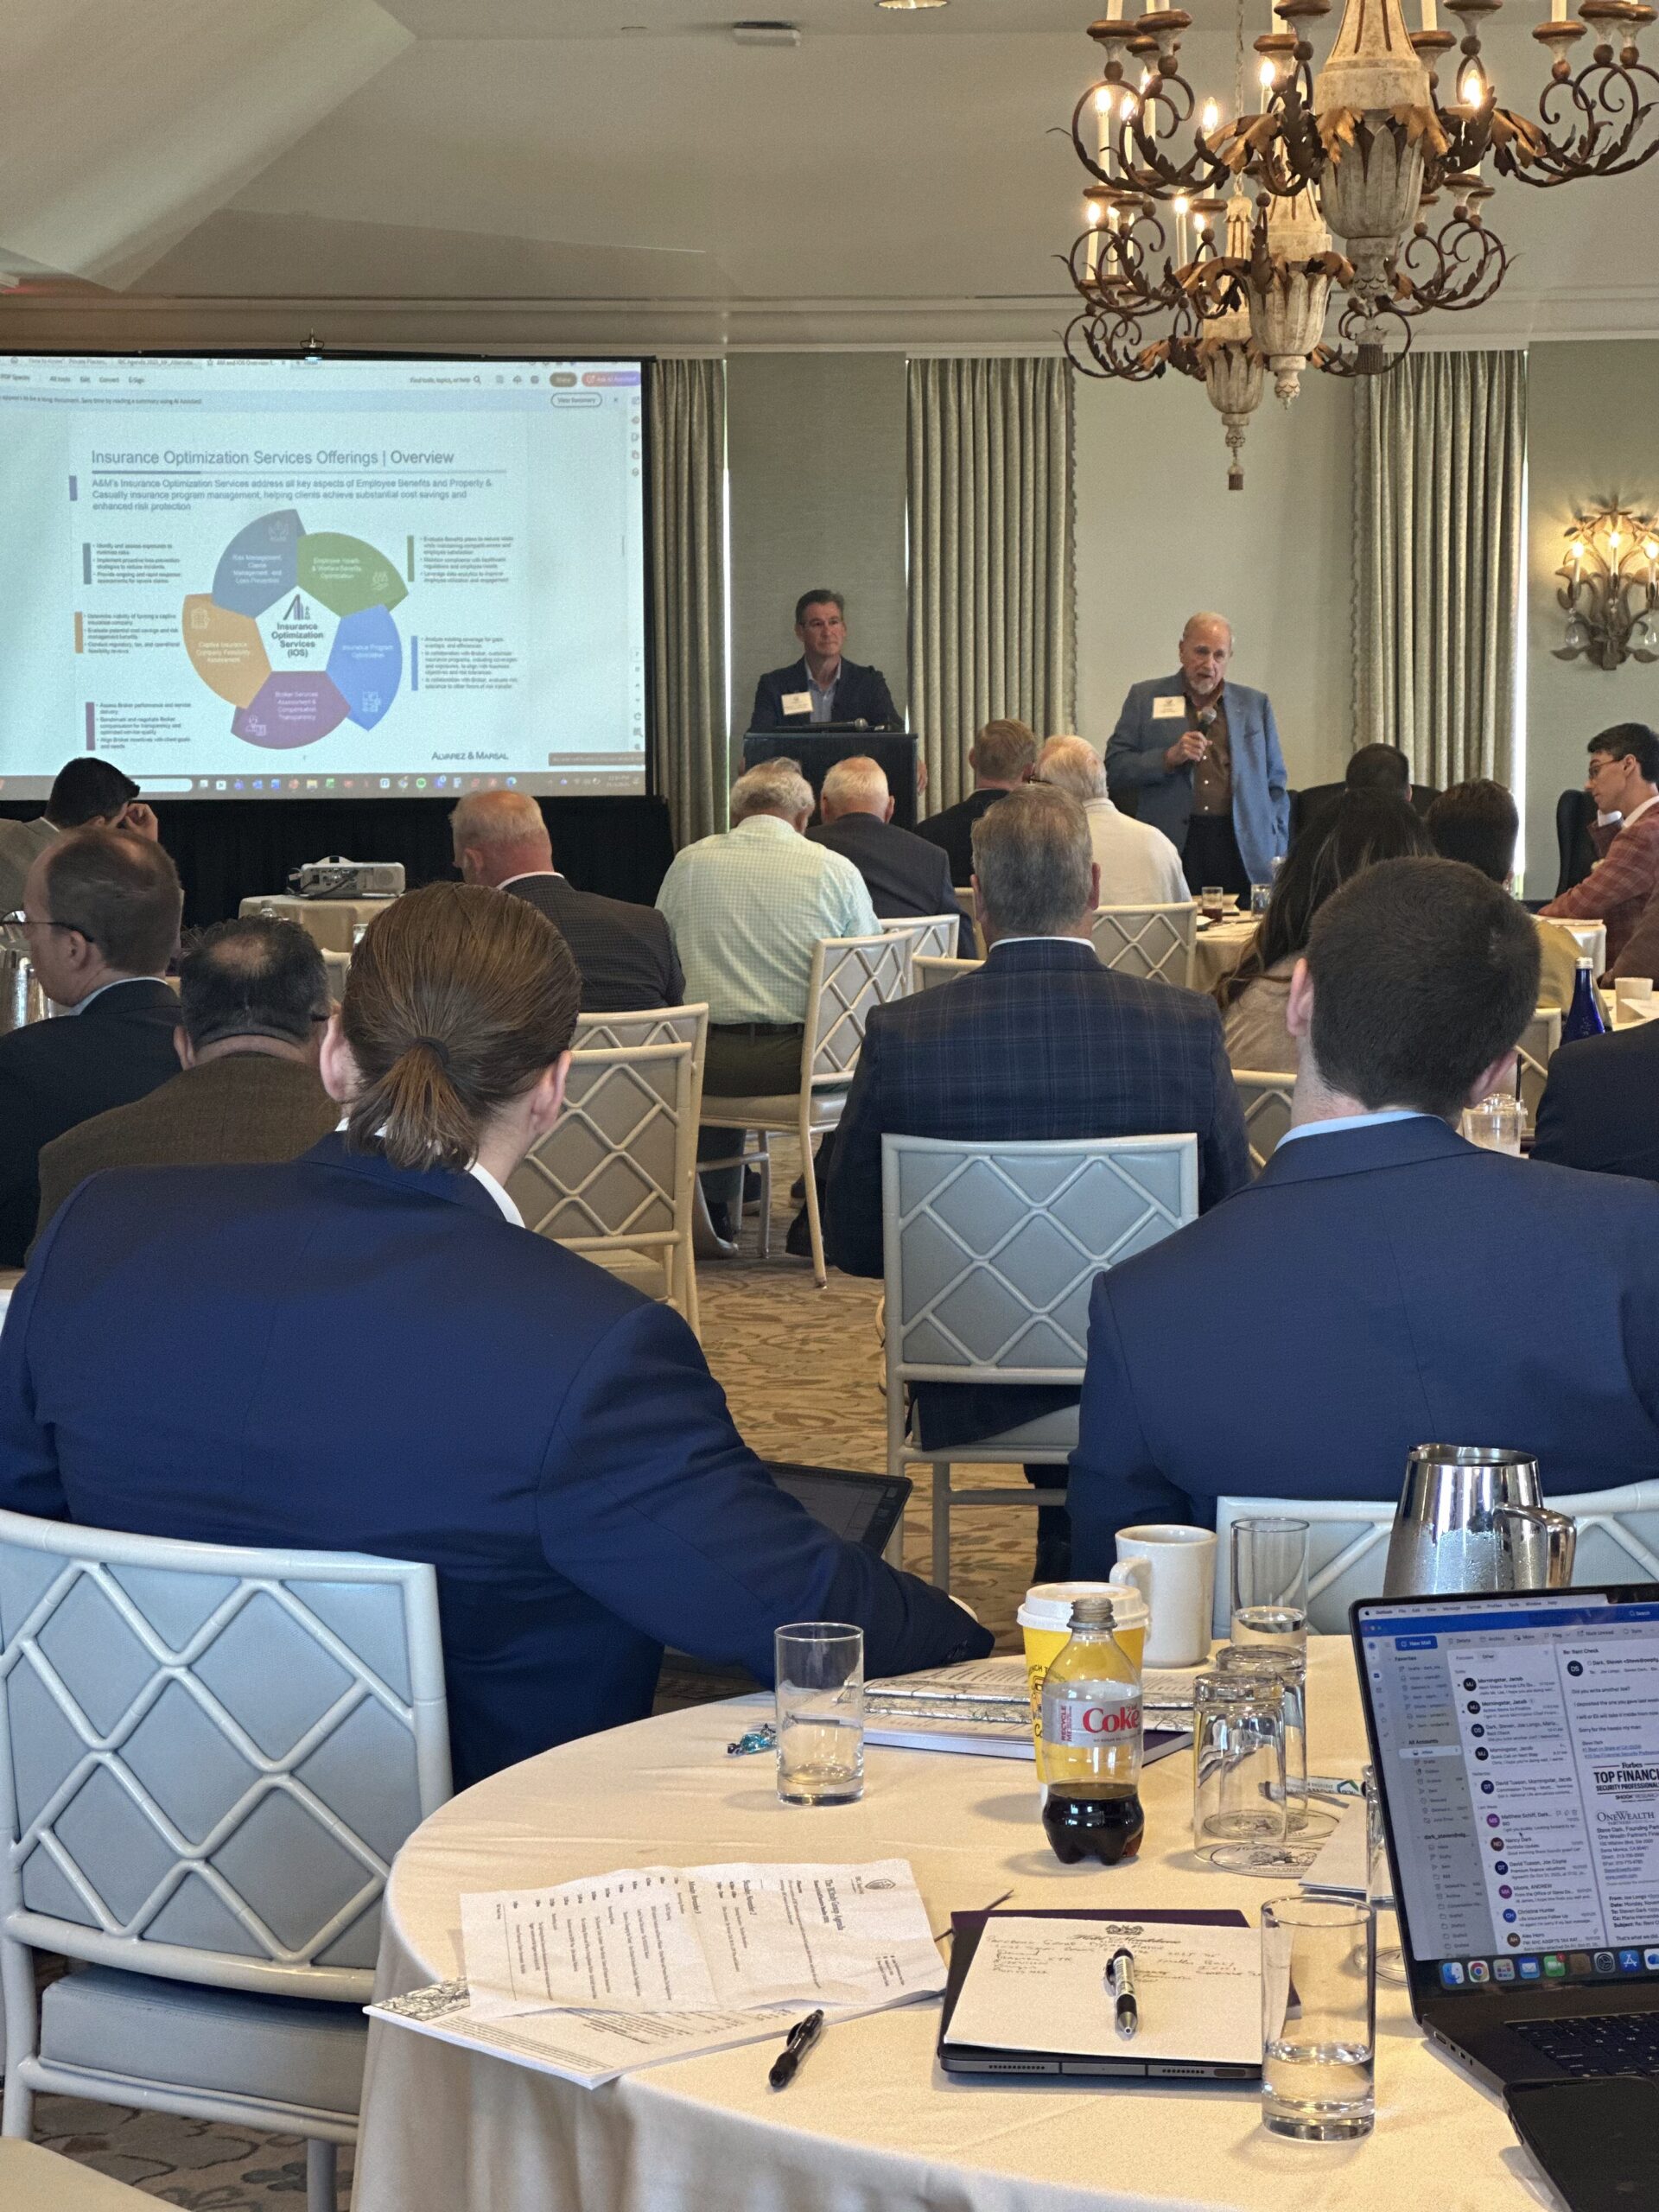
If you are an advisor to the banking industry’s elite, or a leader responsible for the long-term health of your institution, you know that standing still is the same as moving backward. That is why we are thrilled to announce that registration is officially live for the 2026 Independent Bank Corporate (IBC) Owned Life Insurance Study Group.

From November 1–3, 2026, we are returning to our spiritual home at the Hotel Monteleone in New Orleans. This isn't just another industry conference where you sit in a windowless ballroom and trade business cards over lukewarm coffee. This is an exclusive gathering designed for top-tier advisors who are serious about Restoring Alignment and Retention.

Why New Orleans? Why Now?


There is a reason we keep coming back to the French Quarter. Beyond the history and the atmosphere, New Orleans represents a blend of tradition and innovation: much like the strategies we discuss.

What keeps you up at night? For many of our attendees, it’s the "What Ifs" that haunt the boardroom.

  • What if your top talent leaves for a competitor tomorrow?

  • What if a senior executive retires and the replacement cost exceeds your projections?

  • What if a sudden tragedy leaves the business dealing with a widow or a complex succession crisis?


These aren't just hypothetical anxieties; they are the fault lines that can crack a bank’s foundation. At the 2026 IBC Study Group, we don’t just identify these problems; we build the solutions. We focus on the mechanics of Bank-Owned Life Insurance (BOLI) and Corporate-Owned Life Insurance (COLI) not as mere products, but as the engine for The Perfect Plan®.

The Technical Heart: BOLI and Beyond


While the surroundings are legendary, the core of this study group is deeply technical. We dive into the weeds of cost-recovery strategies and the nuances of Bank-Owned Life Insurance (BOLI).

In today’s volatile market, banks are looking for ways to offset the rising costs of employee benefits without taking on undue risk. BOLI remains one of the most effective tools for institutional capital management, offering tax-deferred growth and tax-free death benefits that can be used to fund non-qualified deferred compensation (NQDC) plans or supplemental executive retirement plans (SERPs).

Our sessions will cover:

  • Advanced Cost-Recovery Models: How to structure BOLI to ensure that the bank is made whole for the costs of executive benefits.

  • Executive Retention Strategies: Moving beyond standard bonuses to create "Golden Handcuffs" that actually work.

  • Regulatory Compliance: Navigating the latest updates to ensuring your plans remain "Gospel-compliant" with current tax and banking laws.

  • Succession Planning: Solving the "Business with a Widow" scenario through structured buy-sell arrangements and key-person coverage.


We understand that you are navigating an unstable financial environment. You need a guide who has been through the cycles. Our team at Schiff Executive Benefits acts as that guide, helping you realize your institution’s dream value while protecting your most valuable assets: your people.

Food, Fun, and Friendship: The Monday Night Highlight


We have always believed that the best business happens when the formal ties are loosened. The IBC Study Group has built a reputation on the "Three Fs": Food, Fun, and Friendship. This year, we are taking that to a new level.

On Monday night, we are hosting a Mardi Gras Theme Jazz Reception and Dinner in the brand-new Courtyard at the Hotel Monteleone. Imagine the sound of a brass band echoing off the brick walls, the scent of authentic Creole cuisine in the air, and the chance to network with the brightest minds in the industry in a setting that is uniquely New Orleans.

This isn't just a dinner; it’s an experience designed to foster the kind of deep professional relationships that last decades. It’s where the real "Study Group" happens: sharing stories of what worked, what didn't, and how we are all navigating the complexities of the modern financial world.

Is This Group Right for You?


The IBC Study Group is an exclusive circle. We intentionally keep the numbers focused to ensure that every participant can engage in the high-level dialogue that makes this meeting so valuable.

If you are an advisor who deals with:

  • Institutional BOLI portfolios.

  • Corporate-Owned Life Insurance (COLI) for non-bank entities.

  • Executive benefit plan design and 409A compliance.

  • ESOPs and partnership buy-outs.


...then you belong in the room. This is your opportunity to step away from the day-to-day grind and look at the big picture. Are you building a legacy, or just managing a spreadsheet? Are you offering your clients The Perfect Plan®, or just a standard off-the-shelf solution?

Secure Your Spot


The 2025 Study Group was a complete sell-out, and we expect 2026 to follow suit. The combination of the Monteleone’s charm, the technical depth of our sessions, and the new Monday night Jazz Reception makes this a "must-attend" event on the calendar.

Don't let the "What Ifs" stay unanswered.

  • What if you miss out on the specific tax-efficiency strategies that could save your client millions?

  • What if your competitors are in New Orleans while you’re at your desk?


Registration is now live for the meeting, and hotel reservations are now available through the Hotel Monteleone room block. Important: meeting registration does not cover your hotel booking. They are separate, and you will need to complete both.

Meeting Registration: Register for the 2026 IBC Study Group Here

Hotel Reservation Link: Book your room at Hotel Monteleone

Block Code: IBC30J

If you prefer to call in your reservation, contact 504-523-3341 or 800-535-9595 between 9:00 a.m. and 5:00 p.m. CDT and reference the block code IBC30J.

Sit back, grab your coffee, and mark your calendar. We are heading back to the Big Easy to restore alignment, ensure retention, and celebrate the profession we love.

We can't wait to see you in the Courtyard.


Schiff Executive Benefits is dedicated to helping businesses and banks navigate the complexities of executive retention and cost recovery. Through The Perfect Plan®, we provide the security and guarantees needed in an uncertain world.

For more information on our services or to view our latest insights, visit our posts feed.

An organization is only as strong as the people who lead it. It’s an undeniable truth in business: your "A-players" are the engine driving your growth, your culture, and your ultimate legacy. But here is the reality that keeps many business owners and CEOs up at night: those same A-players are being scouted every single day.

If you are relying solely on a standard benefits package to keep your top talent happy, you might be leaving the back door wide open. Traditional 401(k) plans and basic health insurance are great for the general workforce, but for your high-earners, they often fall short. They hit contribution ceilings too quickly, leaving your most valuable people with a significant "retirement gap."

At Schiff Executive Benefits, we believe in Restoring Alignment and Retention. We don’t just sell products; we reverse-engineer solutions based on the "What If" scenarios that actually matter to your business.

Sit back, grab your coffee, and let’s dive into Executive Benefits 101.

Why Standard Benefits Aren’t Enough for Executives


Let’s talk about the "Retirement Gap." If you have an executive making $300,000 or $500,000 a year, the standard IRS limits on 401(k) contributions (which sit at $23,000 in 2024, plus catch-ups) represent a tiny fraction of their income. While your entry-level employees might be able to replace 70-80% of their income through a 401(k) and Social Security, your top executives might only replace 30-40%.

That’s a problem. It creates a "reverse-discrimination" effect where your most productive people are the least protected.

When your leadership team feels their long-term financial security is at risk, they become susceptible to "the grass is greener" offers from competitors. This is where specialized executive benefits come in. These plans are designed to bypass the limitations of qualified plans, allowing you to recruit, reward, and: most importantly: retain the talent that makes your business move.

Executive leader in office reflecting on executive benefits and financial planning for talent retention.

The "What If" Framework: Solving for Uncertainty


Before we look at the specific tools like NQDC or Phantom Stock, we have to look at the risks. At Schiff Executive Benefits, we anchor every strategy in five core "What If" questions. These aren't just theoretical; they are the real-world events that can dismantle a company if you aren't prepared.

  1. What if your top talent leaves? The cost of replacing a C-suite executive can be 200% or more of their annual salary.

  2. What if you are forced to do business with a widow (or widower)? Without a proper succession and buy-sell arrangement, a partner’s passing can leave you running a company with their heir: who may know nothing about the business.

  3. What if you need a business buy-out? Do you have the liquidity to fund a transition without crippling operations?

  4. What if the cost of replacing a senior executive is too high? How do you fund the search and the "signing bonus" needed for a successor?

  5. What if you run out of retirement money? This applies to you and your executives alike.


By addressing these questions through The Perfect Plan®, we create a roadmap that provides security and clarity.

Executive Benefits Strategies: Your Complete Toolbox


There is no "one-size-fits-all" in executive compensation. A holistic strategy often involves a mix of several different structures, depending on whether you are a C-Corp, an S-Corp, a partnership, or a non-profit.

1. Non-Qualified Deferred Compensation (NQDC)


Think of an NQDC plan as a "401(k) on steroids." It allows executives to defer a much larger portion of their compensation (sometimes up to 100%) on a pre-tax basis. This helps them manage their current tax burden while building a substantial nest egg for the future. For the employer, these plans can be structured with "vesting schedules" (golden handcuffs) that ensure the executive stays for the long haul to receive the full benefit.

2. Phantom Stock Plans


For private companies that want to offer equity-like incentives without actually diluting ownership or giving away voting rights, Phantom Stock is the gold standard. It’s a contractual agreement that gives an executive the right to a cash payment at a future date, with the amount tied to the company's share price or overall value growth. It aligns the executive’s personal wealth directly with the company’s success. You can learn more about how we structure these rewards by visiting our services page.

3. Split-Dollar Life Insurance & COLI


Using Corporate Owned Life Insurance (COLI) is a powerful way to fund these promises. In a Split-Dollar arrangement, the company and the executive share the costs and benefits of a permanent life insurance policy.

  • The executive gets high-limit death benefit protection and potential tax-free supplemental retirement income.

  • The company can structure the plan for cost recovery, meaning the business is eventually reimbursed for the premiums it paid.


This is a sophisticated way to provide a massive benefit while keeping the long-term cost to the company near zero.

Representative Clients

The Power of Cost Recovery in Executive Benefits


One of the most frequent questions we get from CFOs is: "How do we pay for this without hurting our P&L?"

This is where the "reverse-engineering" comes in. By using strategies like COLI, we can design plans where the cash value growth and the ultimate death benefit of the insurance policies offset the cost of the executive’s retirement payments. In many cases, the company can actually recover every dollar spent on the benefit, plus a rate of return.

It turns a "compensation expense" into an "informally funded asset." That is the hallmark of The Perfect Plan®.

Building Your Team of Advisors


You wouldn’t perform surgery on yourself, and you shouldn’t design an executive benefit plan in a vacuum. These strategies require a "team of advisors" approach: coordinating with your tax professionals, legal counsel, and our team at Schiff Executive Benefits.

Whether you are navigating 409A compliance for deferred comp or setting up a buy-sell arrangement for a multi-partner firm, the details matter. The goal is to move from a state of "uncertainty" to a state of "guarantee."

Are you realizing your dream value, or are you just working for the next paycheck? Is your leadership team as committed to the next ten years as you are?

Transitioning to a Secure Future


Business environments are inherently unstable. Markets shift, tax laws change, and talent is mobile. However, your internal structure doesn't have to be. By implementing a robust executive benefits strategy, you are doing more than just paying people well: you are building a fortress around your most valuable assets.

We invite you to stop wondering "What If" and start planning for "When." Whether you are a growing corporation or a long-standing partnership, the time to secure your legacy is now, before you hit the "point of no return."

If you’re ready to see how these strategies can work for your specific situation, let’s have a conversation. No pressure, no hard sell: just a look at the math and the "What Ifs" that matter to you.

Come join us and discover how we can help you build it your way.

Schedule your consultation with Matt Schiff and the team today.


Schiff Executive Benefits provides specialized consulting for corporations, partnerships, and financial institutions. For more insights on executive planning and wealth preservation, listen to The Perfect Plan® Podcast.


At the end of the day, people don’t just work for a paycheck; they work for a future they can actually envision. It’s an undeniable truth in the world of executive leadership: if your top talent doesn't feel their long-term security is inextricably linked to your company’s success, they will eventually look for a door that offers a clearer view of the finish line.


You’ve likely implemented a Nonqualified Deferred Compensation (NQDC) plan with the best of intentions. You wanted to provide a "golden handcuff" to keep your key players in their seats. But what happens when those handcuffs feel more like a nuisance than a reward? Or worse, what happens when your competitors are offering a set of keys that look a lot more inviting?


At Schiff Executive Benefits, we often see companies that have the right tools but the wrong blueprints. We believe in reverse-engineering solutions to match your specific company culture, rather than forcing a generic plan into a unique environment. If your NQDC plan isn't doing the heavy lifting of retention, it’s time to look under the hood.


Here are 10 reasons your NQDC plan might be underperforming: and how we can work together to fix it.


1. The "Black Box" Problem: Lack of Education


If an executive doesn't understand the internal mechanics of their plan, they won't value it. We’ve sat down with brilliant CFOs and COOs who view their NQDC plan as a "black box": money goes in, something happens, and eventually, money comes out. Without a clear understanding of the tax-advantaged growth and the compounding power of the plan, it’s just numbers on a screen.


The Fix: Enhance participant education. This isn’t about a one-time HR meeting; it’s about ongoing, consultative engagement. We help participants see the "why" behind the plan, aligning it with their personal retirement goals.


executive-consultant-modern-office-microphone.webp


2. The Gold is Too Far Away: Rigid Vesting Schedules


Vesting is the heart of retention, but if the schedule is too aggressive or too distant, it loses its "pull." A 10-year cliff vesting schedule might seem like a great way to ensure long-term loyalty, but in today’s fast-paced market, it can feel like an impossible mountain to climb.


The Fix: Consider "rolling vesting" or milestone-based triggers. By rewarding longevity in digestible increments, you create a continuous incentive to stay for "just one more year," which eventually turns into a career.


3. The "Generic Trap": Lack of Customization


One of the biggest mistakes we see is a "one-size-fits-all" approach. Your VP of Sales has different financial anxieties than your Head of R&D. If the plan doesn't reflect the culture of your leadership team, it will never feel like a personal benefit.


The Fix: This is where we excel. We reverse-engineer your executive retention strategies to match your culture. Does your team value aggressive growth, or are they more concerned with downside protection? Build the plan around their needs, not the provider’s template.


4. Inflexible Distribution Options


Life happens. Children go to college, houses are bought, and tax laws change. If your NQDC plan only allows for a lump-sum payment at age 65, you are ignoring the reality of your executives' lives.


The Fix: Modernize your distribution schedules. Allow for scheduled in-service distributions for specific life events. When an executive can see their NQDC plan helping pay for their daughter’s Ivy League tuition, the plan becomes "real" and the loyalty becomes personal.


5. Security Concerns and the "Creditor" Fear


Because NQDC plans are technically "unfunded" and subject to the claims of the company’s general creditors, there is always a lingering whisper of doubt: Will the money actually be there when I need it? In an unstable economic environment, this anxiety can outweigh the potential tax benefits.


The Fix: Use sophisticated funding strategies. While the plan remains technically unfunded for tax purposes, informal funding through vehicles like Corporate-Owned Life Insurance (COLI) can provide the informal "reserve" that gives executives peace of mind. We often discuss these strategies on The Perfect Plan® Podcast.


financial-blueprint-analysis.webp


6. Poor Performance Benchmarking


Is your plan’s crediting rate competitive? If your participants feel they could get a better return by simply taking the cash, paying the taxes, and investing in a standard brokerage account, your retention tool has lost its edge.


The Fix: Regularly review and benchmark your plan against industry standards. Ensure the investment options or crediting rates are attractive enough to justify the deferral. You want your team to feel they have an "unfair advantage" by being part of your organization.


7. The Complexity of Section 409A


Nothing kills the "warmth" of a benefit plan like the cold hand of IRS penalties. Many executives are terrified of the complex rules surrounding Section 409A. If they feel the plan is a tax trap waiting to spring, they will stop contributing.


The Fix: Provide expert guidance and clear communication regarding compliance. At Schiff Executive Benefits, we act as the guide through these "unstable" environments, ensuring that both the company and the executive are protected and confident.


8. Missing the "Personal Legacy" Connection


Executives at the top of their game aren't just thinking about their next vacation; they are thinking about their legacy. Does your plan allow for meaningful beneficiary designations or coordinate with their estate plan?


The Fix: Integrate the NQDC plan into a broader conversation about wealth transfer and The Perfect Plan®. When the benefit extends to their family’s future, it’s no longer just a business arrangement; it’s a life-changing foundation.


cheerful-couple-marina-dock-yachts-sailboats-retirement.webp


9. Administrative Friction


If the portal is hard to use, the statements are confusing, or it’s a hassle to change a deferral election, the participant’s experience is tarnished. Executives have zero patience for administrative friction.


The Fix: Partner with providers who offer a high-touch, "white-glove" experience. The technology should be seamless, but the human support should be even better. We pride ourselves on being the team you can call when you need an answer right now.


10. The "Set It and Forget It" Mentality


The world changes. Your company grows. Tax brackets shift. If you haven't reviewed your NQDC plan in three years, it is likely obsolete. A static plan is a dying plan.


The Fix: Conduct annual reviews. We work with our clients to ensure their plans stay relevant to the current economic landscape and the evolving goals of their leadership team.


Business leaders collaborating on NQDC plan designs to boost executive retention in a warm, professional office setting.


Realizing Your Dream Value


I remember working with a CEO who was frustrated because his top three executives were all being recruited by a larger firm. He had a deferred comp plan in place, but when we looked at it, the executives didn't even know how much was in their accounts. They didn't feel the "weight" of what they would be leaving behind.


We sat down, reverse-engineered the plan to include more flexible distributions and a better crediting rate, and then we communicated it. We showed them how staying for five more years would change their lives: not just their bank accounts. They stayed. Not because they were trapped, but because they finally saw how the company was building their dream alongside them.


Your Next Step


Does your current plan feel like a burden or a benefit? Are you worried that your "golden handcuffs" are starting to rust?


What keeps you up at night regarding your leadership team? If it's the fear of losing the talent you’ve spent years cultivating, it’s time to take a breath and take a look at the blueprint.


Sit back, grab your coffee, and let's have a conversation. We’re here to help you navigate these uncertain waters and build something that lasts. You’ve built an incredible company; let’s make sure your team feels the same passion for its future that you do.


Come join us at Schiff Executive Benefits, where we don't just design plans: we build security and legacy.


Ready to see if your plan is performing?
Contact us today to schedule a warm, low-pressure review of your executive benefits strategy. We’d love to welcome you to the family.


Learn more: our complete guide to NQDC plans.