Hi, How Can We Help You?
  • Planning for all of life's "What Ifs".

Category Archives: Bank Owned Life Insurance

BOLI for banks, COLI for corporations ![[HERO] Bank and corporate executives collaborating on BOLI and COLI planning for employee benefits and executive retention.](https://images.pexels.com/photos/3183150/pexels-photo-3183150.jpeg)


In business, clarity beats complexity. The right tool in the right hands can solve the right problem. The wrong tool, even if it looks similar on paper, creates confusion fast.


If you are a bank leader, you do not need to wonder whether COLI belongs on your balance sheet. It does not. If you are running a corporation, LLC, or partnership, you do not need to sort through BOLI literature. It is not your vehicle.


At Schiff Executive Benefits, we spend our days answering these "What If's." What if top talent leaves? What if retirement costs are rising faster than expected? What if a buy-sell obligation shows up before you are financially ready? We do not start with a product. We reverse engineer solutions based on your goals, your entity type, and your regulatory environment.


That is why this conversation is not about competition between BOLI and COLI. It is about fit. Both use employer-owned life insurance mechanics. Both can support long-term executive benefit planning. But they belong in different worlds.


The Right Tool for the Right Job


The easiest way to frame this is simple.


If you are a bank, credit union, or thrift, you are in the BOLI world.
Bank-Owned Life Insurance is a specialized asset class for financial institutions. It is used to help informally fund employee benefits and generate tax-advantaged income on the institution's balance sheet. It is also heavily regulated by the OCC, FDIC, and state banking departments, which means design, due diligence, and administration matter. You can learn more about our specific BOLI consulting services here.


If you are a corporation, LLC, or partnership, you are in the COLI world.
Corporate-Owned Life Insurance is the broader planning tool for non-bank businesses. It is often used to support executive retention strategies, key-person coverage, buy-sell planning, and nonqualified deferred compensation (NQDC) plans. For companies evaluating deferred compensation design, it also pairs naturally with broader executive benefit planning.


The mechanics may be similar. The use cases may overlap at a high level. But the entity determines the vehicle.


Where COLI Fits in the Corporate World


For corporations, LLCs, and partnerships, COLI is often part of a much broader retention and succession strategy. Many business owners are asset rich and cash poor. Their value is tied up in the business. That works well until a buyout, retirement, death, or executive transition forces a liquidity event.


If you have a buy-sell agreement in place, how will it be funded? If a key executive retires, how will you replace that talent cost-efficiently? If your best people are being recruited, what are you doing today to make staying more valuable than leaving?


This is where COLI can shine. A properly structured plan can help fund obligations tied to executive retention, deferred compensation, key-person risk, and ownership transition. It can create what we call an Ownership Feel to Non-Owners while helping the business maintain control, liquidity, and long-term alignment.


For banks, those same broad concerns may exist. But the funding vehicle is BOLI, not COLI. That distinction matters.


The "In the Room" Expertise: IRC 101(j) and 409A


Rules matter. Entity type matters. Documentation matters. This is where a lot of well-meaning advisors get lost.


When we talk about BOLI and COLI, we are not reading from a brochure. Matt Schiff brings a deep technical legacy to this work. Back in 2003 and 2005, he was in the room where it happened. As a ranking member of the AALU's NQDC Committee, he worked alongside Michael Goldstein to help draft the very laws that govern these plans today: IRC 409A and IRC 101(j).


That matters because these rules do not disappear just because you picked the right entity-specific vehicle. IRC 101(j) and 409A apply to both BOLI and COLI where relevant. Whether you are a bank implementing BOLI or a corporation structuring COLI around deferred compensation, technical compliance is still the backbone of a successful outcome.


If you want to hear more about that era and the technical nuances of these regulations, I highly recommend listening to my podcast interview with Dan Hogans, who was formerly with the IRS Treasury and was a key architect of these rules.


The 101(j) Trap


One area where many generalist advisors trip up is IRC 101(j). This regulation governs employer-owned life insurance. To keep the death benefits of a BOLI or COLI policy income-tax-free, you must comply with strict notice and consent requirements before the policy is issued.


[IMAGE] Executive reviewing IRC 101(j) compliance documents for employer-owned life insurance planning.


If you fail to get the employee's written consent or fail to file the annual IRS Form 8925, the death proceeds that should help the business can suddenly become taxable income. We see this all too often in legacy plans that have never been audited. At Schiff Executive Benefits, we make sure your program is designed to comply from day one, Restoring Alignment and Retention to your organization.


The Perfect Plan® Starts with the Right Vehicle


In today’s competitive landscape, good enough benefits do not cut it. Your best people are being recruited every single day. To keep them, you need a strategy that fits your organization and speaks directly to the outcomes your leadership team cares about.


This is why we developed The Perfect Plan®. It is not just a product. It is a philosophy. The process starts by identifying the right vehicle for the right entity, then designing the plan around the outcome.


That means:


  • Banks may use BOLI to help fund employee benefits and create tax-advantaged balance sheet support.

  • Corporations, LLCs, and partnerships may use COLI to support Deferred Compensation (NQDC), executive retention, key-person coverage, and buy-sell planning.

  • Both require thoughtful design, regulatory awareness, and coordination with your broader advisory team.


Imagine telling your top executive: If you stay with us for the next ten years, we have a plan that provides 100% income when you need it most in retirement, and 100% protection for your family if something happens to you tomorrow.


That is the power of a properly structured plan. It aligns the executive’s personal financial goals with the company’s long-term health.


[IMAGE] Business professionals finalizing a deferred compensation and executive benefit planning agreement.


Why the "Reverse Engineering" Approach?


Most brokers start with a product. We do not work that way.


We work as a broker with any carrier, which allows us to stay agnostic. We start with your "What If's."


  • Are you a bank trying to offset benefit costs efficiently?

  • Are you a corporation preparing for a business buyout?

  • Are you concerned about the cost of replacing a senior executive?

  • Are you looking for 100% cost recovery for the employer?

  • Are you trying to keep your top talent from leaving?


Once we have the goal, we reverse engineer the solution. We work alongside your existing team of advisors: your Accountant, Attorney, and TPA: to ensure that the BOLI or COLI structure fits your legal, tax, and cultural framework.


Your Next Steps


Building a business is hard. Protecting it should not be. The first step is simple: identify your world.


If you are a bank, credit union, or thrift, your conversation starts with BOLI and the banking guidance that surrounds it. If you are a corporation, LLC, or partnership, your conversation starts with COLI and how it supports retention, buy-sell planning, and deferred compensation.


If you are ready to see how the right vehicle fits into your situation, I invite you to take a low-pressure first step. Use our Business Valuation tool to get a clearer picture of what you have built.


From there, we can sit down, grab a coffee, and talk through the practical next move. If you want to go deeper first, explore our Deferred Compensation and NQDC planning page, our COLI strategy overview, or our BOLI consulting page for banks.


To stay updated on the latest strategies for business owners and executives, visit our latest posts here or join the conversation over at The Perfect Plan® on YouTube.


[IMAGE] Modern city skyline symbolizing long-term employer-owned life insurance planning and executive benefit security.


Learn more: our complete guide to Bank Owned Life Insurance (BOLI) and Corporate Owned Life Insurance (COLI).


In the world of institutional finance, there is a fundamental truth we all must face: markets fluctuate, but the need for stability is constant. Whether you are managing the balance sheet of a community bank or overseeing the executive benefits for a Fortune 500 company, you are constantly looking for that "sweet spot": the intersection where growth meets protection.


For years, the choice was binary. You either accepted the low-yield, safe-haven environment of General Account products or you braced yourself for the white-knuckle volatility of Variable Life. But what if there was a third way? What if you could capture the upside of the equity markets without ever having to worry about a market crash eroding your principal?


This is the promise of Institutional Indexed Universal Life (IIUL).


At Schiff Executive Benefits, we specialize in reverse-engineering solutions that align with your company’s culture and long-term intent. We don’t just sell products; we help you plan for all of life’s "What If’s": including what happens when your top talent considers leaving or how to fund a senior executive’s retirement cost-effectively.


What is Institutional Indexed Universal Life (IIUL)?


Institutional Indexed Universal Life (IIUL) is a specialized, institutional-grade version of Indexed Universal Life (IUL). While retail IUL is a popular tool for individual estate planning, the "Institutional" prefix denotes a product designed for the scale, pricing, and transparency required by banks for Bank-Owned Life Insurance (BOLI) and corporations for Corporate-Owned Life Insurance (COLI).


At its core, IIUL is a permanent life insurance vehicle where the cash value growth is linked to the performance of an external equity index, such as the S&P 500, Nasdaq-100, or the EURO STOXX 50. However, unlike a direct investment in the stock market, you aren't actually in the market. You are simply using the index as a measuring stick for interest crediting.


The Power of the 0% Floor


The most compelling feature of IIUL is the 0% floor. This is the ultimate "sleep well at night" hedge. If the S&P 500 drops 20% in a year, your policy’s cash value doesn't drop a dime due to market performance. Your floor is zero. You stay flat while the rest of the market retreats.


A close-up of a financial professional pointing at a data chart on a tablet in a bright, modern corporate office, symbolizing the growth potential of Institutional Indexed Universal Life.


Of course, there is a trade-off for this protection. In exchange for the floor, the insurance carrier places a cap on your growth: typically ranging between 8% and 12%, depending on the carrier and the specific index.


This creates a "smoothed" growth curve. By cutting off the deep valleys of market crashes and slightly shaving the highest peaks, IIUL provides a steady, upward trajectory that is ideal for long-duration liabilities like Supplemental Executive Retirement Plans (SERPs) and Non-Qualified Deferred Compensation (NQDC) plans.


Why Institutions Choose IIUL for BOLI and COLI


Banks and corporations aren't just looking for a place to park cash; they are looking for a strategic asset that solves specific problems. When we look at the BOLI process or COLI strategies, IIUL often emerges as the preferred vehicle for several reasons:


  1. Attracting and Retaining Talent: The "Top Talent Leaving" scenario is one of our core "What Ifs." IIUL provides the informal funding necessary to offer an "Ownership Feel to Non-Owners" through programs like Phantom Stock or Restricted Executive Bonuses.

  2. Cost Recovery: One of the primary goals of any executive benefit plan is full cost recovery for the employer. The tax-free death benefit provided by IIUL allows a company to recoup the costs of the benefits paid out, plus the premiums and the time value of money.

  3. Balance Sheet Efficiency: For banks, BOLI is a highly efficient asset. Because the cash value grows tax-deferred (and can be accessed tax-free if structured correctly), the "Tax Equivalent Yield" of an IIUL policy often significantly outperforms traditional fixed-income investments.


The Tax Advantages: Accumulation and Distribution


In the realm of executive benefits, taxes are often the largest "leak" in the bucket. IIUL is designed to plug those leaks.


  • Tax-Deferred Accumulation: The cash value grows without being diminished by annual income taxes.

  • Tax-Free Death Benefit: Under IRC 101(j), as long as proper notice and consent requirements are met, the death benefit is received by the corporation or bank income tax-free.

  • Efficient Funding for NQDC: When used to informally fund a 401k Mirror or NQDC plan, the growth of the IIUL policy can be matched against the growing liability of the executive's account, creating a hedge that protects the company's P&L.


Two business professionals shaking hands in a high-rise office building, illustrating the collaborative approach Schiff Executive Benefits takes with clients and their advisors.


The "Insider" Advantage: Why Experience Matters


When you are implementing a program as technical as IIUL, you need more than a broker; you need a consultant who has been "in the room where it happened."


Our President, Matt Schiff, brings a level of expertise that is rare in this industry. In 2003 and 2005, Matt was a ranking member of the AALU's NQDC Committee. Alongside Michael Goldstein, he helped draft the very laws that govern these plans today: specifically IRC 409A and IRC 101(j).


We don't just read the regulations; we remember the intent behind them. This technical depth ensures that your plan isn't just "The Perfect Plan®" on paper, but a robust, compliant solution that stands the test of time. For a deeper dive into this history, I encourage you to listen to Matt’s conversation with Dan Hogans (formerly of the IRS Treasury) on The Perfect Plan® YouTube channel.


Leading Carriers in the IIUL Space


Because we operate as an independent consultant and broker, we have the ability to work with any carrier in the market. However, when it comes to the institutional-grade performance required for BOLI and COLI, a few names consistently rise to the top:


  • Pacific Life: Known for high-capacity underwriting and a long history in the COLI market, Pacific Life offers some of the most flexible IIUL designs available today.

  • Nationwide: A stalwart in the institutional space, Nationwide provides robust living benefit riders and streamlined underwriting that is perfect for broad-based corporate programs.

  • Transamerica: Transamerica’s IIUL portfolio is built for accumulation, offering diverse index choices including global options like the EURO STOXX 50.


Is IIUL Right for Your Organization?


Building The Perfect Plan® starts with asking the right questions.


  • What happens to your business if a key executive leaves tomorrow?

  • Are you currently losing 40% of your benefit's value to taxes?

  • Does your current retention strategy provide 100% income protection to your employees' families?


If these questions are keeping you up at night, it’s time for a more sophisticated approach. Institutional Indexed Universal Life isn't just an insurance policy; it is a strategic financial tool designed to restore alignment between your company's goals and your key people’s needs.


A sophisticated boardroom setting with a focused business leader looking out over a city, representing the long-term vision required for executive benefit planning.


Ready to see where you stand?


At Schiff Executive Benefits, we believe in data-driven decisions. Before you design a plan, you need to know what your business is actually worth and where the gaps lie.


We invite you to start your business valuation and data capture here. It’s the first step toward realizing your dream value and ensuring your legacy is protected.


Sit back, grab your coffee, and let’s talk about how we can help you attract, retain, and reward your best people: Restoring Alignment and Retention for the long haul.


In the high-stakes world of community and regional banking, the pursuit of yield is never just about the numbers on a spreadsheet; it is a delicate dance between regulatory capital constraints and the mandate for long-term stability. Every CFO knows the universal truth: you cannot manage what you cannot predict. When it comes to Bank Owned Life Insurance (BOLI), that predictability has historically been bifurcated. You either chose the safety and simplicity of a General Account (GA) structure or the transparency and potential of a Separate Account (SA) structure.


But the financial landscape is rarely that binary. For banks that demand the creditor insulation of a separate account without the stomach-turning volatility of mark-to-market accounting, there is a third way.


Hybrid Account Universal Life BOLI is the "best of both worlds" solution that has quietly become the preferred tool for sophisticated bank boards. It is a strategic middle ground: a product that reverse-engineers the best parts of insurance mechanics to serve the specific needs of a bank’s balance sheet.


The Structural "Sweet Spot": How Hybrid BOLI Works


To understand the value of a Hybrid Account, you first have to understand the tension it resolves.


Historically, General Account BOLI was the standard. The bank paid a premium, and those assets became part of the insurance carrier’s general investment pool. The carrier guaranteed a minimum crediting rate, and the bank enjoyed book-value accounting. The downside? The bank was essentially an unsecured creditor of the insurance company. If the carrier faltered, so did the bank’s asset.


On the other hand, Separate Account BOLI offered transparency and legal insulation. The assets were held in a separate account, away from the carrier’s general creditors. However, this often introduced "mark-to-market" volatility. Unless the bank paid for an expensive Stable Value Protection (SVP) wrap, the fluctuation in the underlying investment portfolio would flow directly through the bank’s P&L.


Hybrid Account BOLI changes the math.


In a Hybrid structure, part of the assets sit in a legally insulated separate account. This provides the bank with the transparency it desires and the creditor protection it needs. However: and this is the "magic" of the hybrid design: the carrier provides a contractually guaranteed minimum crediting rate, much like a General Account product.


Because the carrier is providing the "floor," there is no need for a Stable Value Protection wrap. The carrier contractually guarantees the book-value accounting, meaning the bank does not face direct market value exposure. You get the transparency and insulation of a separate account with the smoothed, predictable income of a general account.


Professional bankers discussing financial strategies over a digital tablet in a clean, modern office.


Why It Matters: Yield Enhancement Without the Volatility


For a bank’s investment committee, the appeal of Hybrid BOLI usually centers on two portfolios: Yield and Yield Plus.


Unlike traditional General Account BOLI, where the bank has no say in how the assets are deployed, Hybrid Account products often allow the bank to benefit from multiple portfolio options. These portfolios are managed with an eye toward high-grade corporate bonds and other bank-eligible investments, but they are structured to allow for slightly higher yield targets than a standard GA product might offer.


Because these are Universal Life chassis, the crediting rate is declared by the carrier based on the performance of these underlying portfolios. However, since the carrier guarantees the floor, the bank doesn't have to worry about a "bad month" in the bond market hitting their quarterly earnings report.


At Schiff Executive Benefits, we specialize in this kind of goal-oriented reverse engineering. We don't just look at the carrier; we look at the intent. If your goal is to fund an Executive NQDC plan or offset the rising costs of employee benefits, the Hybrid structure offers a unique way to match those long-term liabilities with a stable, high-performing asset.


The Regulatory Reality: Accounting and Risk Weighting


From a technical perspective, Hybrid Account BOLI is a masterclass in balance sheet efficiency.


Book-Value Accounting


The primary concern for most bank CFOs is the impact on the P&L. Because Hybrid BOLI uses a crediting-rate approach backed by the carrier’s guarantee, it qualifies for book-value accounting. The bank records the Cash Surrender Value (CSV) as an "Other Asset." The growth in that CSV (the net of the crediting rate minus charges) is recognized as noninterest income. This provides a clean, predictable line item that bank analysts and regulators appreciate.


Risk Weighting


The risk weighting of BOLI is a critical component of Tier 1 Capital management. Under current regulatory frameworks (including Basel III), the risk weighting of Hybrid BOLI typically depends on its composition. While General Account BOLI is usually 100% risk-weighted (corporate-style), and Separate Account BOLI can sometimes be "looked through" to the underlying government-grade assets for a lower weight, Hybrid BOLI is often treated as a blend.


However, many institutions find that the "100% risk weight" trade-off is more than worth it when you consider the lower cost of capital compared to the volatility of a non-wrapped Separate Account.


A legal or technical administrative setting showing a stack of documents and a pen, representing regulatory compliance.


Carrier Spotlight: The NYLIAC BOLI 50


One of the most prominent examples of this technology in action is the NYLIAC BOLI 50 from New York Life. As a Hybrid Account Universal Life product, it has become a staple for banks looking for a high-quality carrier with a "AAA" pedigree.


The BOLI 50 allows banks to access the Yield and Yield Plus portfolios while maintaining that crucial book-value treatment. It’s designed for the bank that wants a household name carrier but doesn't want to settle for the lower "current" rates of a standard general account.


The "What If" Factor: Planning for the Long Term


At Schiff Executive Benefits, we don't just sell products; we solve for the "What Ifs." When we sit down with a bank board, we aren't just talking about Hybrid BOLI; we are talking about:


  1. Top talent leaving – How does this asset fund the retention package to keep your CEO?

  2. Senior exec retirement – Can we offset the replacement cost effectively?

  3. Running out of retirement money – How do we ensure the plan stays solvent for decades?


Our President, Matt Schiff, brings a unique level of authority to these conversations. He didn't just study the laws; he was in the room when they were written. As a ranking member of the AALU's NQDC Committee, Matt helped draft the very regulations (IRC 409A and IRC 101(j)) that govern how these plans must be structured today.


When you work with us, you are getting an architect who understands the "code" of the IRS, not just a contractor who knows how to swing a hammer. We ensure your program is fully compliant with the latest regulations, ensuring that your BOLI remains a tax-advantaged powerhouse rather than a compliance liability.


Restoring Alignment and Retention


Ultimately, Hybrid Account BOLI is a tool for alignment. It aligns the bank's need for stability with the executive's need for a robust benefit structure. It is a key component of The Perfect Plan®, our proprietary approach to ensuring that every dollar on the balance sheet is working toward a specific cultural and financial goal.


If you are a bank decision-maker looking to optimize your BOLI portfolio or replace an underperforming General Account plan, the time to look at Hybrid options is now.


Ready to see how Hybrid BOLI fits your balance sheet?


Sit back, grab your coffee, and let’s look at the numbers. We invite you to join us for a consultative deep dive into your current benefits structure.


The "Perfect Plan®" isn't a myth: it's a reverse-engineered reality. Let’s build it together.


A close-up of a professional handshake in a corporate setting, signifying a partnership and trust.


Learn more: our complete guide to Bank Owned Life Insurance (BOLI).


In the world of institutional finance, transparency is the bedrock of trust. For many community and regional banks, Bank-Owned Life Insurance (BOLI) has long been a foundational asset, providing a tax-advantaged vehicle to offset employee benefit liabilities. However, as institutions grow in complexity and assets, the "General Account" model: where the bank’s capital is comingled with the insurer's general creditors: can sometimes feel like a black box.


For sophisticated bank decision-makers and ALM (Asset Liability Management) teams, the shift toward Separate Account Universal Life BOLI represents a move from passive participation to strategic control. It is a structure designed for those who demand clarity on where their dollars are invested, how they are protected, and how they can be optimized for long-term yield.


At Schiff Executive Benefits, we specialize in reverse-engineering these sophisticated benefit structures to ensure they align perfectly with your bank's culture and financial goals. Our mission is centered on Restoring Alignment and Retention.


The Architecture of Insulation: Legally Segregated Accounts


The defining characteristic of Separate Account BOLI is the legal "moat" it builds around your assets. Unlike General Account BOLI, where the bank is effectively a general creditor of the insurance company, Separate Account premiums are held in a legally segregated account.


Under OCC Bulletin 2004-56, the regulatory framework is clear: these assets are insulated from the claims of the insurer's general creditors in the event of insolvency. For a bank's risk committee, this provides a layer of counterparty risk mitigation that is simply unavailable in traditional products. You aren't just buying a policy; you are securing a dedicated asset pool.


A modern glass skyscraper reflecting the sky, symbolizing the transparency and structural integrity of Separate Account BOLI.


Transparency and Investment Control through IRC 817(h)


One of the primary frustrations with traditional BOLI is the lack of visibility into the underlying portfolio. Separate Account BOLI flips this script. By utilizing third-party investment managers, banks can achieve a level of transparency that rivals their own investment portfolios.


However, this control comes with strict regulatory guardrails. To maintain the tax-advantaged status of the life insurance contract, the account must comply with IRC §817(h) diversification requirements. This ensures that the policy remains treated as insurance rather than a taxable investment.


Furthermore, "Investor Control" rules stipulate that while the bank can choose from a menu of sophisticated investment strategies managed by professional firms, they cannot direct individual security trades. This is where our expertise at Schiff Executive Benefits becomes invaluable. We help you navigate these nuances, ensuring your BOLI program remains compliant while pursuing the yield your institution requires.


Managing Volatility: The SVP "Wrap" and Book-Value Accounting


If Separate Account BOLI offers better transparency and yield potential, why doesn't every bank use it? The answer often lies in the accounting treatment.


By default, Separate Account assets are subject to mark-to-market accounting. For a bank’s P&L, the daily fluctuations of the underlying bond or equity markets can create unwanted volatility. This is where the Stable Value Protection (SVP) wrap comes into play.


An SVP wrap is a contract: often provided by a highly-rated financial institution or the insurer themselves: that allows the bank to report the asset at "book value" rather than fair market value. This "wraps" the volatility, amortizing gains and losses over time to provide a steady, predictable crediting rate. For banks with sophisticated ALM teams, the ability to harvest the "equity risk premium" or higher-duration yields without the immediate P&L sting is a game-changer.


Legal and financial reference books on a mahogany desk, representing the regulatory compliance required for IRC 817(h) and OCC 2004-56.


Capital Efficiency: The Look-Through Advantage


From a regulatory capital perspective, Separate Account BOLI offers a distinct advantage over its General Account counterparts. Under the "look-through" approach, banks can risk-weight the BOLI asset based on the underlying securities within the separate account.


While General Account BOLI is typically risk-weighted at 100% (or 20% if the insurer is highly rated, though this is increasingly rare), Separate Account portfolios focused on high-quality government or agency bonds can often achieve a risk-weighting as low as 20%. This makes Separate Account BOLI an incredibly capital-efficient tool for larger regional or commercial banks looking to optimize their Tier 1 capital ratios.


Why Technical Expertise Matters: The Schiff Legacy


Navigating the intersection of life insurance, tax law, and bank regulation requires more than just a broker; it requires an architect. Matt Schiff, President of Schiff Executive Benefits, brings a unique level of authority to this space. Having served as a ranking member of the AALU's NQDC Committee, Matt helped draft the very laws: like IRC 409A and 101(j): that govern these plans today.


When you work with us, you are working with a team that was "in the room where it happened." We don't just follow the rules; we understand the intent behind them. This technical depth is why we emphasize an integrated approach, working alongside your existing accountants, attorneys, and TPAs to ensure The Perfect Plan® is not just a concept, but a compliant reality.


A professional handshake between two executives in a modern office, signifying the partnership between a bank and Schiff Executive Benefits.


Is Separate Account BOLI Right for Your Bank?


This structure is ideal for institutions that meet several criteria:


  • Asset Size: Generally, banks with $1 billion or more in assets find the administrative and wrap costs of Separate Accounts more justifiable.

  • ALM Sophistication: Banks with dedicated teams capable of monitoring third-party managers and understanding SVP dynamics.

  • Yield Requirements: Institutions looking to outperform the "standard" General Account rates by taking a longer-term, more transparent investment view.

  • Capital Constraints: Banks looking for higher risk-adjusted returns on capital.


Your Path to a More Sophisticated BOLI Strategy


The decision to transition to or implement a Separate Account structure shouldn't be made in a vacuum. It requires a deep dive into your bank’s specific "What If's": from top talent retention to the long-term cost recovery of executive benefits.


We invite you to explore our BOLI process to see how we reverse-engineer solutions based on your specific goals. If you are ready to evaluate your bank's current valuation and potential for a more sophisticated retention tool, we encourage you to use our Business Valuation and Prospect Data Capture tool.


For more insights into high-level financial planning and executive benefits, visit The Perfect Plan® YouTube channel.


At Schiff Executive Benefits, we don't just sell insurance; we build the structures that protect your bank's most valuable asset: its people. Come join us, grab a coffee, and let's discuss how we can bring transparency and stability to your balance sheet.


SEO Pre-flight Check:


  • Meta Description: Explore the benefits of Separate Account Universal Life BOLI for banks. Learn about OCC 2004-56 compliance, IRC 817(h) diversification, and the capital efficiency of the look-through approach.

  • Alt Text: All images include descriptive alt text with target keywords like BOLI, Separate Account, and bank executives.

  • Keywords: Primary keyword "Separate Account Universal Life BOLI" included in H1, intro, and H2 headers.

  • Internal Links: Links provided to the main BOLI page and the BOLI process page.


Learn more: our complete guide to Bank Owned Life Insurance (BOLI).


In the world of community banking, certainty is the ultimate currency. We often tell our clients that while the markets might be a rollercoaster, your balance sheet shouldn't be. When you are looking to offset the rising costs of executive benefits or simply looking for a stable way to deploy excess liquidity, the conversation inevitably turns to Bank Owned Life Insurance (BOLI).


Among the various structures available, General Account Universal Life BOLI remains the bedrock of the industry. It is the most common, the most straightforward, and for many institutions, the most appropriate tool for the job. But as with any sophisticated financial instrument, the "simple" option still requires a deep dive into the mechanics, the risks, and the regulatory expectations.


At Schiff Executive Benefits, we don’t just broker these plans; we reverse-engineer them. We look at your culture, your "What Ifs," and your long-term goals to ensure that the plan you implement today is the one that still makes sense twenty years from now.


What is General Account BOLI?


At its core, a General Account BOLI policy is a contract between the bank and an insurance carrier. The bank pays a premium, and those funds are pooled into the insurer’s general account. This general account is typically a massive, conservatively managed portfolio of high-quality bonds, mortgages, and real estate.


Unlike Separate Account BOLI, where the bank’s assets are segregated and the bank chooses the investment managers, General Account BOLI relies on the carrier’s overall investment performance.


The Mechanism of Stability


When you opt for a General Account structure, you are essentially trading control for a guarantee. The carrier provides a guaranteed minimum crediting rate. Even if the market takes a dive, your cash value won't drop below a certain floor.


For a community bank, the primary appeal is the lack of "mark-to-market" volatility. Because the carrier assumes the investment risk, the bank does not have to report fluctuations in the underlying bond portfolio on its P&L. Instead, you see predictable, tax-advantaged growth in the cash surrender value (CSV) of the policies.


A pair of professional hands reviewing technical financial documents and a compass, symbolizing the strategic direction of General Account BOLI


The Trade-Off: Transparency vs. Security


No financial strategy is without its hurdles. While the stability of General Account BOLI is its greatest strength, it comes with two primary trade-offs:


  1. Lack of Transparency: Since your premiums are pooled with the carrier's other assets, you don't have a window into exactly which bonds or properties are backing your policy. You are trusting the carrier’s investment committee and their historical track record.

  2. Credit Risk: This is the big one. In a General Account structure, the bank is a general creditor of the insurance company. If the carrier runs into financial trouble, your BOLI assets are at risk. This is why we place such a heavy emphasis on carrier selection. We look at A.M. Best, Moody’s, and S&P ratings with a skeptical eye, ensuring the carriers we recommend have the "staying power" to fulfill their long-term promises.


Regulatory Landscape: OCC 2004-56 Compliance


If you’ve spent any time in a boardroom, you know that regulators don't just care about what you buy; they care about how you bought it. OCC 2004-56 (the Interagency Statement on the Purchase and Risk Management of Life Insurance) is the "bible" for BOLI compliance.


General Account BOLI is treated as a complex asset. Regulators expect you to perform a rigorous pre-purchase analysis that includes:


  • Business Purpose: You must document exactly why you are buying BOLI. Usually, this is to fund specific executive benefit obligations like a Non-Qualified Deferred Compensation (NQDC) plan or a SERP.

  • Risk Assessment: You need to quantify the liquidity, credit, and interest rate risks.

  • Concentration Limits: You can't put all your eggs in one carrier's basket.

  • Board Approval: Your board needs to understand the "What Ifs." What if the carrier is downgraded? What if the crediting rate drops to the minimum?


Under current regulatory capital rules, General Account BOLI is typically risk-weighted at 100%. While this is higher than the 20% weighting often found in Separate Account structures, many banks find the trade-off for P&L stability to be well worth the capital charge.


Executives in a collaborative boardroom meeting discussing bank-owned life insurance and talent retention strategies


Why Community Banks Prefer the General Account


Why is this the "simplest and most common" structure? Because most community banks aren't in the business of managing insurance investment portfolios. They want a "set it and forget it" solution: though we prefer the term "set it and monitor it."


General Account BOLI provides:


  • Predictable Non-Interest Income: The steady crediting rate helps smooth out earnings.

  • Cost Offset: It is a highly efficient way to recover the costs of the benefits needed to attract and retain top talent.

  • Simplicity: There is no need for complex daily accounting of underlying securities.


The Schiff Perspective: "In the Room Where it Happened"


When you work with Schiff Executive Benefits, you aren't just getting a broker; you’re getting a partner with deep technical roots. Our President, Matt Schiff, didn't just study these laws: he was a ranking member of the AALU's NQDC Committee and worked alongside Michael Goldstein to help draft the very regulations that govern these plans today (IRC 409A and IRC 101(j)).


We understand the nuances of IRC 101(j) notice and consent requirements. If you miss a signature or a filing date, your tax-free death benefit could become taxable. That’s a "What If" no bank wants to face. We ensure your program is bulletproof from day one.


You can hear more about these technical nuances and our approach to The Perfect Plan® on our YouTube channel, where we break down the complexities of executive benefits into actionable insights.


A modern, glass-clad office building reflecting the institutional strength and stability of a bank's financial foundation


Is Your BOLI Aligned?


General Account Universal Life BOLI is an incredible tool for restoring alignment and retention within your leadership team. It protects the bank's bottom line while providing the "Perfect Plan®" for your executives' future.


However, the "set it and forget it" mentality can be dangerous. As interest rates shift and carrier credit profiles evolve, your BOLI portfolio needs regular check-ups. Are you still compliant with OCC 2004-56? Is your 101(j) paperwork in order? Are you maximizing your risk-adjusted return?


If you are ready to take a closer look at your current BOLI strategy or are considering a new purchase, let's have a conversation. We can help you navigate our BOLI Process and ensure your Bank Owned Life Insurance program is performing exactly as intended.


Sit back, grab your coffee, and let’s build something that lasts.


To get a clearer picture of your bank’s current valuation and how an executive benefit strategy can impact your bottom line, we invite you to use our RISR application. It’s a simple way to start the journey toward a more secure and aligned future.


SEO Pre-flight Check:


  1. Meta Description: Discover why General Account Universal Life BOLI is the preferred choice for community banks seeking stability, tax-advantaged growth, and OCC 2004-56 compliance.

  2. Alt Text: All images include descriptive alt text with keywords like BOLI, General Account BOLI, and Bank Owned Life Insurance.

  3. Keyword Placement: "General Account BOLI" and "Bank Owned Life Insurance" appear in H1, H2s, and throughout the text.

  4. Internal Links: Links provided to /our-boli-process, /boli-bank-owned-life-insurance, and the Perfect Plan® YouTube channel.


Learn more: our complete guide to Bank Owned Life Insurance (BOLI).


In a world that often prizes the "new and flashy," there is an undeniable truth that remains constant: stability is the bedrock of any successful long-term strategy. For a business, stability isn't just about this quarter's earnings; it’s about ensuring that the promises you make today: to your family, your partners, and your key executives: can be kept decades from now.


When we look at the various types of products available in the market for informal funding of executive benefits, Whole Life insurance stands as the "Old Guard." It is the architectural foundation upon which many of the most secure Corporate Owned Life Insurance (COLI) and Bank Owned Life Insurance (BOLI) programs are built.


If you are looking for a financial vehicle that eliminates the "what ifs" of market volatility, Whole Life is often the answer.


The Mechanics of Permanence


Whole Life is exactly what it sounds like: permanent life insurance designed to cover the insured for their entire life. Unlike term insurance, which expires, or universal life products, which may have flexible premiums that can fluctuate, Whole Life is defined by its rigidity: and in the corporate world, that rigidity is its greatest strength.


The core features of a Whole Life policy include:


  • Guaranteed Cash Value Growth: The cash value in a Whole Life policy grows according to a set schedule. It doesn't matter what the S&P 500 does tomorrow; your cash value is contractually guaranteed to increase every year.

  • Fixed Premiums: Your premiums are locked in from day one. They will never increase, regardless of the economy or the health of the insured. This allows for precise long-term budgeting for deferred compensation plans.

  • Dividends (The Performance Kicker): While not guaranteed, "participating" Whole Life policies from mutual insurance companies often pay annual dividends. These dividends can be used to purchase additional insurance, reduce premiums, or boost the cash value even further.


An executive team in a high-end boardroom discussing long-term corporate strategy and risk management.


The "Sleep Well at Night" Factor


For the risk-averse corporate buyer, Whole Life offers what we call the "sleep well at night" factor. When a company uses life insurance to fund a Supplemental Executive Retirement Plan (SERP), they are essentially creating a liability on their balance sheet. They are promising an executive a future payment.


If you fund that promise with a volatile asset, you are taking on "asset-liability mismatch" risk. If the market crashes the year your executive retires, you may find yourself short on the funds needed to pay the benefit.


Whole Life eliminates that mismatch. Because the growth is guaranteed, you can "reverse engineer" your Perfect Plan® with mathematical certainty. You know exactly what the asset will be worth at any given point in the future, ensuring you can meet your obligations to your top talent without straining the company’s cash flow.


The Role of Whole Life in COLI and BOLI


In the realm of Bank Owned Life Insurance (BOLI), Whole Life is a staple. Banks are highly regulated entities that value capital preservation above almost all else. The guaranteed nature of Whole Life cash values aligns perfectly with a bank’s Tier 1 capital requirements.


For corporations, Whole Life serves as a powerful engine for full cost recovery. When we design a plan at Schiff Executive Benefits, our goal is often to ensure the company recovers every dollar spent on the benefit, every dollar of premium paid, and even the "opportunity cost" of those funds. The predictable, tax-advantaged growth of Whole Life makes this math not just possible, but repeatable.


A close-up of a compass on a map, representing the clear direction and guidance provided by a well-structured insurance plan.


Regulatory Expertise: Being in the "Room Where It Happened"


When you are dealing with permanent products like Whole Life, compliance is not optional. You need an advisor who understands the "why" behind the regulations.


Matt Schiff, the President of Schiff Executive Benefits, doesn't just read the laws; he helped write them. In 2003 and 2005, Matt served as a ranking member of the AALU's NQDC Committee alongside Michael Goldstein. Together, they helped draft the very regulations that govern IRC 409A (which dictates how deferred compensation is taxed) and IRC 101(j) (which covers employer-owned life insurance).


This "insider" expertise is why we focus so heavily on ensuring your programs are designed to satisfy every government requirement. To hear more about the history of these regulations directly from the source, we invite you to watch Matt’s conversation with Dan Hogans (formerly of the IRS Treasury) on The Perfect Plan® Podcast.


Solving the Five "What Ifs"


Every business owner we meet is haunted by the same five questions. Whole Life is a versatile tool that provides answers to almost all of them:


  1. What if you end up in business with a widow? Whole Life can fund buy-sell agreements with a guaranteed death benefit.

  2. What if there is a business buy-out? The accumulated cash value provides the liquidity needed for a smooth transition.

  3. What if your top talent leaves? A Whole Life-funded NQDC plan creates "Golden Handcuffs" that reward the executive for staying.

  4. What if you need to replace a senior executive? The tax-free death benefit provides the capital to recruit and train a successor.

  5. What if you run out of retirement money? The policy's cash value can be accessed tax-efficiently to provide a "guaranteed paycheck and a playcheck."


A professional handshake between two executives, symbolizing the trust and retention built through executive benefit programs.


Restoring Alignment and Retention


At Schiff Executive Benefits, we believe that the best plans are those that align the interests of the business owner with the interests of their key people. We call this Restoring Alignment and Retention.


Whole Life is not the only tool in our belt, but for companies that value certainty, guarantees, and a "set it and forget it" approach to financial security, it is often the most appropriate.


If you’re ready to see how the mathematical certainty of Whole Life can strengthen your business, we invite you to take the first step. Use our Business Valuation Tool to see what your company is worth today, then let’s sit down, grab a coffee, and build your Perfect Plan®.


Come join us at The Perfect Plan® and let’s start planning for all of life's "What Ifs."


Change is constant. Process matters. If you're evaluating bank owned life insurance, you need a framework that is clear, compliant, and easy for leadership to follow. Our BOLI process is designed to help banks move from early evaluation to confident implementation without unnecessary complexity. At Schiff Executive Benefits, we make BOLI implementation easier to understand, easier to present, and easier to manage.


Why This Process Matters


A successful BOLI process helps your bank:


  • Offset employee benefit costs

  • Support executive benefit liabilities

  • Stay aligned with risk and capital considerations

  • Give the board a clean path to informed decision-making


Bank executives in a clean modern boardroom reviewing BOLI implementation strategy and OCC 2004-56 compliance


Foundation: OCC 2004-56


Every sound BOLI implementation starts with OCC 2004-56. This guidance sets the standard for how banks evaluate risk, document their analysis, and approach bank owned life insurance as a safe and sound asset. We treat OCC 2004-56 as the starting point, not the finish line. That keeps the entire BOLI process focused, defensible, and board-ready.


The 10-Step BOLI Process


Our pre-purchase analysis is built to help bank leadership evaluate structure, risk, pricing, and fit before moving forward.


1. Calculate Employee Benefit Liabilities


Define the benefit costs the BOLI program is meant to offset.


2. Conduct OCC Testing


Measure capital impact, earnings alignment, and insurance-to-capital positioning.


3. Analyze Insurable Interest


Confirm legal eligibility and proper insurable interest for covered lives.


4. Review Risk


Evaluate credit risk, interest rate risk, liquidity risk, and legislative risk.


5. Prepare Financial Models


Run independent projections for yield, surrender outcomes, and cost recovery.


6. Review Carrier Investment Strategy


Assess how the carrier invests and whether that approach fits your bank.


7. Review Policy Characteristics


Compare General Account, Separate Account, and Hybrid Account options.


8. Reverse-Engineer the Product


Build the design around your bank’s goals instead of forcing a shelf product.


9. Negotiate Final Pricing


Work to improve net yield, pricing, and overall policy economics.


10. Support Board Review


Deliver a concise executive summary and due diligence package for approval.


Implementation and Ongoing Support


Approval is not the end of the BOLI process. It is the beginning of proper execution. We support the full BOLI implementation phase, including documentation, employee consent, policy placement, and delivery. After purchase, we continue with annual reviews, carrier monitoring, and updated analysis so your bank owned life insurance strategy stays aligned with the original goal. We also work alongside your existing advisors, including accountants, attorneys, and TPAs, so the process stays coordinated and efficient.


Ready to implement a smarter BOLI strategy?


Schedule a consultation For a broader look at related executive benefit strategies, visit our services.


Meta Description: Our BOLI process helps banks streamline BOLI implementation with clear steps, OCC 2004-56 alignment, and practical bank owned life insurance guidance.


Learn more: our complete guide to Bank Owned Life Insurance (BOLI).


  • The Short Answer


    Bank-Owned Life Insurance (BOLI) is life insurance a bank purchases on the lives of its officers and directors, where the bank owns the policy, pays the premium, and is the beneficiary. Banks use BOLI as a tax-advantaged balance sheet asset to offset the rising cost of employee benefit programs. Cash surrender value grows tax-deferred, death proceeds are generally received income-tax-free, and the resulting yield typically exceeds what the same capital would earn in taxable short-term instruments of comparable credit quality.


    BOLI is permissible for national banks under 12 U.S.C. 24 (Seventh) and is governed by the 2004 Interagency Statement on the Purchase and Risk Management of Life Insurance. Regulators generally expect aggregate cash surrender value to stay within 25% of Tier 1 capital, with no more than 15% placed with any single carrier. A documented pre-purchase analysis is not optional.


    The same structure bought by an operating company is called COLI; bought by an insurance carrier, iCOLI.


    A bank is only as strong as its community, and its community is only as strong as the leaders who serve it. In the financial world, stability is the cornerstone of trust. Yet, many bank executives find themselves facing an unstable paradox: how do you maintain a competitive edge and protect your balance sheet while simultaneously funding the escalating costs of employee benefits?


    If you are leading a financial institution today, you are likely wrestling with the "What Ifs" that keep even the most seasoned presidents awake at night. What if your top talent is lured away by a larger competitor? What if the cost of your pension and health plans continues to outpace your portfolio’s yield? What if your senior executive retirement costs become a drag on your regulatory capital?


    To find the answer, we look toward a strategy utilized by over 65% of banks in the United States. It is a tool designed for Restoring Alignment and Retention: Bank-Owned Life Insurance (BOLI).


    What is BOLI, and Why Does It Matter?


    At its most fundamental level, Bank-Owned Life Insurance is a life insurance policy purchased by a bank on the lives of its key employees: usually officers and directors. The bank is the owner and the beneficiary of the policy.


    While the term "insurance" is in the name, for a financial institution, BOLI is primarily a sophisticated investment and a Tier 1 asset. The bank pays a premium (often a single lump sum), and the cash value of the policy grows over time.


    Why is this so popular? Because it solves the problem of "lazy capital." Instead of holding assets in low-yield taxable instruments, banks move capital into a tax-advantaged BOLI structure where the growth can offset specific liabilities. It is a method of taking a "dead" expense: like the cost of executive benefits: and turning it into a high-performing asset.
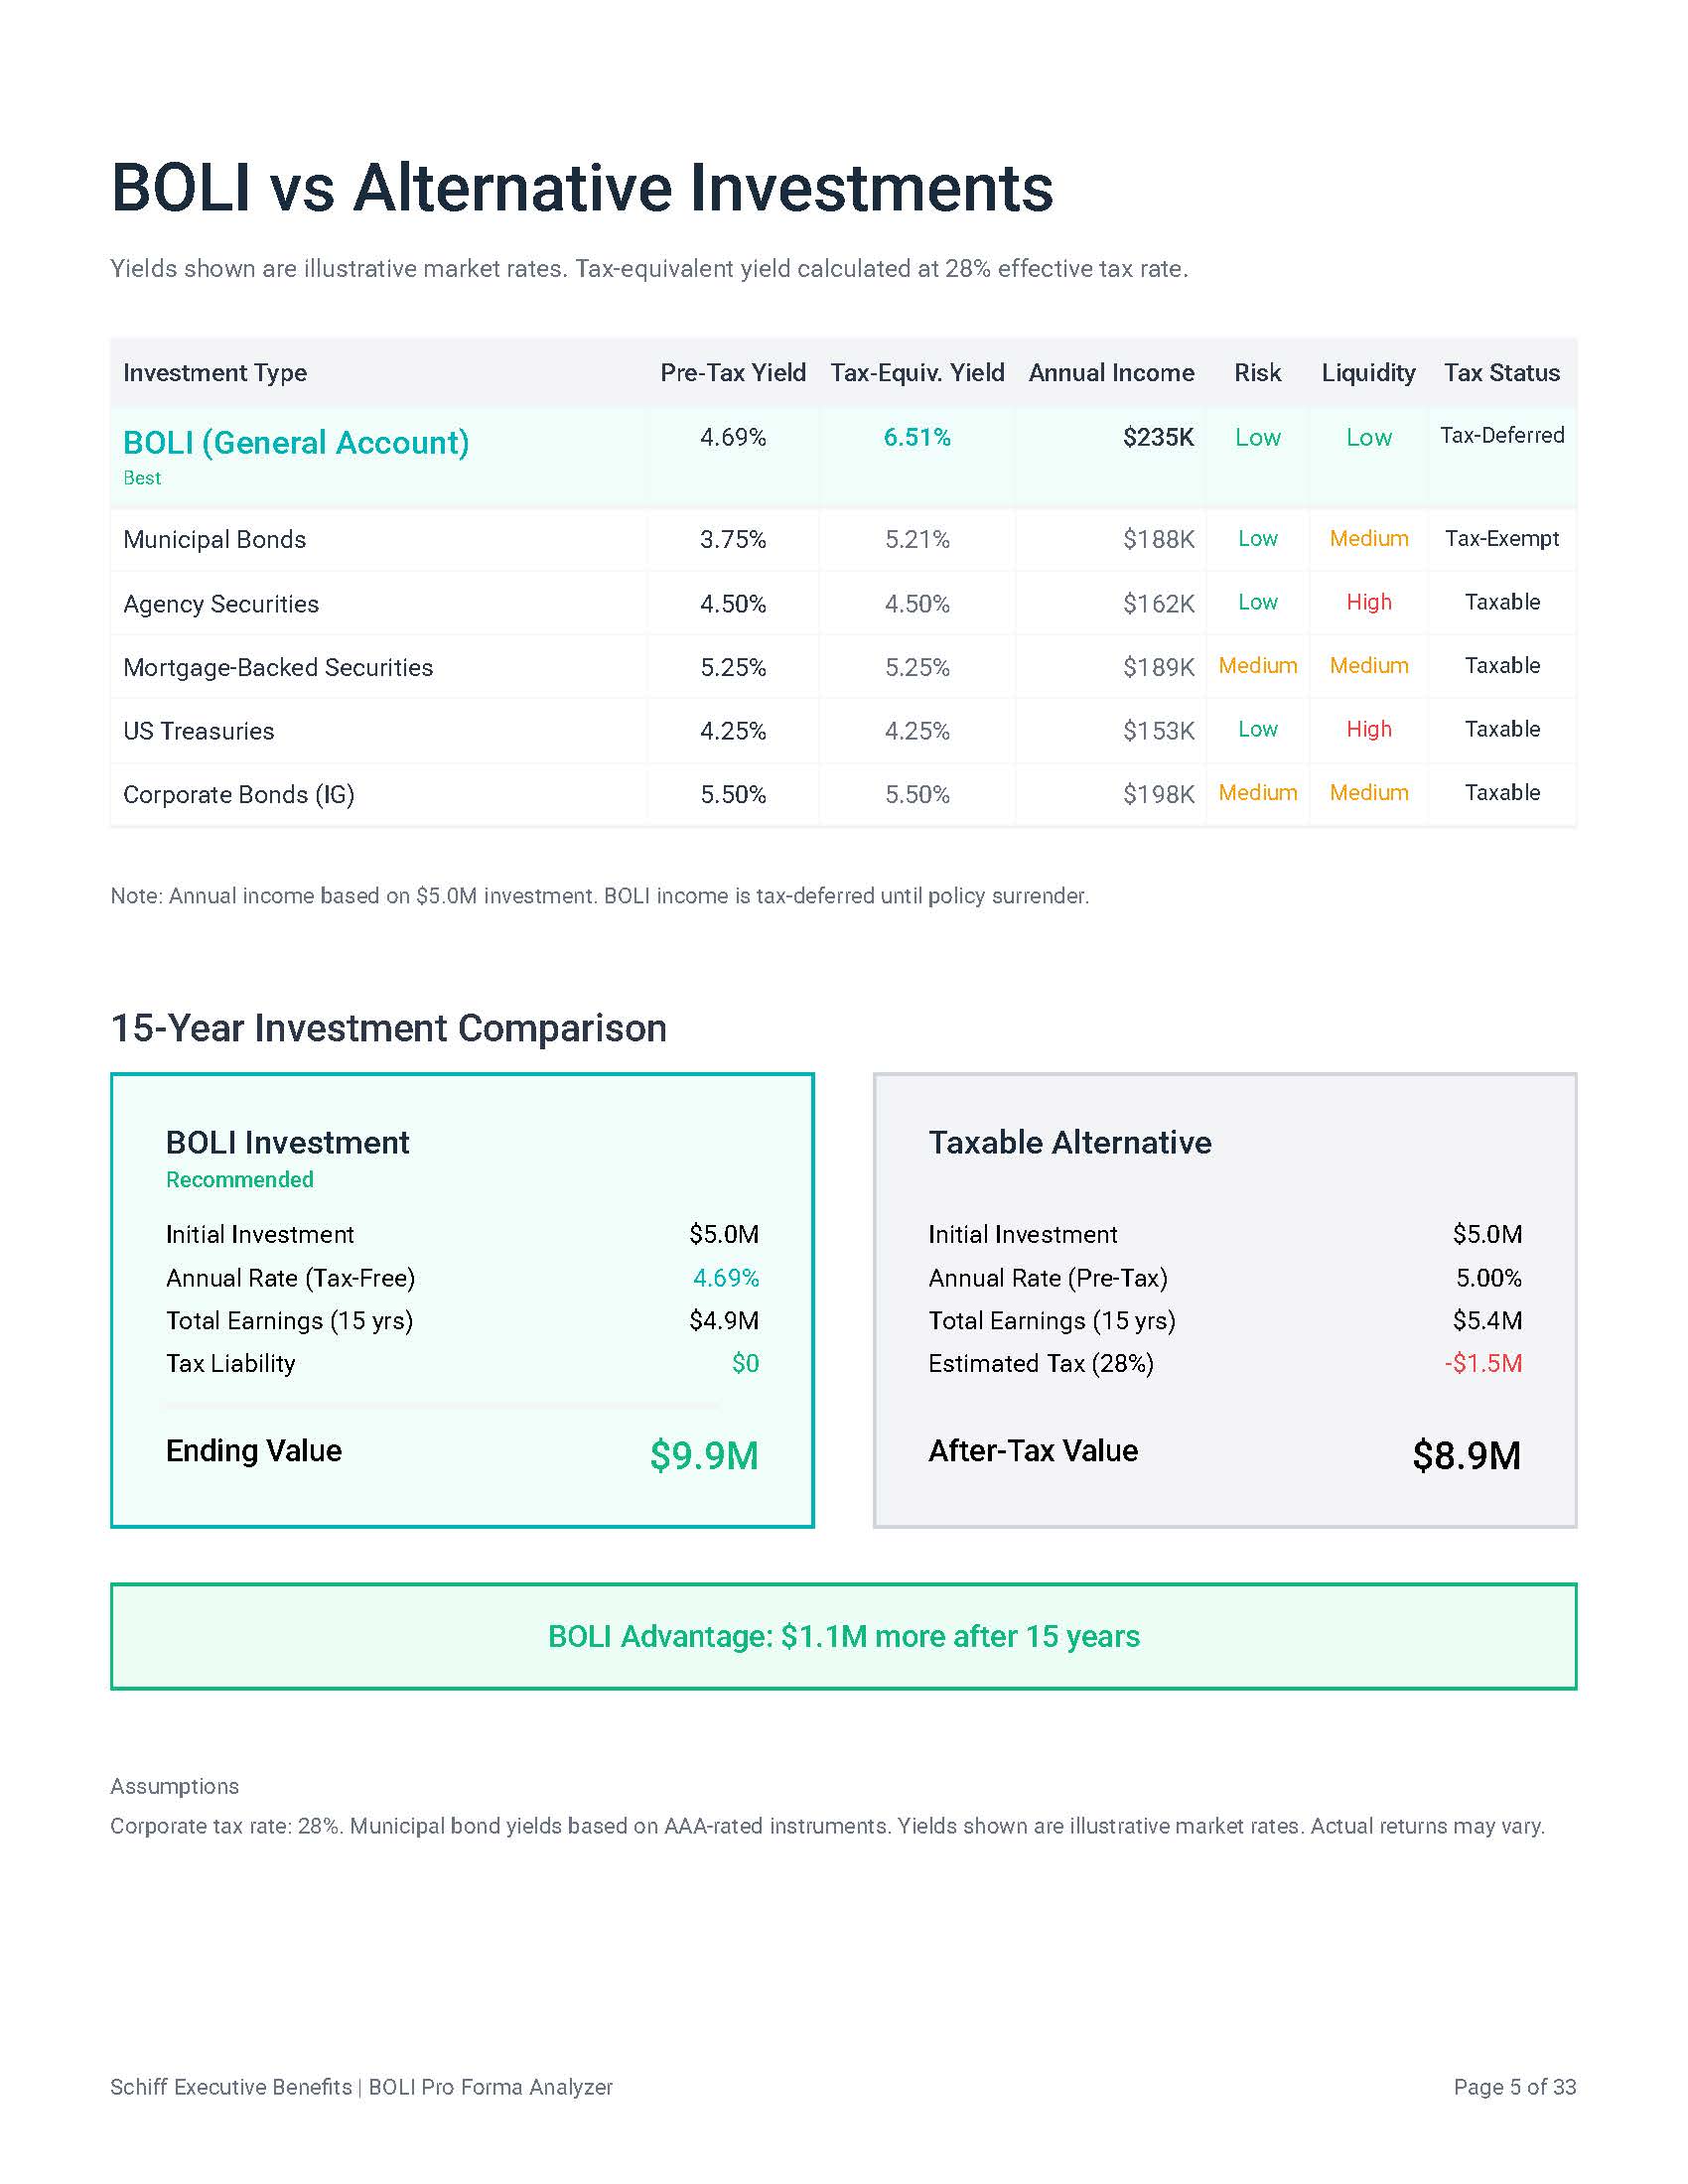

    Comparison chart showing Bank-Owned Life Insurance (BOLI) versus alternative fixed income investments


    The Economic Reality: After-Tax Yield and Efficiency


    In a world where interest rates are volatile and traditional fixed-income yields are often squeezed by taxes, BOLI stands out as a beacon of efficiency.


    When you compare BOLI to alternative fixed-income investments: such as municipal bonds, agency securities, or Treasuries: the difference is often staggering. Because the cash value growth within a BOLI policy is tax-deferred (and tax-free if held until the death of the insured), the "tax-equivalent" yield is significantly higher than what a bank can typically earn elsewhere.


    As shown in our proprietary BOLI Pro Forma Analyzer, a $5 million investment in BOLI can provide a tax-equivalent rate that significantly outperforms corporate bonds or MBS portfolios. This isn't just about "beating the market"; it’s about generating the necessary cash flow to fund Non-Qualified Deferred Compensation (NQDC) and other executive carve-outs that are essential for retention.


    Offsetting the Rising Cost of Talent


    What is the true cost of losing your CFO or a high-performing VP of Lending? It isn't just the recruiter's fee. It is the loss of institutional knowledge, the disruption of client relationships, and the significant expense of "buying" a replacement in a competitive market.


    Most banks use BOLI to recover the costs of:


    • Post-retirement medical benefits

    • Supplemental Executive Retirement Plans (SERPs)

    • Group term life insurance premiums

    • 401(k) matching and pension obligations


    By utilizing BOLI, you are essentially creating an informal "sinking fund" to pay for these future obligations. It allows you to offer "ownership-like" benefits without actually diluting your bank’s equity. This is how you retain your key people while keeping the bank’s financial health intact.

    Bank executives in a boardroom discussing bank-owned life insurance and executive retention strategies.


    Regulatory Compliance: The Tier 1 Advantage


    One of the most frequent questions I get from Bank Presidents is: "How will the regulators view this?"


    The answer is found in the Interagency Statement on the Purchase and Risk Management of Life Insurance. BOLI is recognized as a permissible investment for banks, provided it is managed within specific guidelines. Most notably, the Office of the Comptroller of the Currency (OCC) and other regulators generally allow BOLI holdings up to 25% of a bank’s Tier 1 capital.


    Because BOLI is a high-quality asset backed by highly-rated insurance carriers, it provides a stable foundation for your balance sheet. Unlike securities portfolios, BOLI cash values are typically not subject to the "mark-to-market" volatility that can plague a bank during periods of rising interest rates. This makes it a preferred tool for managing earnings consistency.


    The Human Element: Survivor Income as an Incentive


    While the bank is the primary beneficiary, BOLI can also be structured to provide a powerful direct benefit to the insured executives.


    Through "split-dollar" arrangements, a portion of the death benefit can be directed to the executive’s family. This provides "pre-retirement survivor income": a massive incentive for a key leader who wants to ensure their family is protected while they focus on growing your institution.


    Think about the peace of mind you are offering your top officers. You aren't just giving them a salary; you are giving them a legacy. When you align the bank’s financial goals with the personal security of its leaders, you create an environment where talent stays for the long haul.


    Why the "Carrier Agnostic" Approach Matters


    The BOLI market is nuanced. There are different types of products: General Account, Hybrid Account, and Separate Account: each with its own risk profile and yield potential.


    At Schiff Executive Benefits, we believe that your bank deserves a solution tailored to your specific capital structure and risk appetite, not a "product of the month." We operate as independent brokers, which means we work with all the major, highly-rated carriers to find the right fit for you.


    Our process, which we call The Perfect Plan®, involves:


    1. A Deep-Dive Needs Analysis: We look at your current benefit liabilities and capital ratios.

    2. Carrier Evaluation: We vet the financial strength and historical performance of potential insurance partners.

    3. Pro Forma Modeling: We show you exactly how BOLI will impact your EPS and ROA over 10, 20, and 30 years.

    4. Implementation and Administration: We handle the heavy lifting, from board education to ongoing compliance monitoring.

    Overview of Schiff Executive Benefits’ BOLI consulting services


    The Point of No Return: Why Wait?


    Every day that your bank's benefit liabilities grow while your assets remain in taxable, low-yield accounts is a day of lost opportunity. Economic shifts are coming, and the cost of talent is not going down.


    Are you prepared for the next five years? What if your replacement cost for your senior team increases by 20%? What if your 401(k) matches become a burden on your margins?


    BOLI is not just a financial product; it is a strategic shield. It provides a calm, structured way out of the anxiety of rising costs. It allows you to focus on what you do best: banking: while we ensure your "human capital" is fully funded and protected.


    Join Us for a Deeper Conversation


    Navigating the complexities of executive benefits and BOLI doesn't have to be a solo journey. Whether you are looking to implement your first BOLI plan or you want a review of your existing holdings to ensure they are performing as promised, we are here to help.


    Sit back, grab your coffee, and let's discuss how we can bring stability back to your executive suite. Building your bank’s legacy should be a realization of your dream value, not a source of stress.


    Come join us and discover how The Perfect Plan® can help you achieve alignment and retention.


    Ready to explore the possibilities? Learn more about our services here.


    How BOLI Works: The Mechanics


    A BOLI purchase is a reallocation of existing bank assets, not new spending. The bank moves capital from a taxable holding — typically short-duration securities or fed funds — into an insurance contract on the lives of consenting officers.


    1. The bank identifies a legitimate business need, usually the cost of an existing or planned benefit obligation.

    2. It performs and documents a pre-purchase analysis covering need, amount, carrier selection, product characteristics, and risk.

    3. Eligible insureds provide written notice and consent before any policy is issued.

    4. The bank pays a single premium, or a limited series, and records the cash surrender value as an asset.

    5. Cash value accumulates tax-deferred at the credited rate, and the increase is recognized in non-interest income.

    6. At the insured's death, the carrier pays the bank; proceeds above carrying value are generally income-tax-free.


    The reason this works economically is the absence of current tax on the inside build-up. A taxable instrument yielding the same nominal rate is worth materially less after tax. That spread is the entire case for BOLI, and it is why the comparison must always be run against the specific alternative the bank would otherwise hold.


    BOLI Is a Hold-to-Maturity Asset


    Surrendering a policy generally triggers ordinary income on the gain and forfeits the tax-free death benefit — the two features that justified the purchase. BOLI should therefore be underwritten as a permanent allocation. A bank that may need that liquidity inside ten years is not a good candidate, and any presentation that treats cash value as a liquidity source deserves scrutiny.Diverse business team collaborating in a corporate office meeting.

    The Three Account Types


    Product selection drives most of the risk difference between two otherwise identical BOLI programs.


    • General Account — assets sit in the carrier's general account. The carrier declares a credited rate, usually with a guaranteed floor. Simplest to administer, and the bank takes direct credit exposure to the carrier. Suits smaller programs and banks that prefer a declared rate over transparency.

    • Separate Account — assets are held in a segregated account, insulated from the claims of the carrier's general creditors. Returns track the underlying portfolio, so a stable value protection wrapper is generally used to smooth book value. More transparent, more moving parts, and the wrap provider becomes its own counterparty to diligence.

    • Hybrid Account — a general account chassis with some separate-account characteristics, typically better rate transparency than pure general account without the full complexity of a wrapped separate account.

    • Institutional Indexed Universal Life — crediting tied to an index formula subject to caps and floors. Requires the board to understand exactly how the crediting method behaves in a flat or negative index year.


    There is no universally correct answer. The right structure follows from the bank's size, its credit appetite, its comfort with mark-to-market mechanics, and how much administrative capacity it has.


    The Regulatory Framework


    The controlling guidance is the 2004 Interagency Statement on the Purchase and Risk Management of Life Insurance, issued jointly by the federal banking agencies. Two points drive most examination findings.


    Concentration Guidance


    Aggregate cash surrender value of all life insurance holdings is generally expected to remain within 25% of Tier 1 capital, with exposure to any single carrier generally within 15%. These are supervisory guidelines rather than statutory caps — a bank exceeding them is not automatically in violation, but is expected to document why the concentration is prudent and how it is managed. In practice, examiners treat an undocumented excess far more harshly than a well-reasoned one.


    The Pre-Purchase Analysis


    This is where most criticized BOLI programs fail, and the failure is almost always documentation rather than economics. A defensible analysis addresses:


    • The specific business need and the benefit obligation being offset

    • The amount of insurance and how that amount was derived

    • Vendor and carrier selection, including financial strength and the basis for choosing among carriers

    • Product characteristics, including crediting methodology and surrender charges

    • Alternatives considered and why BOLI was preferred

    • The full risk assessment — liquidity, credit, interest rate, operational, compliance, reputation, and price risk

    • Evidence of board or committee review and approval before purchase


    The analysis must exist before the purchase. Reconstructing one after an examiner asks is not the same thing, and examiners can tell the difference.


    Ongoing Risk Management


    Approval at purchase does not end the obligation. Regulators expect periodic review — at minimum annually — covering carrier financial condition, policy performance against expectations, continued compliance with concentration guidance, and confirmation that the original business purpose still holds. Programs that were bought correctly and then left unmonitored for a decade are a recurring examination finding.


    IRC 101(j): Notice and Consent


    BOLI is employer-owned life insurance, so IRC 101(j) applies with full force. Since the Pension Protection Act of 2006, death proceeds are taxable to the bank above premiums paid unless, before the policy is issued, the insured has been notified in writing of the intent to insure and the maximum face amount, has consented in writing to coverage that may continue after employment ends, and has been informed the bank will be a beneficiary.


    The insured must also fall within a qualifying category, which in a banking context generally means directors and highly compensated employees as defined in the Code. The bank files Form 8925 annually with its return.


    Two situations create most of the exposure. The first is acquisition: banks that grow by merger routinely inherit policies without inheriting the consent files. The second is time — programs bought fifteen years ago by people who have since retired, where nobody has verified that the documentation still exists. Both are worth auditing before a claim rather than during one.


    Accounting Treatment


    An investment in life insurance is reported at the amount realizable under the contract at the balance sheet date, which in practice means cash surrender value net of any surrender charge the bank would actually incur. Periodic increases flow through non-interest income. Death proceeds above carrying value are recognized when realizable.


    Two consequences worth raising with your CFO before the first premium: the asset recorded in year one is cash surrender value, not premium paid, and in some product designs those differ meaningfully at the outset. And the carrier's annual statement becomes audit support, so the reporting relationship matters as much as the crediting rate.


    What BOLI Actually Funds


    BOLI is informal financing, not funding. The policy is a general asset of the bank; it is not pledged, segregated, or promised to any participant. Most programs are used to offset:


    • Supplemental Executive Retirement Plan obligations for officers

    • Deferred compensation liabilities, including director deferral plans

    • Split dollar and endorsement arrangements providing survivor income to officers' families

    • General group benefit costs — health, disability, and post-retirement obligations


    Any plan document or officer communication implying the policy secures the benefit creates a constructive receipt problem and undermines the arrangement. The promise and the asset must stay legally separate.


    Where BOLI Programs Go Wrong


    • Missing 101(j) consent — the most expensive failure, and almost always found at claim rather than at purchase.

    • Thin or backdated pre-purchase analysis — the most common examination criticism.

    • Carrier concentration drift — a program that was inside the 15% single-carrier guideline at purchase can breach it as capital changes or as one carrier's block outperforms.

    • Orphaned programs — the originating producer is gone, nobody reviews performance, and the crediting rate has quietly reset.

    • Product mismatch — separate account complexity sold to a bank without the staff to administer it, or a general account placement with a carrier whose financial strength has since deteriorated.


    Our review of the seven compliance mistakes boards make covers these in more detail, and the portfolio-level review addresses existing holdings.Professional business consultants reviewing executive benefit policy documents with a client.

    Frequently Asked Questions About BOLI


    What is BOLI in banking?


    BOLI is life insurance owned by a bank on the lives of its officers and directors, held as a balance sheet asset to offset employee benefit costs. The bank pays the premium, owns the cash value, and receives the death benefit.


    Is BOLI legal for banks?


    Yes. National banks may purchase and hold life insurance under 12 U.S.C. 24 (Seventh) in connection with employee compensation and benefit plans, key person coverage, and related purposes. State-chartered institutions operate under comparable state authority. The purchase must address a legitimate business need.


    How much BOLI can a bank own?


    Supervisory guidance generally expects aggregate cash surrender value within 25% of Tier 1 capital, and within 15% for any single carrier. These are guidelines requiring documented justification if exceeded, not hard statutory ceilings.


    Are BOLI premiums tax deductible?


    No. Premiums on a policy where the bank is a beneficiary are not deductible. The tax advantage sits in the tax-deferred accumulation and the generally tax-free death benefit.


    What happens to BOLI when an insured officer leaves the bank?


    The bank continues to own the policy and typically keeps it in force — which is exactly why the 101(j) consent must disclose that coverage may continue after employment ends. Whether to retain it is an economic question about that policy's performance.


    Can a bank surrender a BOLI policy?


    It can, but surrender generally triggers ordinary income on the gain and forfeits the tax-free death benefit. Surrender charges may also apply in early years. BOLI should be purchased as a permanent allocation, not a liquidity reserve.


    What is the difference between BOLI and COLI?


    The structure is essentially the same; the owner differs. BOLI is bought by a bank and carries an additional layer of federal banking supervision. COLI is bought by an operating company and is governed by the tax rules without that supervisory overlay. Our side-by-side comparison works through the choice.


    What is stable value protection?


    In separate account BOLI, a stable value wrap smooths the reported book value of the underlying portfolio so the bank is not exposed to mark-to-market swings in earnings. The wrap provider is a distinct counterparty and belongs in the pre-purchase credit analysis alongside the carrier.


    How often should a BOLI program be reviewed?


    At least annually, covering carrier financial condition, actual versus expected performance, concentration against current Tier 1 capital, and continued alignment with the original business purpose. Many banks also commission an independent review every few years.


    Can BOLI be restructured without triggering tax?


    A 1035 exchange may permit moving from one contract to another without current recognition, but the analysis is fact-specific and interacts with 101(j) and the transfer-for-value rules. It should never be undertaken on a wholesaler's illustration alone.




They say that comparison is the thief of joy, but in the banking world, comparison is the bedrock of survival.
Whether you are managing a small community bank with ten employees or steering a multi-billion dollar institution, you are constantly looking at the peer group. You look at their ROA, their efficiency ratios, and their net interest margins. You do this not out of envy, but out of a necessity to understand where the market is moving and ensure you aren’t being left behind in the race for stability and talent.


One of the most significant, yet often under-discussed, benchmarks in this comparison is Bank-Owned Life Insurance (BOLI).


If you’ve spent any time in the C-suite, you know that BOLI is no longer a "niche" strategy. It has become a standard tool for high-performing banks to offset the rising costs of employee benefits. But the question remains: Is your bank above or below the BOLI average? And more importantly, if you are an outlier, do you know why?


The State of the Market: By the Numbers


To understand where you stand, we have to look at the cold, hard data. As we move through 2026, the reliance on Bank-Owned Life Insurance has reached a critical mass.


Currently, 67% of all banks in the United States hold BOLI on their balance sheets. It is the majority position. If you don't have it, you are officially in the minority.


But holding it is only half the story. The depth of the investment is where the strategy really reveals itself. Among those who do hold BOLI, 65% have more than 3.5% of their Tier 1 assets committed to these programs. When we look at the heavy hitters: institutions with over $50 billion in assets: the average BOLI holding jumps to 12.8% of regulatory capital.


Why the disparity? Large institutions didn't get large by accident. They realized long ago that "benefit bleed": the slow, steady drain of capital used to fund executive retirements and rising healthcare costs: is a silent killer of shareholder value. They use BOLI as a specialized asset to recover those costs.


Banking Executive Analyzing Data


Why Averages Matter (and Why They Don't)


When a CEO asks me, "Matt, are we holding too much BOLI?" I rarely start with a number. I start with a question about their The Perfect Plan®.


Averages are a great starting point for a conversation, but they are a terrible way to run a business. If your bank is currently holding 2% of Tier 1 assets in BOLI while your peers are at 12%, you aren't "safer": you are likely just less efficient. You are paying for benefits with after-tax dollars while your competitors are using tax-advantaged assets to do the heavy lifting.


However, being "above" the average carries its own set of responsibilities. If you are pushing toward that 25% regulatory capital concentration limit, your documentation, your risk assessment, and your board oversight must be bulletproof.


The Technical Guardrails: OCC 2004-56 and IRC 7702


In this environment, you can’t afford to "wing it." The regulatory landscape for BOLI is defined largely by OCC Bulletin 2004-56. This isn't just a suggestion; it's the rulebook. It requires banks to perform comprehensive pre-purchase analysis and ongoing monitoring.


One of the most critical technical aspects we navigate with our clients is IRC Section 7702. This section of the Internal Revenue Code defines what actually constitutes a "life insurance contract" for federal tax purposes. If your policy doesn’t meet these stringent requirements, you lose the very tax advantages: tax-free inside buildup and tax-free death benefits: that make BOLI attractive in the first place.


At Schiff Executive Benefits, we focus on ensuring that every program we design is compliant not just today, but for the long haul. We reverse engineer the solution based on your specific liabilities, ensuring that the asset matches the intent.


Managing the 6 Key Risks


When the regulators come knocking, they aren't just looking at your earnings. They are looking at your risk management framework. OCC 2004-56 outlines six key risks that every bank must address regarding their BOLI holdings:


  1. Liquidity Risk: BOLI is an illiquid asset. You can't just flip it for cash tomorrow without potential tax penalties and surrender charges. How does this fit into your overall liquidity profile?

  2. Transaction/Operational Risk: This involves the complexity of the program. Is it being administered correctly? Are the death benefits being tracked?

  3. Reputation Risk: What happens if the carrier fails? Or if the public perceives the plan as "excessive"?

  4. Credit Risk: You are essentially making a long-term loan to an insurance carrier. Is that carrier stable? We work as a broker with a wide variety of top-tier carriers to ensure diversification and credit quality.

  5. Interest Rate Risk: BOLI values can fluctuate based on the interest rate environment. Does your board understand the impact of a rising or falling rate environment on your BOLI yield?

  6. Compliance/Legal Risk: From insurable interest laws to the 25% concentration limits, the legal hurdles are high.


Risk and Compliance Balance


Offsetting Benefit Bleed: Matching Assets to Liabilities


The most common "What If" we hear from bank presidents is: "What if our top talent leaves for the competitor down the street?"


In the current war for talent, standard 401(k) plans often fall short for high-earning executives due to IRS contribution limits. This is where we implement specialized tools like the 401k Mirror Plan.


But here is the catch: creating a promise (a liability) to pay an executive a SERP (Supplemental Executive Retirement Plan) or a Mirror Plan benefit in 15 years is easy. Funding it is the hard part. If you don't have an asset earmarked to grow alongside that liability, you are creating a massive hole in your future balance sheet.


By utilizing BOLI, we can match the asset to the future liability. When the executive retires, the cash value of the BOLI can provide the cash flow to pay the benefit. If the executive passes away prematurely, the death benefit protects the bank and the executive's family. It’s about restoring alignment and retention.


The Schiff Approach: Reverse Engineering Your Success


We don't believe in "off-the-shelf" products. Our team has almost 100 years of combined experience in technical benefit design. We don’t start with a BOLI policy; we start with your goals.


We ask the tough questions:


  • What is the cost of your current benefit "bleed"?

  • How much of your capital is working for you versus sitting in low-yield traditional assets?

  • Are your top three executives truly tied to the long-term success of the bank?


Once we have those answers, we "reverse engineer" a solution that fits your culture. We call this The Perfect Plan®. It’s a process that ensures your benefits are a bridge to your goals, not a weight on your earnings.


Strategic Growth and Data


Where Do You Go From Here?


If you find that your bank is below the average, don't panic. It’s an opportunity. It means you have "eligible purchase capacity": dry powder that can be deployed to increase your ROA and secure your key people.


If you are above the average, it's time for a check-up. Are you managing those six key risks? Is your documentation up to the standards of the latest OCC exams?


Regardless of where you sit on the curve, the goal is the same: realizing your dream value and building it your way. Don't let your executive benefits be an afterthought.


If you want to see exactly how your bank stacks up against a specific peer group: not just national averages, but the banks in your own backyard: let’s talk. Sit back, grab your coffee, and come join us for a deeper dive into the technical side of retention.


Your legacy is too important to leave to chance. Let's make sure you have The Perfect Plan® in place and help your bank maximize your BOLI Portfolio. Our Proprietary BOLI Model can give you a peer analysis and projected earnings analysis in seconds. Give us a call at 610-292-9330 or email us at info@schiffbenefits.com for your bank's copy.  We're here to help, and have the expertise to work with ANY carrier.


Financial Legacy and Precision


Learn more: our complete guide to Bank Owned Life Insurance (BOLI).


The Benchmark Trap: Why Peer Averages Mislead


Benchmarking is a starting point, not a verdict. A peer average tells you what banks of roughly your size are doing; it tells you nothing about whether any of them did it well, or whether their circumstances resemble yours.


Two banks holding identical BOLI as a percentage of Tier 1 capital can be in completely different positions. One bought general account coverage from a highly rated carrier at a favorable crediting rate and has reviewed it annually since. The other holds a decade-old placement from a carrier that has since been downgraded, at a rate that quietly reset, with no documented review. The benchmark treats them as peers. An examiner will not.


Matching the average is therefore the wrong objective. The right question is whether your holding is sized to a real obligation, placed with carriers you would underwrite today, and structured so the economics still work under conservative assumptions.


BOLI vs. Traditional Fixed Income


The comparison that matters is against the specific asset the bank would otherwise hold for the same duration — not against an abstract benchmark.


  • Tax treatment. Interest on taxable securities is recognized currently. BOLI cash value accumulates without current tax, and death proceeds are generally received income-tax-free when IRC 101(j) is satisfied. On identical nominal yields, the after-tax outcomes diverge substantially over a long holding period.

  • Duration and liquidity. A bond portfolio can be sold. BOLI cannot be exited without surrendering the tax advantages that justified it. This is the central tradeoff, and it should be decided on the bank's actual liquidity profile rather than on a yield comparison alone.

  • Credit exposure. Fixed income carries issuer risk you can diversify at will. General account BOLI concentrates exposure in a small number of carriers, which is precisely why the 15% single-carrier guidance exists.

  • Earnings presentation. BOLI increases flow through non-interest income rather than interest income, which changes how the contribution appears in your margin analysis.


None of this makes BOLI categorically better or worse. It makes it a different instrument with a different risk profile, appropriate for capital the bank can genuinely commit for the long term.


The Governance Questions Your Board Should Be Asking


Whether you hold BOLI already or are evaluating a first purchase, these are the questions that separate a defensible program from one that draws criticism:


  • What specific benefit obligation does this holding offset, and how was the amount derived?

  • Where does aggregate cash surrender value sit against current Tier 1 capital, and against each individual carrier?

  • When was carrier financial strength last reviewed, and by whom?

  • Is actual crediting performance tracking what was illustrated at purchase?

  • Does 101(j) notice and consent documentation exist for every insured, including those inherited through acquisition?

  • Does the pre-purchase analysis exist in writing, dated before the purchase?

  • If the original business purpose has changed, does the holding still make sense?


A board that can answer all seven is in good shape. A board that cannot answer the last three has an examination problem waiting to surface, regardless of how the yield looks.


From Benchmark to Strategy


The point of measuring against peers is to prompt the harder question underneath: is this program built around your bank's obligations, or was it sized to look normal? Benchmarks describe the market. Strategy is what you do with your own balance sheet.


For the full technical treatment of how these programs are structured and regulated, see our complete guide to Bank-Owned Life Insurance. If you already hold BOLI, the seven compliance mistakes boards make is the faster diagnostic.


"The best time to plant a tree was twenty years ago. The second best time is now."


It’s an old aphorism, but in the world of executive benefits and bank regulation, it’s a universal truth that separates the thriving organizations from the ones just waiting for an audit to go sideways.


Welcome to the Friday Wrap. Pull up a chair, grab your coffee (black, if you’re doing it right), and let’s look at what we’ve tackled this week. We’ve been moving fast, focusing on two heavy hitters that define whether a company is truly aligned or just coasting on hope. We’re talking about the technical minefield of BOLI compliance and the strategic elegance of the Non-Qualified Deferred Compensation (NQDC) plan: otherwise known as the "401(k) Mirror."


At Schiff Executive Benefits, our mission is simple: Restoring Alignment and Retention. We spend our days reverse-engineering solutions to ensure that when you look at your top talent, you aren't asking yourself, "What if they leave?" Instead, you’re confident that they have every reason to stay. That is the core of The Perfect Plan®.


Section 1: The BOLI Compliance Minefield


First up, we dove deep into the world of Bank-Owned Life Insurance. Now, BOLI is a fantastic tool: it’s a way for banks to offset the rising costs of employee benefits using a tax-advantaged asset. But here is the problem: many boards treat BOLI like a "set it and forget it" crockpot.


Bad idea.


complianceImage


If you aren't staying on top of your BOLI compliance, you aren't just risking a slap on the wrist; you’re risking the "safety and soundness" rating of your entire institution. We discussed the 7 common mistakes boards make, and if any of these sound familiar, it’s time for a check-up:


  1. The 25% Tier 1 Capital Guideline: You can’t just buy BOLI until your heart's content. Regulatory guidance (specifically OCC 2004-56) suggests that a bank’s total BOLI holdings should generally not exceed 25% of its Tier 1 Capital. Are you pushing that limit?

  2. The 1% Concentration Rule: While not always a hard regulatory floor, many conservative boards set a limit that no single insurance carrier should represent more than 1% of the bank's total assets. Diversification isn't just for your personal portfolio; it’s for your balance sheet protection.

  3. The IRC 101(j) Gotcha: This is the big one. If you don’t get written, informed consent from the employee before the policy is issued, the death benefit: which is supposed to be tax-free: becomes taxable. That is a massive, preventable unforced error.

  4. Lack of Annual Board Review: The regulators want to see that the board is actually looking at the performance and risk of the BOLI asset every single year.

  5. Credit Analysis Neglect: When was the last time you did a deep dive into the creditworthiness of the carriers holding your BOLI?

  6. Ignoring Mortality Performance: Are you tracking how the actual mortality experience matches up against the projections you were sold?

  7. Failing the Peer Analysis: Regulators love to see how you stack up against your peers. If you aren't doing a peer analysis of your BOLI holdings, you’re flying blind.


BOLI is a powerful component of The Perfect Plan®, but only if it’s managed with the precision it deserves.


Section 2: Breaking the "Success Ceiling" with the 401(k) Mirror


Next, we shifted gears to look at how corporate entities (and banks, too) handle their most expensive and valuable asset: their people.


Have you ever noticed that the more successful your executives become, the more the government penalizes them? It’s called the "Success Ceiling."


successCeiling


In a traditional 401(k), there is a hard limit on what an employee can defer. For high-earning executives, that limit often represents a tiny fraction of their total income: sometimes as low as 2% or 3%. While the rest of your staff can defer 10% or 15% toward their future, your top leaders are hitting a wall.


That’s where the NQDC 401(k) Mirror Plan comes in.


By creating a "Mirror" plan, you allow your key talent to defer significantly more of their compensation: often up to 80% of salary and 100% of bonuses: on a tax-deferred basis. It "mirrors" the 401(k) experience they already know: they choose their investments, they see their statements, and they watch their money grow.


Section 3: The Power of Golden Handcuffs


Why does this matter to you as a business owner or a board member? Because it solves one of the most critical of the "5 What Ifs": What if your top talent leaves?


goldenHandcuffs


When you implement a Mirror Plan, you aren't just giving them a place to save; you’re creating "Golden Handcuffs." By structuring employer contributions with specific vesting schedules or "tail" payouts, you create a powerful incentive for your executives to stay for the long haul.


Imagine an executive who has $500,000 or $1,000,000 in a deferred comp account that they only get if they stay for another five years. That makes the recruiter’s phone call a lot less tempting.


This is the essence of The Perfect Plan®. It’s about building a structure where the company’s goals and the executive’s personal financial goals are perfectly aligned. When they win, you win. When they stay, the company grows.


Section 4: Strategy Over Product


At Schiff Executive Benefits, we aren't just selling insurance or setting up plans. We’re reverse-engineering your goals. Whether it's ensuring your BOLI is compliant so you don't get a "Matter Requiring Attention" from the OCC, or designing a Mirror Plan that keeps your CEO from jumping ship to a competitor, we start with the intent.


strategyImage


Does your current benefit structure match your company culture? Does it actually protect you from the "What Ifs"?


If you're not sure, it might be time to take a look at how we build The Perfect Plan®. We work alongside your existing team: your accountants, your attorneys, and your TPA: to ensure that every piece of the puzzle fits perfectly.


Wrapping Up the Week


It’s been a productive week, but there is always more work to be done in the pursuit of alignment.


If any of this resonated with you: if you’re worried about your BOLI concentration limits or if you realize your top talent is hitting a ceiling they can’t break through: let’s talk.


You can check out our full range of services on our Posts page or, better yet, come join the conversation over on The Perfect Plan® Podcast YouTube channel. We’re constantly dropping new insights to help you navigate these technical waters.


Have a great weekend. Rest up, stay focused, and remember: alignment isn't an accident. It’s a choice.


Warmly,


Matt Schiff
President, Schiff Executive Benefits


Schiff Executive Benefits helps businesses attract, retain, and reward key talent through goal-oriented reverse engineering and deep technical expertise. Visit us at schiffbenefits.com to learn more.


Note: This post is scheduled to publish on Friday, May 15, 2026, at 7:00 AM ET.


Learn more: our complete guide to Bank Owned Life Insurance (BOLI) and how a 401(k) Mirror Plan works.