In the high-stakes world of community and regional banking, the pursuit of yield is never just about the numbers on a spreadsheet; it is a delicate dance between regulatory capital constraints and the mandate for long-term stability. Every CFO knows the universal truth: you cannot manage what you cannot predict. When it comes to Bank Owned Life Insurance (BOLI), that predictability has historically been bifurcated. You either chose the safety and simplicity of a General Account (GA) structure or the transparency and potential of a Separate Account (SA) structure.
But the financial landscape is rarely that binary. For banks that demand the creditor insulation of a separate account without the stomach-turning volatility of mark-to-market accounting, there is a third way.
Hybrid Account Universal Life BOLI is the "best of both worlds" solution that has quietly become the preferred tool for sophisticated bank boards. It is a strategic middle ground: a product that reverse-engineers the best parts of insurance mechanics to serve the specific needs of a bank’s balance sheet.
The Structural "Sweet Spot": How Hybrid BOLI Works
To understand the value of a Hybrid Account, you first have to understand the tension it resolves.
Historically, General Account BOLI was the standard. The bank paid a premium, and those assets became part of the insurance carrier’s general investment pool. The carrier guaranteed a minimum crediting rate, and the bank enjoyed book-value accounting. The downside? The bank was essentially an unsecured creditor of the insurance company. If the carrier faltered, so did the bank’s asset.
On the other hand, Separate Account BOLI offered transparency and legal insulation. The assets were held in a separate account, away from the carrier’s general creditors. However, this often introduced "mark-to-market" volatility. Unless the bank paid for an expensive Stable Value Protection (SVP) wrap, the fluctuation in the underlying investment portfolio would flow directly through the bank’s P&L.
Hybrid Account BOLI changes the math.
In a Hybrid structure, part of the assets sit in a legally insulated separate account. This provides the bank with the transparency it desires and the creditor protection it needs. However: and this is the "magic" of the hybrid design: the carrier provides a contractually guaranteed minimum crediting rate, much like a General Account product.
Because the carrier is providing the "floor," there is no need for a Stable Value Protection wrap. The carrier contractually guarantees the book-value accounting, meaning the bank does not face direct market value exposure. You get the transparency and insulation of a separate account with the smoothed, predictable income of a general account.
Why It Matters: Yield Enhancement Without the Volatility
For a bank’s investment committee, the appeal of Hybrid BOLI usually centers on two portfolios: Yield and Yield Plus.
Unlike traditional General Account BOLI, where the bank has no say in how the assets are deployed, Hybrid Account products often allow the bank to benefit from multiple portfolio options. These portfolios are managed with an eye toward high-grade corporate bonds and other bank-eligible investments, but they are structured to allow for slightly higher yield targets than a standard GA product might offer.
Because these are Universal Life chassis, the crediting rate is declared by the carrier based on the performance of these underlying portfolios. However, since the carrier guarantees the floor, the bank doesn't have to worry about a "bad month" in the bond market hitting their quarterly earnings report.
At Schiff Executive Benefits, we specialize in this kind of goal-oriented reverse engineering. We don't just look at the carrier; we look at the intent. If your goal is to fund an Executive NQDC plan or offset the rising costs of employee benefits, the Hybrid structure offers a unique way to match those long-term liabilities with a stable, high-performing asset.
The Regulatory Reality: Accounting and Risk Weighting
From a technical perspective, Hybrid Account BOLI is a masterclass in balance sheet efficiency.
Book-Value Accounting
The primary concern for most bank CFOs is the impact on the P&L. Because Hybrid BOLI uses a crediting-rate approach backed by the carrier’s guarantee, it qualifies for book-value accounting. The bank records the Cash Surrender Value (CSV) as an "Other Asset." The growth in that CSV (the net of the crediting rate minus charges) is recognized as noninterest income. This provides a clean, predictable line item that bank analysts and regulators appreciate.
Risk Weighting
The risk weighting of BOLI is a critical component of Tier 1 Capital management. Under current regulatory frameworks (including Basel III), the risk weighting of Hybrid BOLI typically depends on its composition. While General Account BOLI is usually 100% risk-weighted (corporate-style), and Separate Account BOLI can sometimes be "looked through" to the underlying government-grade assets for a lower weight, Hybrid BOLI is often treated as a blend.
However, many institutions find that the "100% risk weight" trade-off is more than worth it when you consider the lower cost of capital compared to the volatility of a non-wrapped Separate Account.
Carrier Spotlight: The NYLIAC BOLI 50
One of the most prominent examples of this technology in action is the NYLIAC BOLI 50 from New York Life. As a Hybrid Account Universal Life product, it has become a staple for banks looking for a high-quality carrier with a "AAA" pedigree.
The BOLI 50 allows banks to access the Yield and Yield Plus portfolios while maintaining that crucial book-value treatment. It’s designed for the bank that wants a household name carrier but doesn't want to settle for the lower "current" rates of a standard general account.
The "What If" Factor: Planning for the Long Term
At Schiff Executive Benefits, we don't just sell products; we solve for the "What Ifs." When we sit down with a bank board, we aren't just talking about Hybrid BOLI; we are talking about:
Top talent leaving – How does this asset fund the retention package to keep your CEO?
Senior exec retirement – Can we offset the replacement cost effectively?
Running out of retirement money – How do we ensure the plan stays solvent for decades?
Our President, Matt Schiff, brings a unique level of authority to these conversations. He didn't just study the laws; he was in the room when they were written. As a member of the AALU's NQDC Committee, Matt provided technical input on the very regulations (IRC 409A and IRC 101(j)) that govern how these plans must be structured today.
When you work with us, you are getting an architect who understands the "code" of the IRS, not just a contractor who knows how to swing a hammer. We ensure your program is fully compliant with the latest regulations, ensuring that your BOLI remains a tax-advantaged powerhouse rather than a compliance liability.
Restoring Alignment and Retention
Ultimately, Hybrid Account BOLI is a tool for alignment. It aligns the bank's need for stability with the executive's need for a robust benefit structure. It is a key component of The Perfect Plan®, our proprietary approach to ensuring that every dollar on the balance sheet is working toward a specific cultural and financial goal.
If you are a bank decision-maker looking to optimize your BOLI portfolio or replace an underperforming General Account plan, the time to look at Hybrid options is now.
Ready to see how Hybrid BOLI fits your balance sheet?
Sit back, grab your coffee, and let’s look at the numbers. We invite you to join us for a consultative deep dive into your current benefits structure.
Discover your bank's true value: Use our RISR Business Valuation Tool to see how your executive benefits align with your overall growth.
In the world of institutional finance, transparency is the bedrock of trust. For many community and regional banks, Bank-Owned Life Insurance (BOLI) has long been a foundational asset, providing a tax-advantaged vehicle to offset employee benefit liabilities. However, as institutions grow in complexity and assets, the "General Account" model: where the bank’s capital is comingled with the insurer's general creditors: can sometimes feel like a black box.
For sophisticated bank decision-makers and ALM (Asset Liability Management) teams, the shift toward Separate Account Universal Life BOLI represents a move from passive participation to strategic control. It is a structure designed for those who demand clarity on where their dollars are invested, how they are protected, and how they can be optimized for long-term yield.
At Schiff Executive Benefits, we specialize in reverse-engineering these sophisticated benefit structures to ensure they align perfectly with your bank's culture and financial goals. Our mission is centered on Restoring Alignment and Retention.
The Architecture of Insulation: Legally Segregated Accounts
The defining characteristic of Separate Account BOLI is the legal "moat" it builds around your assets. Unlike General Account BOLI, where the bank is effectively a general creditor of the insurance company, Separate Account premiums are held in a legally segregated account.
Under OCC Bulletin 2004-56, the regulatory framework is clear: these assets are insulated from the claims of the insurer's general creditors in the event of insolvency. For a bank's risk committee, this provides a layer of counterparty risk mitigation that is simply unavailable in traditional products. You aren't just buying a policy; you are securing a dedicated asset pool.
Transparency and Investment Control through IRC 817(h)
One of the primary frustrations with traditional BOLI is the lack of visibility into the underlying portfolio. Separate Account BOLI flips this script. By utilizing third-party investment managers, banks can achieve a level of transparency that rivals their own investment portfolios.
However, this control comes with strict regulatory guardrails. To maintain the tax-advantaged status of the life insurance contract, the account must comply with IRC §817(h) diversification requirements. This ensures that the policy remains treated as insurance rather than a taxable investment.
Furthermore, "Investor Control" rules stipulate that while the bank can choose from a menu of sophisticated investment strategies managed by professional firms, they cannot direct individual security trades. This is where our expertise at Schiff Executive Benefits becomes invaluable. We help you navigate these nuances, ensuring your BOLI program remains compliant while pursuing the yield your institution requires.
Managing Volatility: The SVP "Wrap" and Book-Value Accounting
If Separate Account BOLI offers better transparency and yield potential, why doesn't every bank use it? The answer often lies in the accounting treatment.
By default, Separate Account assets are subject to mark-to-market accounting. For a bank’s P&L, the daily fluctuations of the underlying bond or equity markets can create unwanted volatility. This is where the Stable Value Protection (SVP) wrap comes into play.
An SVP wrap is a contract: often provided by a highly-rated financial institution or the insurer themselves: that allows the bank to report the asset at "book value" rather than fair market value. This "wraps" the volatility, amortizing gains and losses over time to provide a steady, predictable crediting rate. For banks with sophisticated ALM teams, the ability to harvest the "equity risk premium" or higher-duration yields without the immediate P&L sting is a game-changer.
Capital Efficiency: The Look-Through Advantage
From a regulatory capital perspective, Separate Account BOLI offers a distinct advantage over its General Account counterparts. Under the "look-through" approach, banks can risk-weight the BOLI asset based on the underlying securities within the separate account.
While General Account BOLI is typically risk-weighted at 100% (or 20% if the insurer is highly rated, though this is increasingly rare), Separate Account portfolios focused on high-quality government or agency bonds can often achieve a risk-weighting as low as 20%. This makes Separate Account BOLI an incredibly capital-efficient tool for larger regional or commercial banks looking to optimize their Tier 1 capital ratios.
Why Technical Expertise Matters: The Schiff Legacy
Navigating the intersection of life insurance, tax law, and bank regulation requires more than just a broker; it requires an architect. Matt Schiff, President of Schiff Executive Benefits, brings a unique level of authority to this space. Having served as a member of the AALU's NQDC Committee, Matt provided technical input on the very laws: like IRC 409A and 101(j): that govern these plans today.
When you work with us, you are working with a team that was "in the room where it happened." We don't just follow the rules; we understand the intent behind them. This technical depth is why we emphasize an integrated approach, working alongside your existing accountants, attorneys, and TPAs to ensure The Perfect Plan® is not just a concept, but a compliant reality.
Is Separate Account BOLI Right for Your Bank?
This structure is ideal for institutions that meet several criteria:
Asset Size: Generally, banks with $1 billion or more in assets find the administrative and wrap costs of Separate Accounts more justifiable.
ALM Sophistication: Banks with dedicated teams capable of monitoring third-party managers and understanding SVP dynamics.
Yield Requirements: Institutions looking to outperform the "standard" General Account rates by taking a longer-term, more transparent investment view.
Capital Constraints: Banks looking for higher risk-adjusted returns on capital.
Your Path to a More Sophisticated BOLI Strategy
The decision to transition to or implement a Separate Account structure shouldn't be made in a vacuum. It requires a deep dive into your bank’s specific "What If's": from top talent retention to the long-term cost recovery of executive benefits.
We invite you to explore our BOLI process to see how we reverse-engineer solutions based on your specific goals. If you are ready to evaluate your bank's current valuation and potential for a more sophisticated retention tool, we encourage you to use our Business Valuation and Prospect Data Capture tool.
At Schiff Executive Benefits, we don't just sell insurance; we build the structures that protect your bank's most valuable asset: its people. Come join us, grab a coffee, and let's discuss how we can bring transparency and stability to your balance sheet.
SEO Pre-flight Check:
Meta Description: Explore the benefits of Separate Account Universal Life BOLI for banks. Learn about OCC 2004-56 compliance, IRC 817(h) diversification, and the capital efficiency of the look-through approach.
Alt Text: All images include descriptive alt text with target keywords like BOLI, Separate Account, and bank executives.
Keywords: Primary keyword "Separate Account Universal Life BOLI" included in H1, intro, and H2 headers.
Internal Links: Links provided to the main BOLI page and the BOLI process page.
In the world of community banking, certainty is the ultimate currency. We often tell our clients that while the markets might be a rollercoaster, your balance sheet shouldn't be. When you are looking to offset the rising costs of executive benefits or simply looking for a stable way to deploy excess liquidity, the conversation inevitably turns to Bank Owned Life Insurance (BOLI).
Among the various structures available, General Account Universal Life BOLI remains the bedrock of the industry. It is the most common, the most straightforward, and for many institutions, the most appropriate tool for the job. But as with any sophisticated financial instrument, the "simple" option still requires a deep dive into the mechanics, the risks, and the regulatory expectations.
At Schiff Executive Benefits, we don’t just broker these plans; we reverse-engineer them. We look at your culture, your "What Ifs," and your long-term goals to ensure that the plan you implement today is the one that still makes sense twenty years from now.
What is General Account BOLI?
At its core, a General Account BOLI policy is a contract between the bank and an insurance carrier. The bank pays a premium, and those funds are pooled into the insurer’s general account. This general account is typically a massive, conservatively managed portfolio of high-quality bonds, mortgages, and real estate.
Unlike Separate Account BOLI, where the bank’s assets are segregated and the bank chooses the investment managers, General Account BOLI relies on the carrier’s overall investment performance.
The Mechanism of Stability
When you opt for a General Account structure, you are essentially trading control for a guarantee. The carrier provides a guaranteed minimum crediting rate. Even if the market takes a dive, your cash value won't drop below a certain floor.
For a community bank, the primary appeal is the lack of "mark-to-market" volatility. Because the carrier assumes the investment risk, the bank does not have to report fluctuations in the underlying bond portfolio on its P&L. Instead, you see predictable, tax-advantaged growth in the cash surrender value (CSV) of the policies.
The Trade-Off: Transparency vs. Security
No financial strategy is without its hurdles. While the stability of General Account BOLI is its greatest strength, it comes with two primary trade-offs:
Lack of Transparency: Since your premiums are pooled with the carrier's other assets, you don't have a window into exactly which bonds or properties are backing your policy. You are trusting the carrier’s investment committee and their historical track record.
Credit Risk: This is the big one. In a General Account structure, the bank is a general creditor of the insurance company. If the carrier runs into financial trouble, your BOLI assets are at risk. This is why we place such a heavy emphasis on carrier selection. We look at A.M. Best, Moody’s, and S&P ratings with a skeptical eye, ensuring the carriers we recommend have the "staying power" to fulfill their long-term promises.
Regulatory Landscape: OCC 2004-56 Compliance
If you’ve spent any time in a boardroom, you know that regulators don't just care about what you buy; they care about how you bought it. OCC 2004-56 (the Interagency Statement on the Purchase and Risk Management of Life Insurance) is the "bible" for BOLI compliance.
General Account BOLI is treated as a complex asset. Regulators expect you to perform a rigorous pre-purchase analysis that includes:
Business Purpose: You must document exactly why you are buying BOLI. Usually, this is to fund specific executive benefit obligations like a Non-Qualified Deferred Compensation (NQDC) plan or a SERP.
Risk Assessment: You need to quantify the liquidity, credit, and interest rate risks.
Concentration Limits: You can't put all your eggs in one carrier's basket.
Board Approval: Your board needs to understand the "What Ifs." What if the carrier is downgraded? What if the crediting rate drops to the minimum?
Under current regulatory capital rules, General Account BOLI is typically risk-weighted at 100%. While this is higher than the 20% weighting often found in Separate Account structures, many banks find the trade-off for P&L stability to be well worth the capital charge.
Why Community Banks Prefer the General Account
Why is this the "simplest and most common" structure? Because most community banks aren't in the business of managing insurance investment portfolios. They want a "set it and forget it" solution: though we prefer the term "set it and monitor it."
General Account BOLI provides:
Predictable Non-Interest Income: The steady crediting rate helps smooth out earnings.
Cost Offset: It is a highly efficient way to recover the costs of the benefits needed to attract and retain top talent.
Simplicity: There is no need for complex daily accounting of underlying securities.
The Schiff Perspective: "In the Room Where it Happened"
When you work with Schiff Executive Benefits, you aren't just getting a broker; you’re getting a partner with deep technical roots. Our President, Matt Schiff, didn't just study these laws: he was a member of the AALU's NQDC Committee and worked alongside Michael Goldstein to provide technical input on the very regulations that govern these plans today (IRC 409A and IRC 101(j)).
We understand the nuances of IRC 101(j) notice and consent requirements. If you miss a signature or a filing date, your tax-free death benefit could become taxable. That’s a "What If" no bank wants to face. We ensure your program is bulletproof from day one.
You can hear more about these technical nuances and our approach to The Perfect Plan® on our YouTube channel, where we break down the complexities of executive benefits into actionable insights.
Is Your BOLI Aligned?
General Account Universal Life BOLI is an incredible tool for restoring alignment and retention within your leadership team. It protects the bank's bottom line while providing the "Perfect Plan®" for your executives' future.
However, the "set it and forget it" mentality can be dangerous. As interest rates shift and carrier credit profiles evolve, your BOLI portfolio needs regular check-ups. Are you still compliant with OCC 2004-56? Is your 101(j) paperwork in order? Are you maximizing your risk-adjusted return?
If you are ready to take a closer look at your current BOLI strategy or are considering a new purchase, let's have a conversation. We can help you navigate our BOLI Process and ensure your Bank Owned Life Insurance program is performing exactly as intended.
Sit back, grab your coffee, and let’s build something that lasts.
To get a clearer picture of your bank’s current valuation and how an executive benefit strategy can impact your bottom line, we invite you to use our RISR application. It’s a simple way to start the journey toward a more secure and aligned future.
SEO Pre-flight Check:
Meta Description: Discover why General Account Universal Life BOLI is the preferred choice for community banks seeking stability, tax-advantaged growth, and OCC 2004-56 compliance.
Alt Text: All images include descriptive alt text with keywords like BOLI, General Account BOLI, and Bank Owned Life Insurance.
Keyword Placement: "General Account BOLI" and "Bank Owned Life Insurance" appear in H1, H2s, and throughout the text.
Internal Links: Links provided to /our-boli-process, /boli-bank-owned-life-insurance, and the Perfect Plan® YouTube channel.
Change is constant. Process matters. If you're evaluating bank owned life insurance, you need a framework that is clear, compliant, and easy for leadership to follow. Our BOLI process is designed to help banks move from early evaluation to confident implementation without unnecessary complexity. At Schiff Executive Benefits, we make BOLI implementation easier to understand, easier to present, and easier to manage.
Why This Process Matters
A successful BOLI process helps your bank:
Offset employee benefit costs
Support executive benefit liabilities
Stay aligned with risk and capital considerations
Give the board a clean path to informed decision-making
Foundation: OCC 2004-56
Every sound BOLI implementation starts with OCC 2004-56. This guidance sets the standard for how banks evaluate risk, document their analysis, and approach bank owned life insurance as a safe and sound asset. We treat OCC 2004-56 as the starting point, not the finish line. That keeps the entire BOLI process focused, defensible, and board-ready.
The 10-Step BOLI Process
Our pre-purchase analysis is built to help bank leadership evaluate structure, risk, pricing, and fit before moving forward.
1. Calculate Employee Benefit Liabilities
Define the benefit costs the BOLI program is meant to offset.
2. Conduct OCC Testing
Measure capital impact, earnings alignment, and insurance-to-capital positioning.
3. Analyze Insurable Interest
Confirm legal eligibility and proper insurable interest for covered lives.
Run independent projections for yield, surrender outcomes, and cost recovery.
6. Review Carrier Investment Strategy
Assess how the carrier invests and whether that approach fits your bank.
7. Review Policy Characteristics
Compare General Account, Separate Account, and Hybrid Account options.
8. Reverse-Engineer the Product
Build the design around your bank’s goals instead of forcing a shelf product.
9. Negotiate Final Pricing
Work to improve net yield, pricing, and overall policy economics.
10. Support Board Review
Deliver a concise executive summary and due diligence package for approval.
Implementation and Ongoing Support
Approval is not the end of the BOLI process. It is the beginning of proper execution. We support the full BOLI implementation phase, including documentation, employee consent, policy placement, and delivery. After purchase, we continue with annual reviews, carrier monitoring, and updated analysis so your bank owned life insurance strategy stays aligned with the original goal. We also work alongside your existing advisors, including accountants, attorneys, and TPAs, so the process stays coordinated and efficient.
Meta Description: Our BOLI process helps banks streamline BOLI implementation with clear steps, OCC 2004-56 alignment, and practical bank owned life insurance guidance.
They say that comparison is the thief of joy, but in the banking world, comparison is the bedrock of survival. Whether you are managing a small community bank with ten employees or steering a multi-billion dollar institution, you are constantly looking at the peer group. You look at their ROA, their efficiency ratios, and their net interest margins. You do this not out of envy, but out of a necessity to understand where the market is moving and ensure you aren’t being left behind in the race for stability and talent.
One of the most significant, yet often under-discussed, benchmarks in this comparison is Bank-Owned Life Insurance (BOLI).
If you’ve spent any time in the C-suite, you know that BOLI is no longer a "niche" strategy. It has become a standard tool for high-performing banks to offset the rising costs of employee benefits. But the question remains: Is your bank above or below the BOLI average? And more importantly, if you are an outlier, do you know why?
The State of the Market: By the Numbers
To understand where you stand, we have to look at the cold, hard data. As we move through 2026, the reliance on Bank-Owned Life Insurance has reached a critical mass.
Currently, 67% of all banks in the United States hold BOLI on their balance sheets. It is the majority position. If you don't have it, you are officially in the minority.
But holding it is only half the story. The depth of the investment is where the strategy really reveals itself. Among those who do hold BOLI, 65% have more than 3.5% of their Tier 1 assets committed to these programs. When we look at the heavy hitters: institutions with over $50 billion in assets: the average BOLI holding jumps to 12.8% of regulatory capital.
Why the disparity? Large institutions didn't get large by accident. They realized long ago that "benefit bleed": the slow, steady drain of capital used to fund executive retirements and rising healthcare costs: is a silent killer of shareholder value. They use BOLI as a specialized asset to recover those costs.
Why Averages Matter (and Why They Don't)
When a CEO asks me, "Matt, are we holding too much BOLI?" I rarely start with a number. I start with a question about their The Perfect Plan®.
Averages are a great starting point for a conversation, but they are a terrible way to run a business. If your bank is currently holding 2% of Tier 1 assets in BOLI while your peers are at 12%, you aren't "safer": you are likely just less efficient. You are paying for benefits with after-tax dollars while your competitors are using tax-advantaged assets to do the heavy lifting.
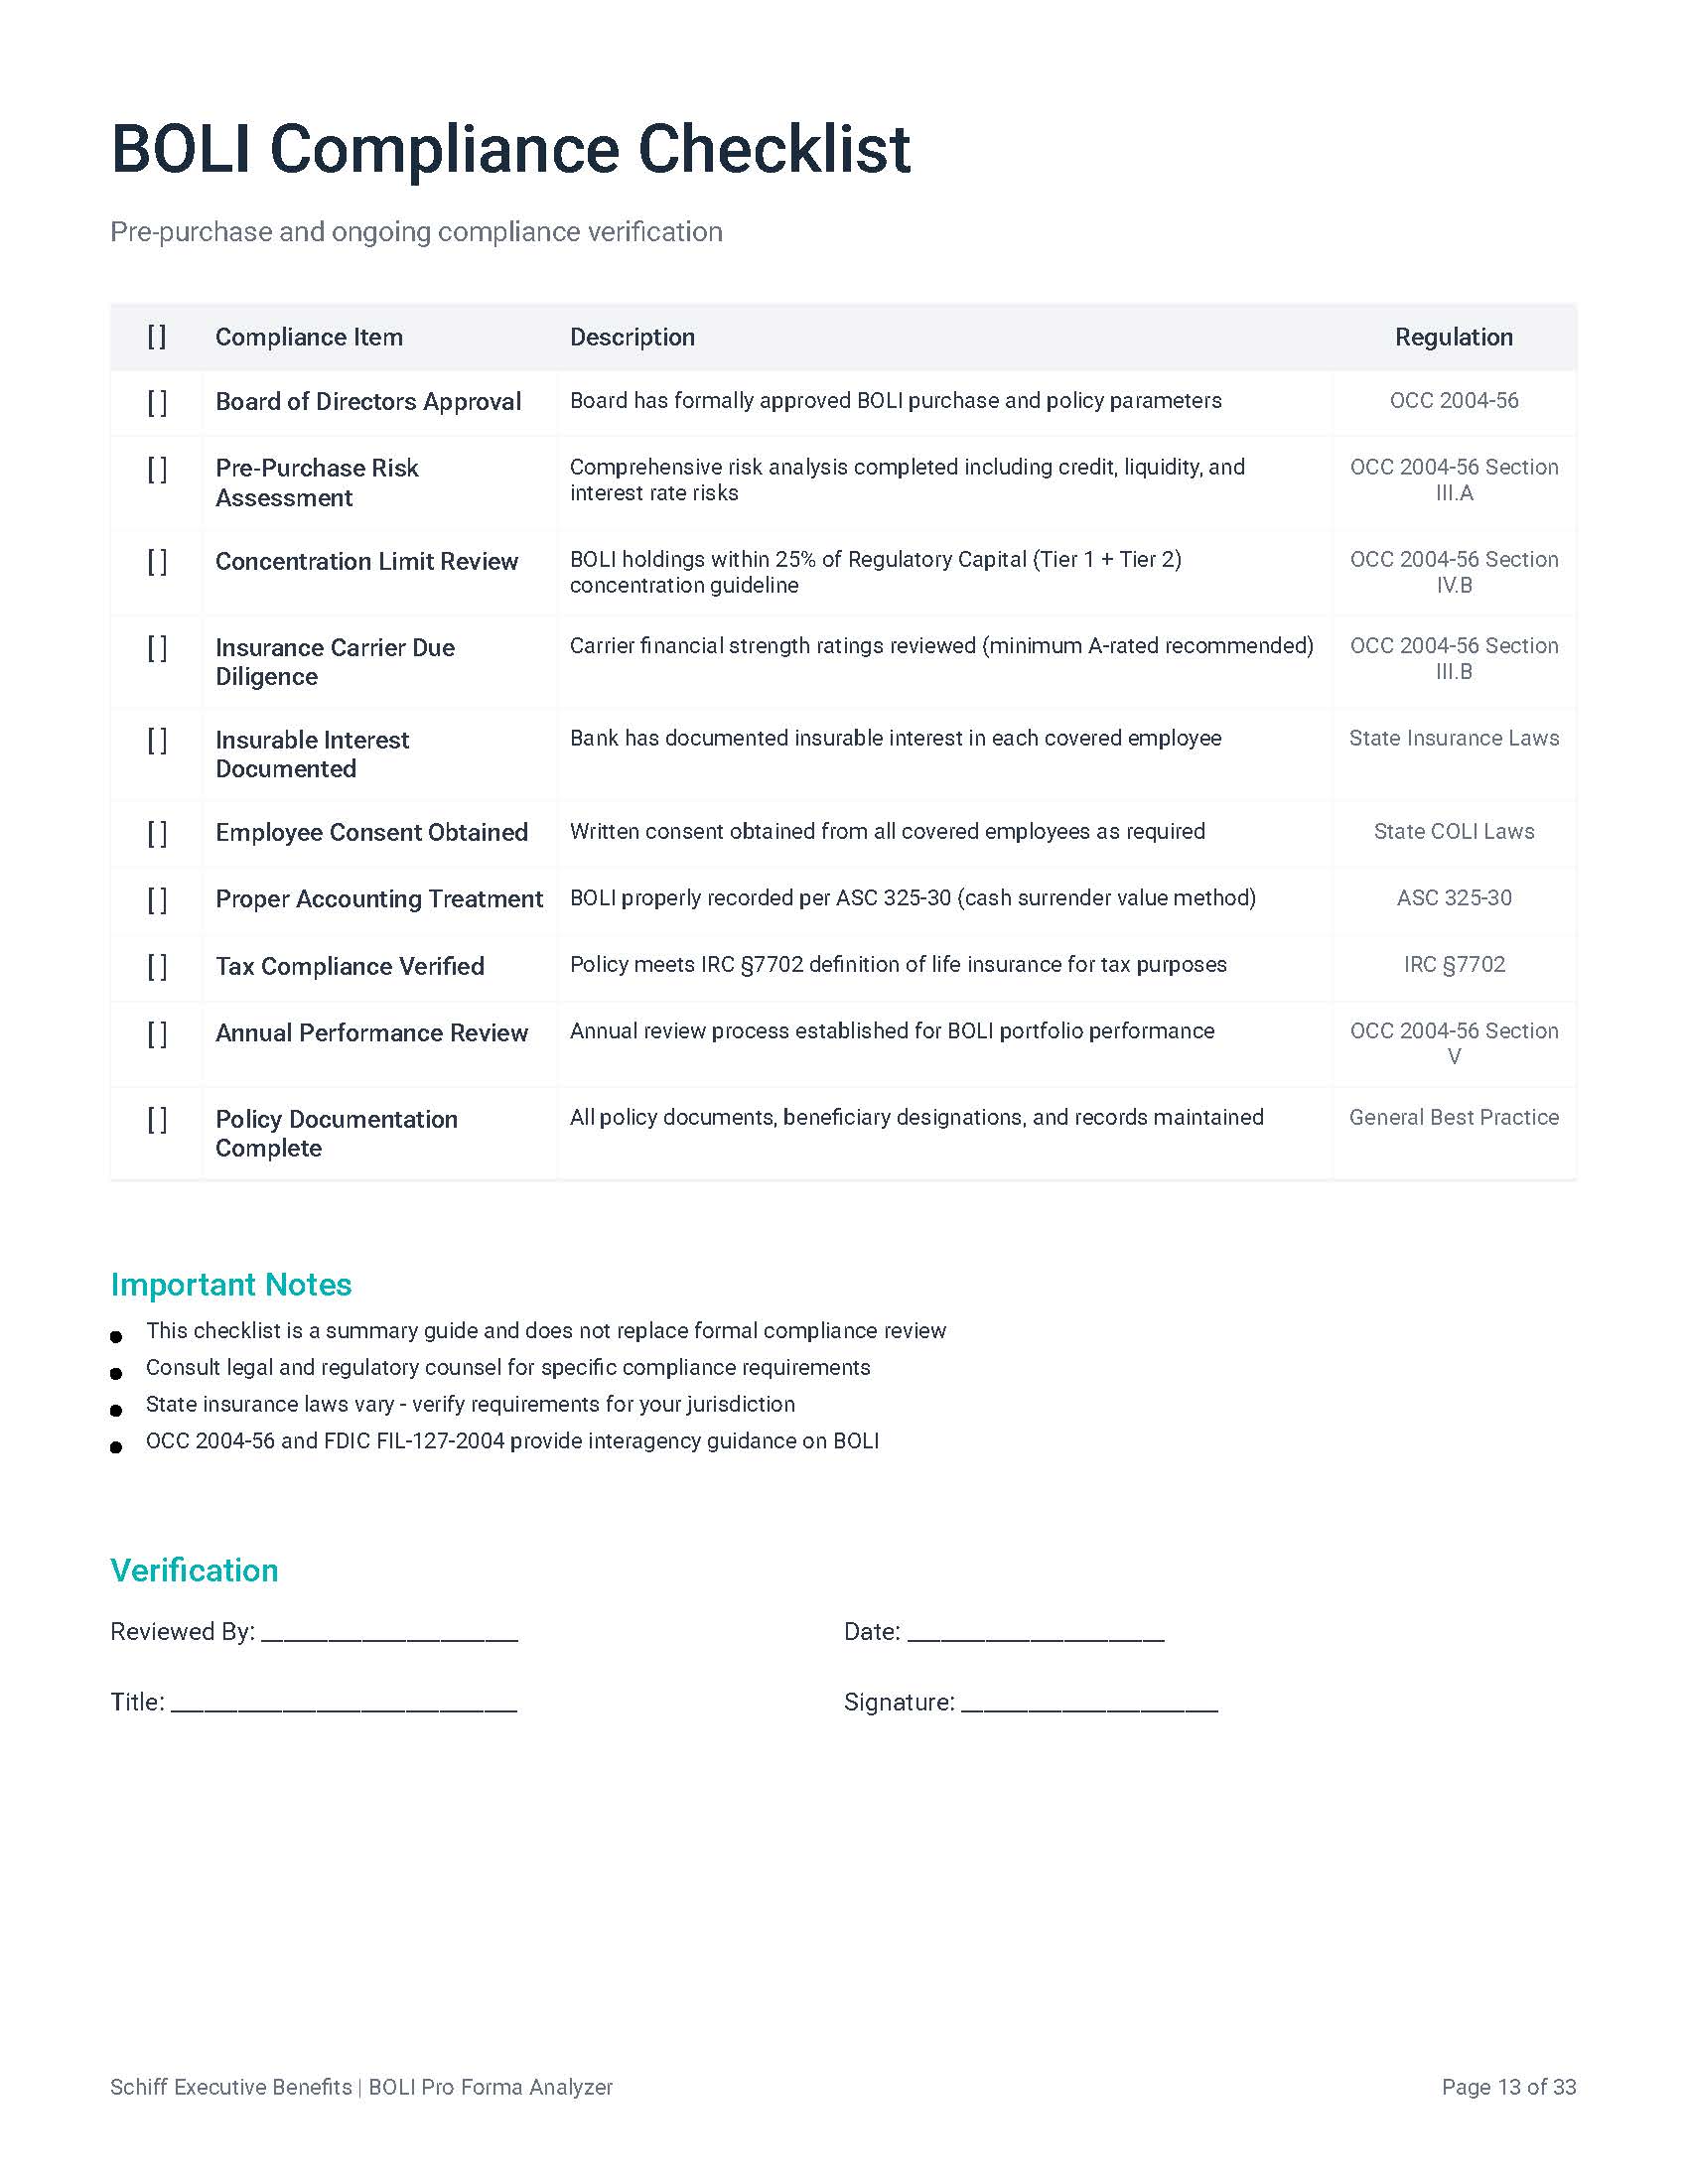
However, being "above" the average carries its own set of responsibilities. If you are pushing toward that 25% regulatory capital concentration limit, your documentation, your risk assessment, and your board oversight must be bulletproof.
The Technical Guardrails: OCC 2004-56 and IRC 7702
In this environment, you can’t afford to "wing it." The regulatory landscape for BOLI is defined largely by OCC Bulletin 2004-56. This isn't just a suggestion; it's the rulebook. It requires banks to perform comprehensive pre-purchase analysis and ongoing monitoring.
One of the most critical technical aspects we navigate with our clients is IRC Section 7702. This section of the Internal Revenue Code defines what actually constitutes a "life insurance contract" for federal tax purposes. If your policy doesn’t meet these stringent requirements, you lose the very tax advantages: tax-free inside buildup and tax-free death benefits: that make BOLI attractive in the first place.
At Schiff Executive Benefits, we focus on ensuring that every program we design is compliant not just today, but for the long haul. We reverse engineer the solution based on your specific liabilities, ensuring that the asset matches the intent.
Managing the 6 Key Risks
When the regulators come knocking, they aren't just looking at your earnings. They are looking at your risk management framework. OCC 2004-56 outlines six key risks that every bank must address regarding their BOLI holdings:
Liquidity Risk: BOLI is an illiquid asset. You can't just flip it for cash tomorrow without potential tax penalties and surrender charges. How does this fit into your overall liquidity profile?
Transaction/Operational Risk: This involves the complexity of the program. Is it being administered correctly? Are the death benefits being tracked?
Reputation Risk: What happens if the carrier fails? Or if the public perceives the plan as "excessive"?
Credit Risk: You are essentially making a long-term loan to an insurance carrier. Is that carrier stable? We work as a broker with a wide variety of top-tier carriers to ensure diversification and credit quality.
Interest Rate Risk: BOLI values can fluctuate based on the interest rate environment. Does your board understand the impact of a rising or falling rate environment on your BOLI yield?
Compliance/Legal Risk: From insurable interest laws to the 25% concentration limits, the legal hurdles are high.
Offsetting Benefit Bleed: Matching Assets to Liabilities
The most common "What If" we hear from bank presidents is: "What if our top talent leaves for the competitor down the street?"
In the current war for talent, standard 401(k) plans often fall short for high-earning executives due to IRS contribution limits. This is where we implement specialized tools like the 401k Mirror Plan.
But here is the catch: creating a promise (a liability) to pay an executive a SERP (Supplemental Executive Retirement Plan) or a Mirror Plan benefit in 15 years is easy. Funding it is the hard part. If you don't have an asset earmarked to grow alongside that liability, you are creating a massive hole in your future balance sheet.
By utilizing BOLI, we can match the asset to the future liability. When the executive retires, the cash value of the BOLI can provide the cash flow to pay the benefit. If the executive passes away prematurely, the death benefit protects the bank and the executive's family. It’s about restoring alignment and retention.
The Schiff Approach: Reverse Engineering Your Success
We don't believe in "off-the-shelf" products. Our team has almost 100 years of combined experience in technical benefit design. We don’t start with a BOLI policy; we start with your goals.
We ask the tough questions:
What is the cost of your current benefit "bleed"?
How much of your capital is working for you versus sitting in low-yield traditional assets?
Are your top three executives truly tied to the long-term success of the bank?
Once we have those answers, we "reverse engineer" a solution that fits your culture. We call this The Perfect Plan®. It’s a process that ensures your benefits are a bridge to your goals, not a weight on your earnings.
Where Do You Go From Here?
If you find that your bank is below the average, don't panic. It’s an opportunity. It means you have "eligible purchase capacity": dry powder that can be deployed to increase your ROA and secure your key people.
If you are above the average, it's time for a check-up. Are you managing those six key risks? Is your documentation up to the standards of the latest OCC exams?
Regardless of where you sit on the curve, the goal is the same: realizing your dream value and building it your way. Don't let your executive benefits be an afterthought.
If you want to see exactly how your bank stacks up against a specific peer group: not just national averages, but the banks in your own backyard: let’s talk. Sit back, grab your coffee, and come join us for a deeper dive into the technical side of retention.
Your legacy is too important to leave to chance. Let's make sure you have The Perfect Plan® in place and help your bank maximize your BOLI Portfolio. Our Proprietary BOLI Model can give you a peer analysis and projected earnings analysis in seconds. Give us a call at 610-292-9330 or email us at info@schiffbenefits.com for your bank's copy. We're here to help, and have the expertise to work with ANY carrier.
Benchmarking is a starting point, not a verdict. A peer average tells you what banks of roughly your size are doing; it tells you nothing about whether any of them did it well, or whether their circumstances resemble yours.
Two banks holding identical BOLI as a percentage of Tier 1 capital can be in completely different positions. One bought general account coverage from a highly rated carrier at a favorable crediting rate and has reviewed it annually since. The other holds a decade-old placement from a carrier that has since been downgraded, at a rate that quietly reset, with no documented review. The benchmark treats them as peers. An examiner will not.
Matching the average is therefore the wrong objective. The right question is whether your holding is sized to a real obligation, placed with carriers you would underwrite today, and structured so the economics still work under conservative assumptions.
BOLI vs. Traditional Fixed Income
The comparison that matters is against the specific asset the bank would otherwise hold for the same duration — not against an abstract benchmark.
Tax treatment. Interest on taxable securities is recognized currently. BOLI cash value accumulates without current tax, and death proceeds are generally received income-tax-free when IRC 101(j) is satisfied. On identical nominal yields, the after-tax outcomes diverge substantially over a long holding period.
Duration and liquidity. A bond portfolio can be sold. BOLI cannot be exited without surrendering the tax advantages that justified it. This is the central tradeoff, and it should be decided on the bank's actual liquidity profile rather than on a yield comparison alone.
Credit exposure. Fixed income carries issuer risk you can diversify at will. General account BOLI concentrates exposure in a small number of carriers, which is precisely why the 15% single-carrier guidance exists.
Earnings presentation. BOLI increases flow through non-interest income rather than interest income, which changes how the contribution appears in your margin analysis.
None of this makes BOLI categorically better or worse. It makes it a different instrument with a different risk profile, appropriate for capital the bank can genuinely commit for the long term.
The Governance Questions Your Board Should Be Asking
Whether you hold BOLI already or are evaluating a first purchase, these are the questions that separate a defensible program from one that draws criticism:
What specific benefit obligation does this holding offset, and how was the amount derived?
Where does aggregate cash surrender value sit against current Tier 1 capital, and against each individual carrier?
When was carrier financial strength last reviewed, and by whom?
Is actual crediting performance tracking what was illustrated at purchase?
Does 101(j) notice and consent documentation exist for every insured, including those inherited through acquisition?
Does the pre-purchase analysis exist in writing, dated before the purchase?
If the original business purpose has changed, does the holding still make sense?
A board that can answer all seven is in good shape. A board that cannot answer the last three has an examination problem waiting to surface, regardless of how the yield looks.
From Benchmark to Strategy
The point of measuring against peers is to prompt the harder question underneath: is this program built around your bank's obligations, or was it sized to look normal? Benchmarks describe the market. Strategy is what you do with your own balance sheet.
"The best time to plant a tree was twenty years ago. The second best time is now."
It’s an old aphorism, but in the world of executive benefits and bank regulation, it’s a universal truth that separates the thriving organizations from the ones just waiting for an audit to go sideways.
Welcome to the Friday Wrap. Pull up a chair, grab your coffee (black, if you’re doing it right), and let’s look at what we’ve tackled this week. We’ve been moving fast, focusing on two heavy hitters that define whether a company is truly aligned or just coasting on hope. We’re talking about the technical minefield of BOLI compliance and the strategic elegance of the Non-Qualified Deferred Compensation (NQDC) plan: otherwise known as the "401(k) Mirror."
At Schiff Executive Benefits, our mission is simple: Restoring Alignment and Retention. We spend our days reverse-engineering solutions to ensure that when you look at your top talent, you aren't asking yourself, "What if they leave?" Instead, you’re confident that they have every reason to stay. That is the core of The Perfect Plan®.
Section 1: The BOLI Compliance Minefield
First up, we dove deep into the world of Bank-Owned Life Insurance. Now, BOLI is a fantastic tool: it’s a way for banks to offset the rising costs of employee benefits using a tax-advantaged asset. But here is the problem: many boards treat BOLI like a "set it and forget it" crockpot.
Bad idea.
If you aren't staying on top of your BOLI compliance, you aren't just risking a slap on the wrist; you’re risking the "safety and soundness" rating of your entire institution. We discussed the 7 common mistakes boards make, and if any of these sound familiar, it’s time for a check-up:
The 25% Tier 1 Capital Guideline: You can’t just buy BOLI until your heart's content. Regulatory guidance (specifically OCC 2004-56) suggests that a bank’s total BOLI holdings should generally not exceed 25% of its Tier 1 Capital. Are you pushing that limit?
The 1% Concentration Rule: While not always a hard regulatory floor, many conservative boards set a limit that no single insurance carrier should represent more than 1% of the bank's total assets. Diversification isn't just for your personal portfolio; it’s for your balance sheet protection.
The IRC 101(j) Gotcha: This is the big one. If you don’t get written, informed consent from the employee before the policy is issued, the death benefit: which is supposed to be tax-free: becomes taxable. That is a massive, preventable unforced error.
Lack of Annual Board Review: The regulators want to see that the board is actually looking at the performance and risk of the BOLI asset every single year.
Credit Analysis Neglect: When was the last time you did a deep dive into the creditworthiness of the carriers holding your BOLI?
Ignoring Mortality Performance: Are you tracking how the actual mortality experience matches up against the projections you were sold?
Failing the Peer Analysis: Regulators love to see how you stack up against your peers. If you aren't doing a peer analysis of your BOLI holdings, you’re flying blind.
BOLI is a powerful component of The Perfect Plan®, but only if it’s managed with the precision it deserves.
Section 2: Breaking the "Success Ceiling" with the 401(k) Mirror
Next, we shifted gears to look at how corporate entities (and banks, too) handle their most expensive and valuable asset: their people.
Have you ever noticed that the more successful your executives become, the more the government penalizes them? It’s called the "Success Ceiling."
In a traditional 401(k), there is a hard limit on what an employee can defer. For high-earning executives, that limit often represents a tiny fraction of their total income: sometimes as low as 2% or 3%. While the rest of your staff can defer 10% or 15% toward their future, your top leaders are hitting a wall.
By creating a "Mirror" plan, you allow your key talent to defer significantly more of their compensation: often up to 80% of salary and 100% of bonuses: on a tax-deferred basis. It "mirrors" the 401(k) experience they already know: they choose their investments, they see their statements, and they watch their money grow.
Section 3: The Power of Golden Handcuffs
Why does this matter to you as a business owner or a board member? Because it solves one of the most critical of the "5 What Ifs": What if your top talent leaves?
When you implement a Mirror Plan, you aren't just giving them a place to save; you’re creating "Golden Handcuffs." By structuring employer contributions with specific vesting schedules or "tail" payouts, you create a powerful incentive for your executives to stay for the long haul.
Imagine an executive who has $500,000 or $1,000,000 in a deferred comp account that they only get if they stay for another five years. That makes the recruiter’s phone call a lot less tempting.
This is the essence of The Perfect Plan®. It’s about building a structure where the company’s goals and the executive’s personal financial goals are perfectly aligned. When they win, you win. When they stay, the company grows.
Section 4: Strategy Over Product
At Schiff Executive Benefits, we aren't just selling insurance or setting up plans. We’re reverse-engineering your goals. Whether it's ensuring your BOLI is compliant so you don't get a "Matter Requiring Attention" from the OCC, or designing a Mirror Plan that keeps your CEO from jumping ship to a competitor, we start with the intent.
Does your current benefit structure match your company culture? Does it actually protect you from the "What Ifs"?
If you're not sure, it might be time to take a look at how we build The Perfect Plan®. We work alongside your existing team: your accountants, your attorneys, and your TPA: to ensure that every piece of the puzzle fits perfectly.
Wrapping Up the Week
It’s been a productive week, but there is always more work to be done in the pursuit of alignment.
If any of this resonated with you: if you’re worried about your BOLI concentration limits or if you realize your top talent is hitting a ceiling they can’t break through: let’s talk.
You can check out our full range of services on our Posts page or, better yet, come join the conversation over on The Perfect Plan® Podcast YouTube channel. We’re constantly dropping new insights to help you navigate these technical waters.
Have a great weekend. Rest up, stay focused, and remember: alignment isn't an accident. It’s a choice.
Warmly,
Matt Schiff President, Schiff Executive Benefits
Schiff Executive Benefits helps businesses attract, retain, and reward key talent through goal-oriented reverse engineering and deep technical expertise. Visit us at schiffbenefits.com to learn more.
Note: This post is scheduled to publish on Friday, May 15, 2026, at 7:00 AM ET.
If you think the cost of compliance is high, try the cost of non-compliance. In the world of community banking, that isn’t just a catchy aphorism: it’s a reality that can show up on your doorstep during your next regulatory exam.
Bank-Owned Life Insurance (BOLI) is one of the most powerful tools available to help you offset the rising costs of employee benefits and "Restoring Alignment and Retention" within your executive team. But because it’s so effective, it’s also highly regulated. Whether you are a small community bank or a large regional institution, your BOLI program is under the microscope of the OCC, FDIC, and the IRS.
Are you confident that your board is steering the ship correctly, or are there hidden icebergs in your compliance reporting? Let’s look at the seven most common BOLI compliance mistakes boards make and, more importantly, how to fix them before the regulators do it for you.
1. Exceeding the 25% Tier 1 Capital Guideline
The interagency statement on BOLI (OCC 2004-56) is very clear: it is generally considered "imprudent" for a bank to hold BOLI with an aggregate Cash Surrender Value (CSV) that exceeds 25% of its Tier 1 Capital.
Many boards make the mistake of looking at this as a "one and done" calculation at the time of purchase. However, Tier 1 Capital fluctuates. If your bank experiences a capital hit or if your BOLI portfolio grows faster than your capital base, you could suddenly find yourself in a concentrated position.
The Fix: Your board should receive a quarterly "Capacity Analysis" that measures your BOLI holdings against current Tier 1 Capital levels. At Schiff Executive Benefits, we help banks reverse-engineer these calculations to ensure you have a "buffer" that accounts for both portfolio growth and potential capital volatility.
2. Ignoring the 1% Asset Concentration Limit
While the 25% rule covers your entire BOLI portfolio, there is a second, more granular rule: the 1% asset concentration guideline. This limits the amount of BOLI you can hold with a single insurance carrier to no more than 1% of your bank’s total assets.
Concentrating too much risk with one carrier is a red flag for regulators who are concerned about credit risk. If that carrier’s credit rating slips, your entire benefit-funding strategy could be compromised.
The Fix: Diversification is your best friend. If you are approaching that 1% threshold, any new BOLI purchases should be spread across a basket of highly-rated carriers. This not only keeps the regulators happy but also protects your bank from "putting all its eggs in one basket."
3. The "Silent Killer": IRC 101(j) Oversight
If there is one technicality that keeps bank CEOs up at night, it should be IRC Section 101(j). This IRS regulation requires that any employee whose life is being insured must provide written notice and consentbefore the policy is issued.
If you fail to get that signed consent: or if you can’t find the paperwork during an audit: the death benefit, which is normally tax-free, could become taxable income. For a bank, that is a catastrophic financial blow to a program designed for cost recovery.
The Fix: Conduct a "Notice and Consent Audit." Ensure every single file has a signed, dated consent form that precedes the policy effective date. If you're missing one, don't wait. Talk to your advisors about remediation immediately.
4. Failing to Conduct a Pre-Purchase Analysis (OCC 2004-56)
Some boards treat BOLI like a standard investment product: they look at the yield, the carrier rating, and pull the trigger. But the OCC 2004-56 guidelines require a much deeper dive. You must document that you’ve analyzed the risks: liquidity risk, transaction risk, reputation risk, and credit risk.
Regulators want to see that the board didn't just "buy a product" but instead "approved a strategy." If your board minutes don't reflect a robust discussion of these risks, you're failing the compliance test.
The Fix: Every BOLI purchase should be preceded by a formal Pre-Purchase Assessment. This document should outline exactly how the BOLI offsets specific benefit liabilities and why the chosen carriers were selected over others.
5. The "Set It and Forget It" Mentality
One of the most dangerous phrases in a boardroom is, "We already have BOLI; we're good." BOLI is not a static asset. As interest rates move and mortality tables change, the performance of your policies will shift.
The Interagency Statement mandates an annual post-purchase review. This isn't just a courtesy; it’s a requirement. You need to assess the creditworthiness of the carriers, the performance of the separate accounts (if applicable), and the continued need for the coverage.
The Fix: Schedule a formal annual BOLI review with your board. This review should be documented in the minutes and include an updated credit analysis of every carrier in your portfolio. If you haven't seen a performance report in over 12 months, you're officially behind.
6. Lack of Independent Vendor Due Diligence
Are you relying solely on the insurance carrier's marketing materials for your compliance data? Regulators expect the board to perform independent due diligence. You need to verify that the carrier's financial strength is being monitored by an objective third party and that the pricing of the product is competitive.
If your "advisor" only shows you one carrier or one product, you aren't doing due diligence: you're being sold.
The Fix: Work with a consulting firm that acts as a broker with access to the entire market. At Schiff Executive Benefits, we pride ourselves on being carrier-agnostic. We don't have a "favorite" carrier; we have a favorite solution that fits your bank's specific culture and risk appetite.
7. Misalignment with Executive Retention Goals
The ultimate goal of BOLI is to fund executive benefits that help you attract and keep your top talent. However, many banks have BOLI programs that are completely decoupled from their actual benefit liabilities.
If you have $10 million in BOLI but your Supplemental Executive Retirement Plan (SERP) is underfunded or non-existent, you are holding a tax-advantaged asset without the "purpose" that justifies it to regulators. This misalignment is a "What If" that often leads to top talent leaving for a competitor who offers a more structured retirement plan.
The Fix: This is where we excel. We use a process called "Goal-Oriented Reverse Engineering." We start with your goal: retaining your CEO or CFO: and work backward to design the benefit and the BOLI funding strategy that makes it cost-effective for the bank. This ensures your program is "Gospel-compliant" with your bank’s mission.
Building Your Perfect Plan®
Compliance doesn't have to be a burden that slows your bank down. When handled correctly, it becomes the foundation of a rock-solid executive benefit strategy that protects the bank’s capital and rewards its most valuable people.
Are you worried about your 25% Tier 1 limit? Are you unsure if your IRC 101(j) paperwork is in order? Don't wait for the regulators to point out the cracks in your foundation.
We invite you to sit back, grab your coffee, and join us for a deeper dive into these strategies. You can learn more about our philosophy by watching The Perfect Plan® where we break down complex technical topics into actionable advice for business owners and bank boards.
If you’re ready to ensure your BOLI program is fully compliant and optimized for cost recovery, reach out to our team today. Let’s make sure your board is making the right moves to protect your bank’s future.
Disclaimer: Schiff Executive Benefits does not provide legal or tax advice. Always consult with your qualified legal and tax advisors regarding your specific situation and compliance with IRC 101(j) and OCC guidelines.
They say that the only constant in life is change, but in the world of high-stakes banking and executive leadership, the only constant is the relentless need for top-tier talent. Without the right people in the right seats, even the most storied financial institutions are just buildings with impressive vaults.
We’ve all felt the shift. The landscape of executive benefits is evolving faster than a New Orleans jazz solo. Tax codes shift, regulatory scrutiny tightens, and the "Great Reshuffle" has turned the hunt for executive retention into a strategic arms race.
If you are an advisor to the banking industry’s elite, or a leader responsible for the long-term health of your institution, you know that standing still is the same as moving backward. That is why we are thrilled to announce that registration is officially live for the 2026 Independent Bank Corporate (IBC) Owned Life Insurance Study Group.
From November 1–3, 2026, we are returning to our spiritual home at the Hotel Monteleone in New Orleans. This isn't just another industry conference where you sit in a windowless ballroom and trade business cards over lukewarm coffee. This is an exclusive gathering designed for top-tier advisors who are serious about Restoring Alignment and Retention.
Why New Orleans? Why Now?
There is a reason we keep coming back to the French Quarter. Beyond the history and the atmosphere, New Orleans represents a blend of tradition and innovation: much like the strategies we discuss.
What keeps you up at night? For many of our attendees, it’s the "What Ifs" that haunt the boardroom.
What if your top talent leaves for a competitor tomorrow?
What if a senior executive retires and the replacement cost exceeds your projections?
What if a sudden tragedy leaves the business dealing with a widow or a complex succession crisis?
These aren't just hypothetical anxieties; they are the fault lines that can crack a bank’s foundation. At the 2026 IBC Study Group, we don’t just identify these problems; we build the solutions. We focus on the mechanics of Bank-Owned Life Insurance (BOLI) and Corporate-Owned Life Insurance (COLI) not as mere products, but as the engine for The Perfect Plan®.
The Technical Heart: BOLI and Beyond
While the surroundings are legendary, the core of this study group is deeply technical. We dive into the weeds of cost-recovery strategies and the nuances of Bank-Owned Life Insurance (BOLI).
In today’s volatile market, banks are looking for ways to offset the rising costs of employee benefits without taking on undue risk. BOLI remains one of the most effective tools for institutional capital management, offering tax-deferred growth and tax-free death benefits that can be used to fund non-qualified deferred compensation (NQDC) plans or supplemental executive retirement plans (SERPs).
Our sessions will cover:
Advanced Cost-Recovery Models: How to structure BOLI to ensure that the bank is made whole for the costs of executive benefits.
Executive Retention Strategies: Moving beyond standard bonuses to create "Golden Handcuffs" that actually work.
Regulatory Compliance: Navigating the latest updates to ensuring your plans remain "Gospel-compliant" with current tax and banking laws.
Succession Planning: Solving the "Business with a Widow" scenario through structured buy-sell arrangements and key-person coverage.
We understand that you are navigating an unstable financial environment. You need a guide who has been through the cycles. Our team at Schiff Executive Benefits acts as that guide, helping you realize your institution’s dream value while protecting your most valuable assets: your people.
Food, Fun, and Friendship: The Monday Night Highlight
We have always believed that the best business happens when the formal ties are loosened. The IBC Study Group has built a reputation on the "Three Fs": Food, Fun, and Friendship. This year, we are taking that to a new level.
On Monday night, we are hosting a Mardi Gras Theme Jazz Reception and Dinner in the brand-new Courtyard at the Hotel Monteleone. Imagine the sound of a brass band echoing off the brick walls, the scent of authentic Creole cuisine in the air, and the chance to network with the brightest minds in the industry in a setting that is uniquely New Orleans.
This isn't just a dinner; it’s an experience designed to foster the kind of deep professional relationships that last decades. It’s where the real "Study Group" happens: sharing stories of what worked, what didn't, and how we are all navigating the complexities of the modern financial world.
Is This Group Right for You?
The IBC Study Group is an exclusive circle. We intentionally keep the numbers focused to ensure that every participant can engage in the high-level dialogue that makes this meeting so valuable.
If you are an advisor who deals with:
Institutional BOLI portfolios.
Corporate-Owned Life Insurance (COLI) for non-bank entities.
Executive benefit plan design and 409A compliance.
ESOPs and partnership buy-outs.
...then you belong in the room. This is your opportunity to step away from the day-to-day grind and look at the big picture. Are you building a legacy, or just managing a spreadsheet? Are you offering your clients The Perfect Plan®, or just a standard off-the-shelf solution?
Secure Your Spot
The 2025 Study Group was a complete sell-out, and we expect 2026 to follow suit. The combination of the Monteleone’s charm, the technical depth of our sessions, and the new Monday night Jazz Reception makes this a "must-attend" event on the calendar.
Don't let the "What Ifs" stay unanswered.
What if you miss out on the specific tax-efficiency strategies that could save your client millions?
What if your competitors are in New Orleans while you’re at your desk?
Registration is now live for the meeting, and hotel reservations are now available through the Hotel Monteleone room block. Important: meeting registration does not cover your hotel booking. They are separate, and you will need to complete both.
If you prefer to call in your reservation, contact 504-523-3341 or 800-535-9595 between 9:00 a.m. and 5:00 p.m. CDT and reference the block code IBC30J.
Sit back, grab your coffee, and mark your calendar. We are heading back to the Big Easy to restore alignment, ensure retention, and celebrate the profession we love.
We can't wait to see you in the Courtyard.
Schiff Executive Benefits is dedicated to helping businesses and banks navigate the complexities of executive retention and cost recovery. ThroughThe Perfect Plan®, we provide the security and guarantees needed in an uncertain world.
For more information on our services or to view our latest insights, visit ourposts feed.
Bank-Owned Life Insurance (BOLI) is life insurance a bank purchases on the lives of its officers and directors, where the bank owns the policy, pays the premium, and is the beneficiary. Banks use BOLI as a tax-advantaged balance sheet asset to offset the rising cost of employee benefit programs. Cash surrender value grows tax-deferred, death proceeds are generally received income-tax-free, and the resulting yield typically exceeds what the same capital would earn in taxable short-term instruments of comparable credit quality.
BOLI is permissible for national banks under 12 U.S.C. 24 (Seventh) and is governed by the 2004 Interagency Statement on the Purchase and Risk Management of Life Insurance. The Statement sets supervisory guidelines rather than statutory caps: aggregate cash surrender value is generally expected to stay within 25% of Tier 1 capital, with exposure to any single carrier generally within 15%. It also calls for a documented pre-purchase analysis.
The same structure bought by an operating company is called COLI; bought by an insurance carrier, iCOLI.
A bank is only as strong as its community, and its community is only as strong as the leaders who serve it. In the financial world, stability is the cornerstone of trust. Yet, many bank executives find themselves facing an unstable paradox: how do you maintain a competitive edge and protect your balance sheet while simultaneously funding the escalating costs of employee benefits?
If you are leading a financial institution today, you are likely wrestling with the "What Ifs" that keep even the most seasoned presidents awake at night. What if your top talent is lured away by a larger competitor? What if the cost of your pension and health plans continues to outpace your portfolio’s yield? What if your senior executive retirement costs become a drag on your regulatory capital?
To find the answer, we look toward a strategy utilized by over 65% of banks in the United States. It is a tool designed for Restoring Alignment and Retention: Bank-Owned Life Insurance (BOLI).
What is BOLI, and Why Does It Matter?
At its most fundamental level, Bank-Owned Life Insurance is a life insurance policy purchased by a bank on the lives of its key employees: usually officers and directors. The bank is the owner and the beneficiary of the policy.
While the term "insurance" is in the name, for a financial institution, BOLI is primarily a sophisticated investment and a Tier 1 asset. The bank pays a premium (often a single lump sum), and the cash value of the policy grows over time.
Why is this so popular? Because it solves the problem of "lazy capital." Instead of holding assets in low-yield taxable instruments, banks move capital into a tax-advantaged BOLI structure where the growth can offset specific liabilities. It is a method of taking a "dead" expense: like the cost of executive benefits: and turning it into a high-performing asset.
The Economic Reality: After-Tax Yield and Efficiency
In a world where interest rates are volatile and traditional fixed-income yields are often squeezed by taxes, BOLI stands out as a beacon of efficiency.
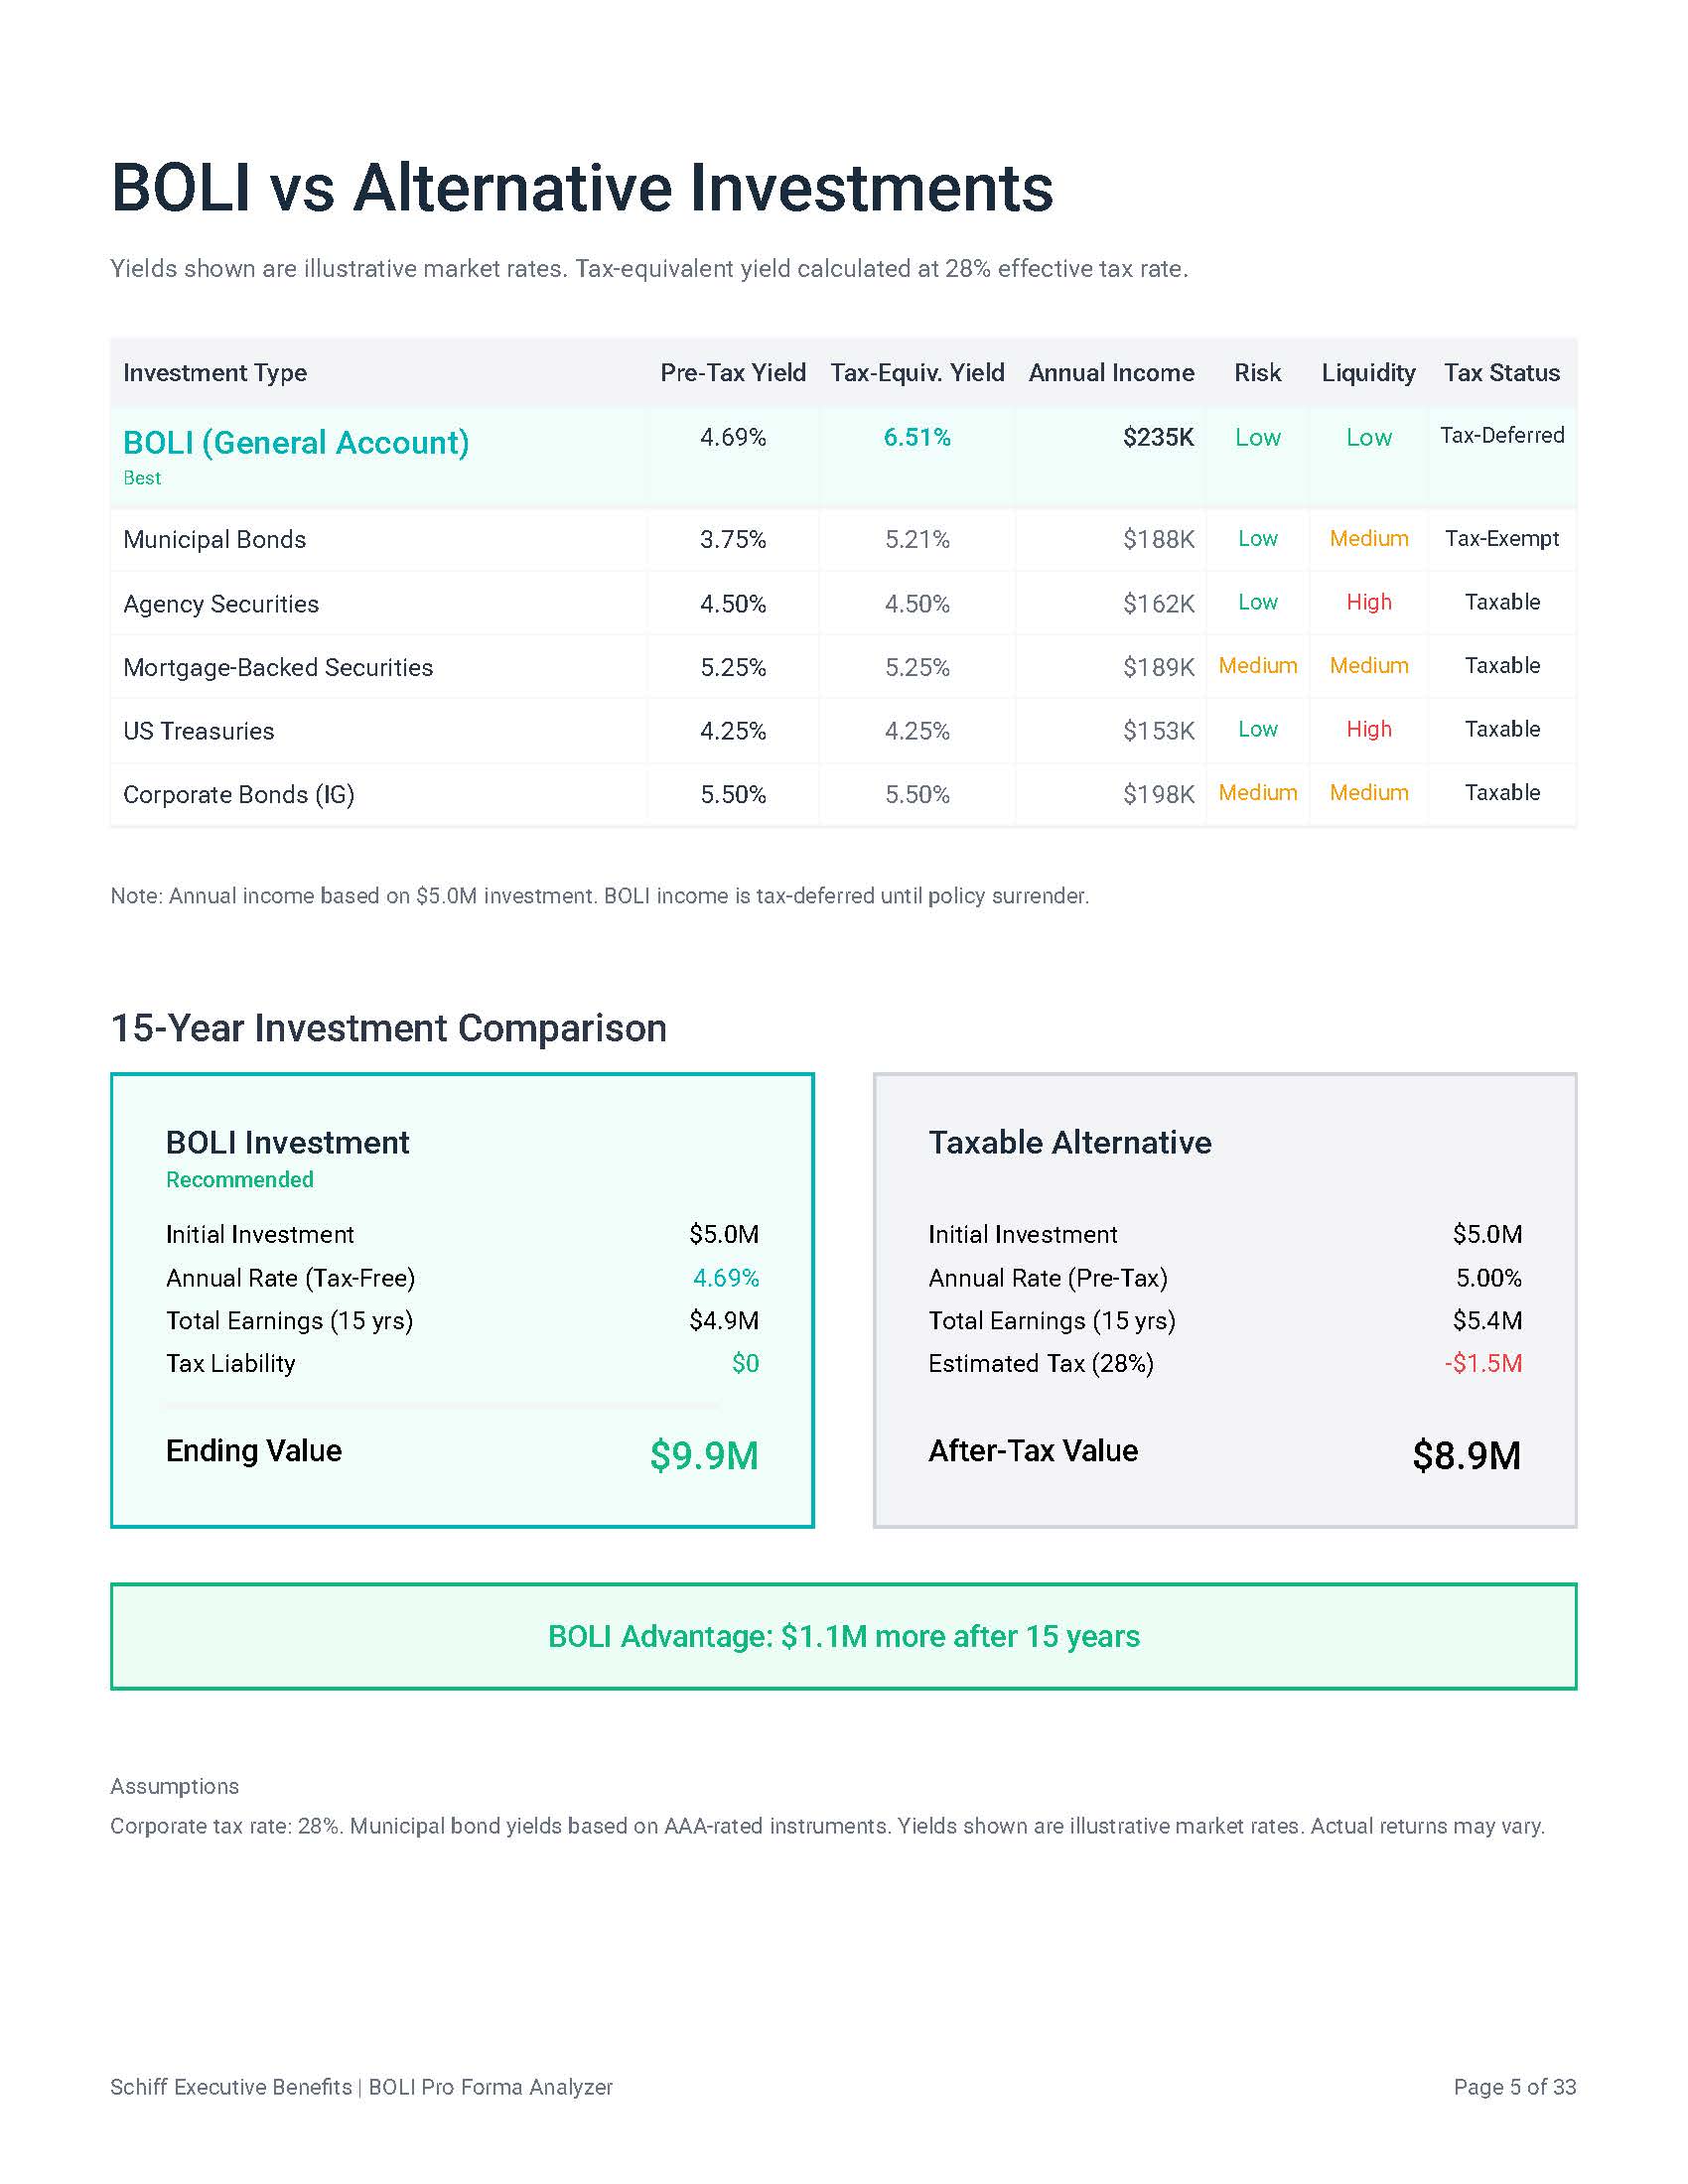
When you compare BOLI to alternative fixed-income investments: such as municipal bonds, agency securities, or Treasuries: the difference is often staggering. Because the cash value growth within a BOLI policy is tax-deferred (and tax-free if held until the death of the insured), the "tax-equivalent" yield is significantly higher than what a bank can typically earn elsewhere.
As shown in our proprietary BOLI Pro Forma Analyzer, a $5 million investment in BOLI can provide a tax-equivalent rate that significantly outperforms corporate bonds or MBS portfolios. This isn't just about "beating the market"; it’s about generating the necessary cash flow to fund Non-Qualified Deferred Compensation (NQDC) and other executive carve-outs that are essential for retention.
Offsetting the Rising Cost of Talent
What is the true cost of losing your CFO or a high-performing VP of Lending? It isn't just the recruiter's fee. It is the loss of institutional knowledge, the disruption of client relationships, and the significant expense of "buying" a replacement in a competitive market.
Most banks use BOLI to recover the costs of:
Post-retirement medical benefits
Supplemental Executive Retirement Plans (SERPs)
Group term life insurance premiums
401(k) matching and pension obligations
By utilizing BOLI, you are essentially creating an informal "sinking fund" to pay for these future obligations. It allows you to offer "ownership-like" benefits without actually diluting your bank’s equity. This is how you retain your key people while keeping the bank’s financial health intact.
Regulatory Compliance: The Tier 1 Advantage
One of the most frequent questions I get from Bank Presidents is: "How will the regulators view this?"
The answer is found in the Interagency Statement on the Purchase and Risk Management of Life Insurance. BOLI is recognized as a permissible investment for banks, provided it is managed within specific guidelines. Most notably, the Office of the Comptroller of the Currency (OCC) and other regulators generally allow BOLI holdings up to 25% of a bank’s Tier 1 capital.
Because BOLI is a high-quality asset backed by highly-rated insurance carriers, it provides a stable foundation for your balance sheet. Unlike securities portfolios, BOLI cash values are typically not subject to the "mark-to-market" volatility that can plague a bank during periods of rising interest rates. This makes it a preferred tool for managing earnings consistency.
The Human Element: Survivor Income as an Incentive
While the bank is the primary beneficiary, BOLI can also be structured to provide a powerful direct benefit to the insured executives.
Through "split-dollar" arrangements, a portion of the death benefit can be directed to the executive’s family. This provides "pre-retirement survivor income": a massive incentive for a key leader who wants to ensure their family is protected while they focus on growing your institution.
Think about the peace of mind you are offering your top officers. You aren't just giving them a salary; you are giving them a legacy. When you align the bank’s financial goals with the personal security of its leaders, you create an environment where talent stays for the long haul.
Why the "Carrier Agnostic" Approach Matters
The BOLI market is nuanced. There are different types of products: General Account, Hybrid Account, and Separate Account: each with its own risk profile and yield potential.
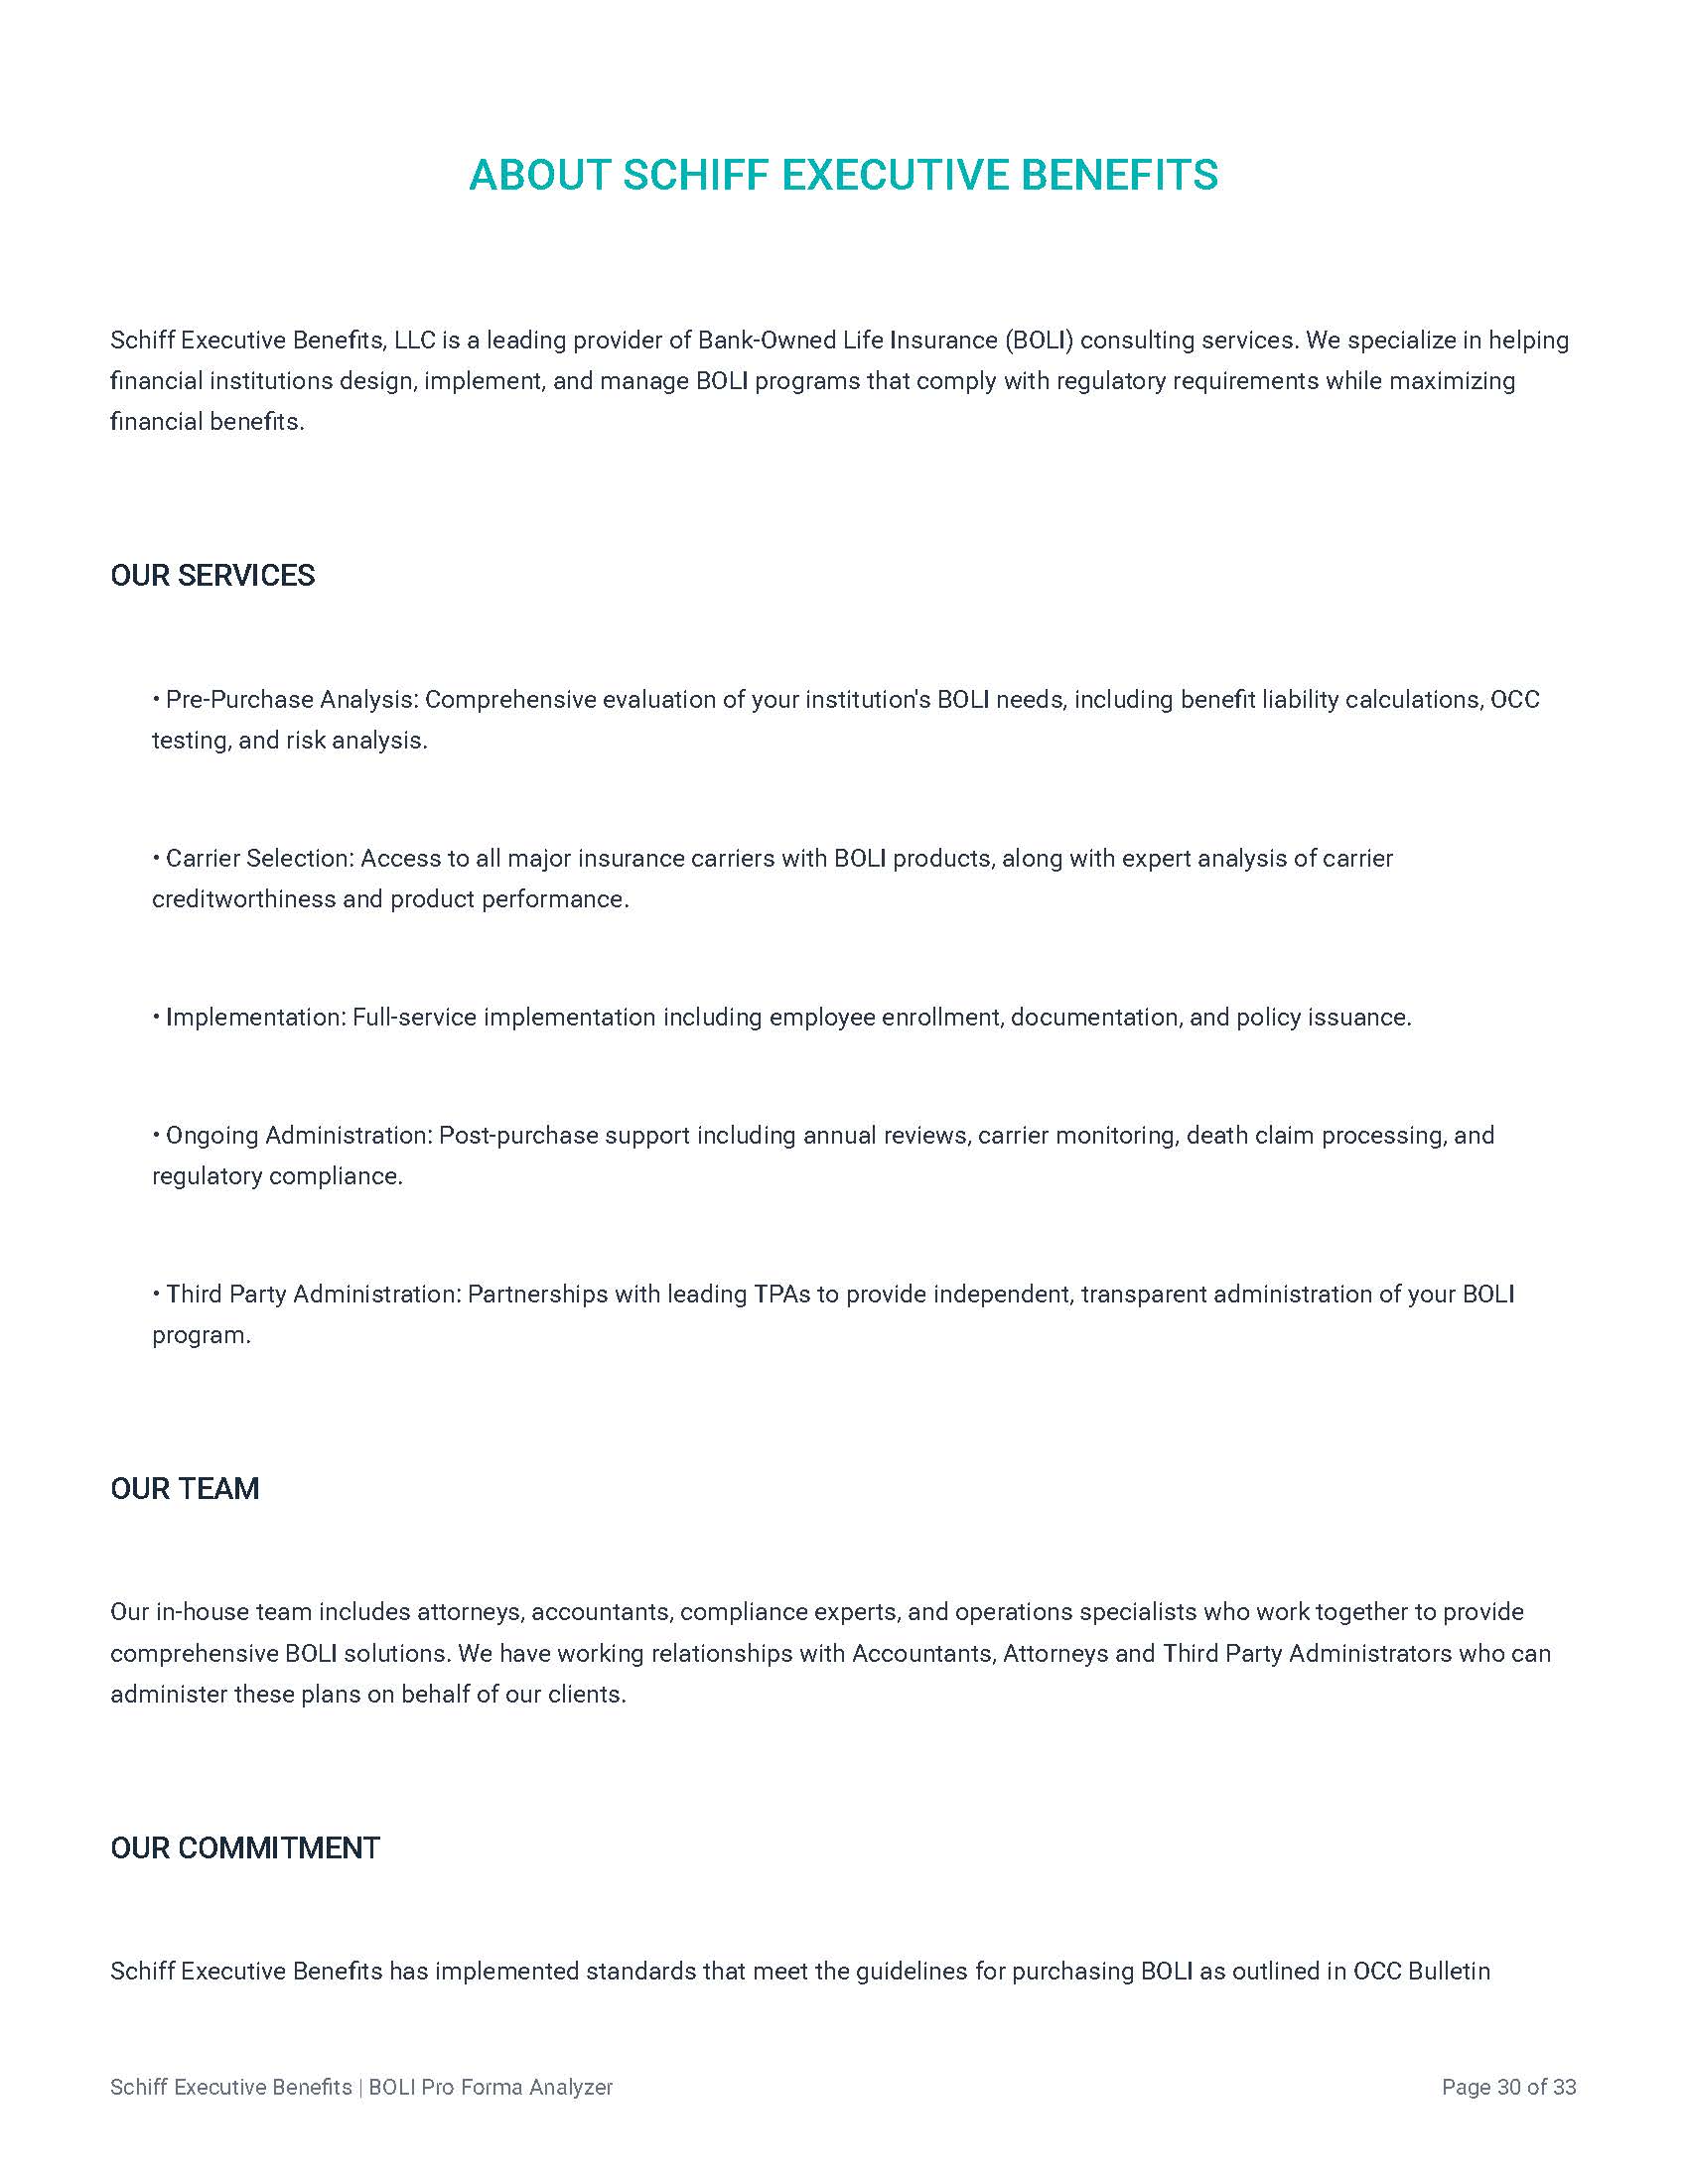
At Schiff Executive Benefits, we believe that your bank deserves a solution tailored to your specific capital structure and risk appetite, not a "product of the month." We operate as independent brokers, which means we work with all the major, highly-rated carriers to find the right fit for you.
Our process, which we call The Perfect Plan®, involves:
A Deep-Dive Needs Analysis: We look at your current benefit liabilities and capital ratios.
Carrier Evaluation: We vet the financial strength and historical performance of potential insurance partners.
Pro Forma Modeling: We show you exactly how BOLI will impact your EPS and ROA over 10, 20, and 30 years.
Implementation and Administration: We handle the heavy lifting, from board education to ongoing compliance monitoring.
The Point of No Return: Why Wait?
Every day that your bank's benefit liabilities grow while your assets remain in taxable, low-yield accounts is a day of lost opportunity. Economic shifts are coming, and the cost of talent is not going down.
Are you prepared for the next five years? What if your replacement cost for your senior team increases by 20%? What if your 401(k) matches become a burden on your margins?
BOLI is not just a financial product; it is a strategic shield. It provides a calm, structured way out of the anxiety of rising costs. It allows you to focus on what you do best: banking: while we ensure your "human capital" is fully funded and protected.
Join Us for a Deeper Conversation
Navigating the complexities of executive benefits and BOLI doesn't have to be a solo journey. Whether you are looking to implement your first BOLI plan or you want a review of your existing holdings to ensure they are performing as promised, we are here to help.
Sit back, grab your coffee, and let's discuss how we can bring stability back to your executive suite. Building your bank’s legacy should be a realization of your dream value, not a source of stress.
Come join us and discover how The Perfect Plan® can help you achieve alignment and retention.
A BOLI purchase is a reallocation of existing bank assets, not new spending. The bank moves capital from a taxable holding — typically short-duration securities or fed funds — into an insurance contract on the lives of consenting officers.
The bank identifies a legitimate business need, usually the cost of an existing or planned benefit obligation.
It performs and documents a pre-purchase analysis covering need, amount, carrier selection, product characteristics, and risk.
Eligible insureds provide written notice and consent before any policy is issued.
The bank pays a single premium, or a limited series, and records the cash surrender value as an asset.
Cash value accumulates tax-deferred at the credited rate, and the increase is recognized in non-interest income.
At the insured's death, the carrier pays the bank; proceeds above carrying value are generally income-tax-free.
The reason this works economically is the absence of current tax on the inside build-up. A taxable instrument yielding the same nominal rate is worth materially less after tax. That spread is the entire case for BOLI, and it is why the comparison must always be run against the specific alternative the bank would otherwise hold.
BOLI Is a Hold-to-Maturity Asset
Surrendering a policy generally triggers ordinary income on the gain and forfeits the tax-free death benefit — the two features that justified the purchase. BOLI should therefore be underwritten as a permanent allocation. A bank that may need that liquidity inside ten years is not a good candidate, and any presentation that treats cash value as a liquidity source deserves scrutiny.
The Three Account Types
Product selection drives most of the risk difference between two otherwise identical BOLI programs.
General Account — assets sit in the carrier's general account. The carrier declares a credited rate, usually with a guaranteed floor. Simplest to administer, and the bank takes direct credit exposure to the carrier. Suits smaller programs and banks that prefer a declared rate over transparency.
Separate Account — assets are held in a segregated account, insulated from the claims of the carrier's general creditors. Returns track the underlying portfolio, so a stable value protection wrapper is generally used to smooth book value. More transparent, more moving parts, and the wrap provider becomes its own counterparty to diligence.
Hybrid Account — a general account chassis with some separate-account characteristics, typically better rate transparency than pure general account without the full complexity of a wrapped separate account.
Institutional Indexed Universal Life — crediting tied to an index formula subject to caps and floors. Requires the board to understand exactly how the crediting method behaves in a flat or negative index year.
There is no universally correct answer. The right structure follows from the bank's size, its credit appetite, its comfort with mark-to-market mechanics, and how much administrative capacity it has.
Aggregate cash surrender value of all life insurance holdings is generally expected to remain within 25% of Tier 1 capital, with exposure to any single carrier generally within 15%. These are supervisory guidelines rather than statutory caps — a bank exceeding them is not automatically in violation, but is expected to document why the concentration is prudent and how it is managed. In practice, examiners treat an undocumented excess far more harshly than a well-reasoned one.
The Pre-Purchase Analysis
This is where most criticized BOLI programs fail, and the failure is almost always documentation rather than economics. A defensible analysis addresses:
The specific business need and the benefit obligation being offset
The amount of insurance and how that amount was derived
Vendor and carrier selection, including financial strength and the basis for choosing among carriers
Product characteristics, including crediting methodology and surrender charges
Alternatives considered and why BOLI was preferred
The full risk assessment — liquidity, credit, interest rate, operational, compliance, reputation, and price risk
Evidence of board or committee review and approval before purchase
The analysis must exist before the purchase. Reconstructing one after an examiner asks is not the same thing, and examiners can tell the difference.
Ongoing Risk Management
Approval at purchase does not end the obligation. Regulators expect periodic review — at minimum annually — covering carrier financial condition, policy performance against expectations, continued compliance with concentration guidance, and confirmation that the original business purpose still holds. Programs that were bought correctly and then left unmonitored for a decade are a recurring examination finding.
IRC 101(j): Notice and Consent
BOLI is employer-owned life insurance, so IRC 101(j) applies with full force. Since the Pension Protection Act of 2006, death proceeds are taxable to the bank above premiums paid unless, before the policy is issued, the insured has been notified in writing of the intent to insure and the maximum face amount, has consented in writing to coverage that may continue after employment ends, and has been informed the bank will be a beneficiary.
The insured must also fall within a qualifying category, which in a banking context generally means directors and highly compensated employees as defined in the Code. The bank files Form 8925 annually with its return.
Two situations create most of the exposure. The first is acquisition: banks that grow by merger routinely inherit policies without inheriting the consent files. The second is time — programs bought fifteen years ago by people who have since retired, where nobody has verified that the documentation still exists. Both are worth auditing before a claim rather than during one.
Accounting Treatment
An investment in life insurance is reported at the amount realizable under the contract at the balance sheet date, which in practice means cash surrender value net of any surrender charge the bank would actually incur. Periodic increases flow through non-interest income. Death proceeds above carrying value are recognized when realizable.
Two consequences worth raising with your CFO before the first premium: the asset recorded in year one is cash surrender value, not premium paid, and in some product designs those differ meaningfully at the outset. And the carrier's annual statement becomes audit support, so the reporting relationship matters as much as the crediting rate.
What BOLI Actually Funds
BOLI is informal financing, not funding. The policy is a general asset of the bank; it is not pledged, segregated, or promised to any participant. Most programs are used to offset:
Split dollar and endorsement arrangements providing survivor income to officers' families
General group benefit costs — health, disability, and post-retirement obligations
Any plan document or officer communication implying the policy secures the benefit creates a constructive receipt problem and undermines the arrangement. The promise and the asset must stay legally separate.
Where BOLI Programs Go Wrong
Missing 101(j) consent — the most expensive failure, and almost always found at claim rather than at purchase.
Thin or backdated pre-purchase analysis — the most common examination criticism.
Carrier concentration drift — a program that was inside the 15% single-carrier guideline at purchase can breach it as capital changes or as one carrier's block outperforms.
Orphaned programs — the originating producer is gone, nobody reviews performance, and the crediting rate has quietly reset.
Product mismatch — separate account complexity sold to a bank without the staff to administer it, or a general account placement with a carrier whose financial strength has since deteriorated.
Free Download: Bank-Owned Life Insurance (BOLI) Guide
Tell us where to send it. The PDF opens right away, and we will email you a copy.
Frequently Asked Questions About BOLI
What is BOLI in banking?
BOLI is life insurance owned by a bank on the lives of its officers and directors, held as a balance sheet asset to offset employee benefit costs. The bank pays the premium, owns the cash value, and receives the death benefit.
Is BOLI legal for banks?
Yes. National banks may purchase and hold life insurance under 12 U.S.C. 24 (Seventh) in connection with employee compensation and benefit plans, key person coverage, and related purposes. State-chartered institutions operate under comparable state authority. The purchase must address a legitimate business need.
How much BOLI can a bank own?
Supervisory guidance generally expects aggregate cash surrender value within 25% of Tier 1 capital, and within 15% for any single carrier. These are guidelines requiring documented justification if exceeded, not hard statutory ceilings.
Are BOLI premiums tax deductible?
No. Premiums on a policy where the bank is a beneficiary are not deductible. The tax advantage sits in the tax-deferred accumulation and the generally tax-free death benefit.
What happens to BOLI when an insured officer leaves the bank?
The bank continues to own the policy and typically keeps it in force — which is exactly why the 101(j) consent must disclose that coverage may continue after employment ends. Whether to retain it is an economic question about that policy's performance.
Can a bank surrender a BOLI policy?
It can, but surrender generally triggers ordinary income on the gain and forfeits the tax-free death benefit. Surrender charges may also apply in early years. BOLI should be purchased as a permanent allocation, not a liquidity reserve.
What is the difference between BOLI and COLI?
The structure is essentially the same; the owner differs. BOLI is bought by a bank and carries an additional layer of federal banking supervision. COLI is bought by an operating company and is governed by the tax rules without that supervisory overlay. Our side-by-side comparison works through the choice.
What is stable value protection?
In separate account BOLI, a stable value wrap smooths the reported book value of the underlying portfolio so the bank is not exposed to mark-to-market swings in earnings. The wrap provider is a distinct counterparty and belongs in the pre-purchase credit analysis alongside the carrier.
How often should a BOLI program be reviewed?
At least annually, covering carrier financial condition, actual versus expected performance, concentration against current Tier 1 capital, and continued alignment with the original business purpose. Many banks also commission an independent review every few years.
Can BOLI be restructured without triggering tax?
A 1035 exchange may permit moving from one contract to another without current recognition, but the analysis is fact-specific and interacts with 101(j) and the transfer-for-value rules. A wholesaler's illustration is not a substitute for that analysis.
Time is the only asset that cannot be replaced. In the world of high-level finance, whether you are running a regional bank or a multi-state corporation, you know that a missed opportunity today translates into a massive liability tomorrow. You’ve worked hard to build your organization, to hire the right people, and to protect your bottom line. But often, the very tools designed to safeguard your future, Corporate Owned Life Insurance (COLI) and Bank Owned Life Insurance (BOLI), become stagnant because of a "set it and forget it" mentality.
Are you absolutely certain your current portfolio is actually working for you, or is it just sitting there? Does your executive benefits strategy still align with the goals you set five years ago?
At Schiff Executive Benefits, we believe in a "reverse engineering" approach. We don't start with a product; we start with your desired outcome. Whether you’re looking to offset benefit costs, secure "golden handcuffs" for key talent, or fund a buy/sell arrangement, your portfolio needs to be precise.
Here are the 7 most common mistakes we see in COLI and BOLI portfolios and, more importantly, how you can fix them.
1. Treating Your Portfolio as a "Static" Asset
The market moves. Regulations shift. Tax codes evolve. Yet, many corporations and banks treat their life insurance portfolios like a dusty file in a cabinet. A common misperception is that BOLI or COLI is illiquid or unchangeable. In reality, these are dynamic financial instruments.
If you haven't reviewed your portfolio in the last 24 months, you are likely missing out on repricing opportunities or better-performing crediting rates. Market conditions change, and a portfolio requires periodic review to identify upgrade opportunities. Just as you wouldn't ignore your equity portfolio or your loan book, you cannot ignore your COLI/BOLI holdings.
2. Neglecting 101(j) and 409A Compliance
Compliance isn't just a box to check; it’s the foundation of your tax-advantaged status. Under IRC Section 101(j), if you don’t follow specific notice and consent requirements before the policy is issued, the death benefit, which should be tax-free, could suddenly become taxable income.
Similarly, for corporations using nonqualified deferred compensation (NQDC) plans, the shadow of Section 409A is always present. A single mistake in how your plan is structured or how the COLI informally funds it can lead to immediate taxation and 20% penalties for your key executives.
The Fix: Conduct a comprehensive audit of your documentation. Do you have the signed consents? Is your plan document 409A compliant? If you're unsure, it’s time to bring in our team to look under the hood.
3. Ignoring Credit Quality and Concentration Risk
We’ve all seen what happens when an organization puts too many eggs in one basket. In a BOLI environment, credit quality is paramount. Many providers pass along data from insurance carriers without truly validating it. Are you monitoring the financial health of the carrier? Are you diversified across multiple carriers to mitigate risk?
A healthy portfolio requires in-depth insurance carrier analysis. At Schiff Executive Benefits, we help you look beyond the marketing materials to the actual solvency and commitment of the carrier to the BOLI/COLI market.
Suggested prompt: A professional, high-end close-up of a hand reviewing a financial spread sheet with a glass of water on a polished wooden desk, warm natural lighting.
4. Failing to Link the Portfolio to Executive Retention
Why do you have these policies in the first place? For many of our clients, the goal is "Full Cost Recovery" of executive benefit plans. However, if your executive retention strategies are disconnected from your portfolio performance, you aren’t maximizing your "Ownership Feel."
Are you using Split Dollar arrangements? Are you leveraging the portfolio to create a "Golden Handcuff" effect that makes it impossible for your competitors to poach your top talent? If your portfolio is just a line item on the balance sheet and not a tool for talent management, you’re missing half the value.
5. Underestimating the Power of ESOP Integration
For partnerships and private corporations, Employee Stock Ownership Plans (ESOPs) are a powerful way to align employee interests with company growth. However, ESOPs create unique liquidity needs, especially when it comes to repurchase obligations.
Mistake number five is failing to use COLI to "sprinkle in" liquidity for these obligations. By reverse-engineering your future cash flow needs, we can structure a COLI portfolio that grows tax-deferred, providing the cash exactly when the company needs to buy back shares from retiring employees.
6. Overlooking Buy/Sell and Succession Funding
What keeps you up at night? For many business owners, it’s the question of what happens to the firm if a partner passes away or becomes disabled. Many Buy/Sell arrangements are funded with outdated policies that don't account for the current valuation of the business.
If your business has grown (and we hope it has!), your 10-year-old policy is likely insufficient. You are essentially leaving your legacy to chance. We use a technical lens to ensure your Buy/Sell funding matches your current "dream value," ensuring a smooth transition for the remaining partners and the family of the deceased.
7. Lacking a "Team of Advisors" Approach
The most dangerous phrase in business is "I’ve got it covered." Managing a COLI/BOLI portfolio requires a blend of legal, tax, accounting, and insurance expertise. If your insurance agent doesn't understand the nuances of FASB accounting or the specific regulatory hurdles faced by banks, they aren't helping you, they're creating risk.
At Schiff Executive Benefits, we don't work in a vacuum. We collaborate with your existing CPAs and legal counsel to ensure that your Perfect Plan® is airtight from every angle.
The Path Forward: Reverse Engineering Your Success
The national debt is rising, market volatility is the new constant, and the "war for talent" is only getting more intense. In this environment, you cannot afford a mediocre portfolio. You need a strategy that is as sophisticated as the organization you’ve built.
Are you realizing the maximum after-tax yield on your assets? Is your plan structured to recover every dollar of cost, including the opportunity cost of the money?
If these questions give you pause, it’s okay. Most of our clients felt the same way before we began the "reverse engineering" process with them. They were looking for security and a guarantee that their hard work would translate into a lasting legacy.
We invite you to stop guessing and start knowing. Your professional legacy is too important to leave to "standard" industry practices. You deserve a plan that is built your way, with your goals as the blueprint.
Sit back, grab your coffee, and let’s have a conversation. Whether you want to dive deep into the technicalities of a 409A plan or just want a second set of eyes on your BOLI holdings, we are here to guide you through the uncertainty.
To hear more about our philosophy and see these strategies in action, check out The Perfect Plan® Podcast where we break down complex financial structures into actionable executive advice.
Schiff Executive Benefits provides specialized consulting. For specific legal or tax advice, please consult with your professional advisors. You can find our full disclosure here.







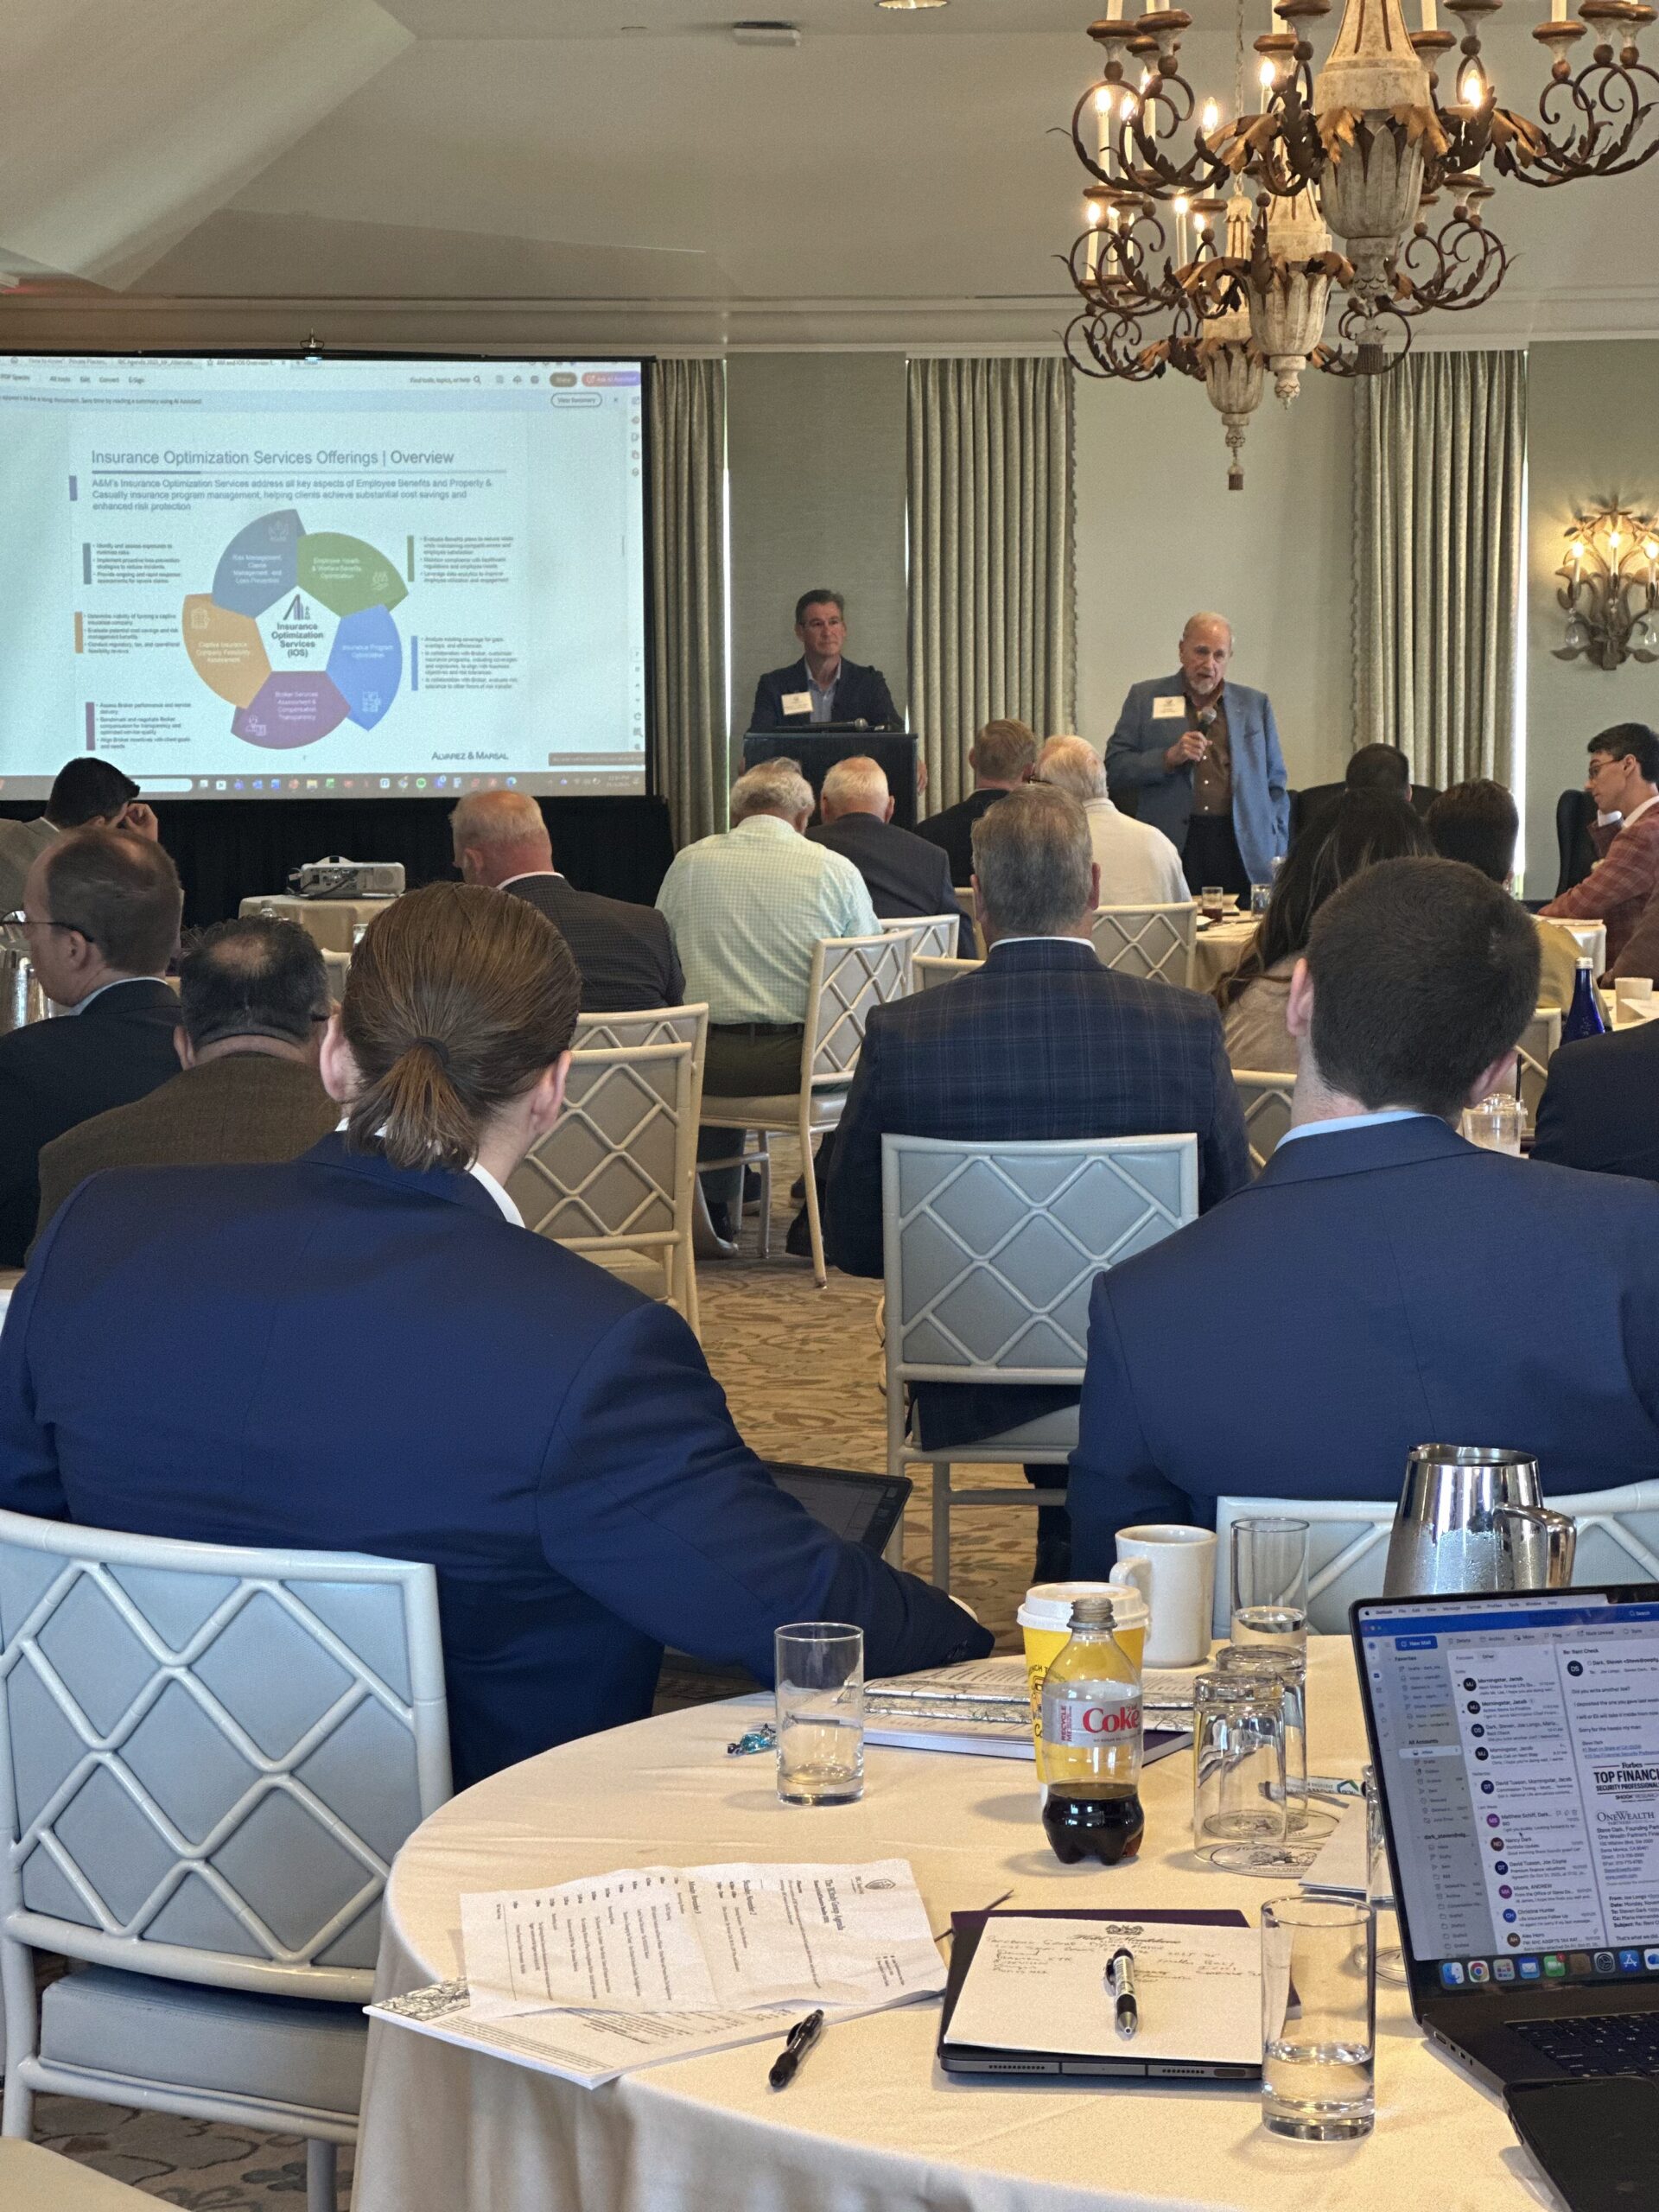 They say that the only constant in life is change, but in the world of high-stakes banking and executive leadership, the only constant is the relentless need for top-tier talent. Without the right people in the right seats, even the most storied financial institutions are just buildings with impressive vaults.