It has often been said that a man who has his health has a thousand dreams, but a man who does not has only one. For the high-achieving executive, the transition from a storied career into a hard-earned retirement is the ultimate "dream value." You have spent decades navigating market volatility, managing complex teams, and securing the future of your organization. But there is one variable that remains stubbornly outside of any spreadsheet: the unpredictable nature of long-term health.
The reality is that traditional retirement strategies often overlook the "What If" that keeps many leaders up at night: What if I run out of retirement money because of a long-term care event?
At Schiff Executive Benefits, we believe in Restoring Alignment and Retention. When it comes to protecting your most valuable human capital: and your own personal legacy: the choice between Long-Term Care (LTC) riders and standalone coverage isn't just a technical insurance decision. It is a strategic move to safeguard a lifetime of work.
The "What If" Problem: Why Long-Term Care is the Missing Piece
Most executive benefit packages are robust when it comes to life insurance, disability, and deferred compensation. However, the gap between "wealthy" and "secure" is often defined by long-term care coverage. A private room in an assisted living facility or 24-hour home care can easily exceed $150,000 a year in today's market: and those costs are only rising.
For the corporation, the question is equally pressing: How do you attract and retain senior talent when the competition is offering "The Perfect Plan®"? If your senior executives are worried about their personal solvency in the face of a health crisis, they aren't focused on the long-term vision of your company.
Standalone LTC Policies: The Traditional Specialist
Standalone long-term care insurance was once the gold standard. These policies are dedicated instruments designed for one thing: paying for care.
The Pros:
Customization: You can often dial in specific elimination periods, inflation protection percentages, and benefit durations.
Pure Focus: Every dollar of premium is directed toward the LTC benefit.
The Cons:
The "Use It or Lose It" Trap: This is the primary anxiety for many executives. If you pay premiums for twenty years and then pass away peacefully in your sleep without ever needing care, the insurance company keeps the premiums. For a high-net-worth individual, this feels like an inefficient use of capital.
Volatile Premiums: Many older standalone policies saw significant rate increases over the years, creating uncertainty in retirement budgeting.
Stringent Underwriting: Getting approved for a standalone policy can be a gauntlet of medical exams and history checks.
LTC Riders on Life Insurance: The Integrated Alternative
In recent years, we have seen a massive shift toward "linked-benefit" or "hybrid" strategies. This usually involves adding an LTC rider to a permanent life insurance policy, often structured as Corporate Owned Life Insurance (COLI).
How It Works
Instead of a separate policy, the LTC benefit is "accelerated" from the death benefit. If you need care, you tap into the life insurance policy's face value. If you don't need care, your beneficiaries receive the full death benefit.
The Benefits of the Rider Approach:
Efficiency: Your premium is never "wasted." It either pays for care or it pays a death benefit.
Simplified Underwriting: When these plans are implemented as part of a deferred compensation or executive benefit program, we can often negotiate simplified or "guaranteed issue" underwriting for a group of executives. This is a massive win for senior leaders who might have minor health hiccups that would disqualify them from standalone coverage.
When we sit down with a board of directors or a business owner, the conversation usually turns to the bottom line. How can the company afford to provide such a high-tier benefit?
The answer lies in the structure of the COLI. If structured correctly, the employer can achieve full cost recovery. The company pays the premiums and remains the beneficiary of the policy. The executive receives the long-term care protection as a benefit of their employment. When the executive eventually passes away (long after they have retired), the company receives the death benefit tax-free, which can reimburse the company for every dollar of premium paid, plus a rate of return.
This transforms an "expense" into an "informal funding vehicle." It allows the company to offer a world-class benefit that helps attract and retain top talent without permanently depleting the balance sheet.
Comparing the Strategies: At a Glance
Feature
Standalone LTC
LTC Rider (Hybrid/COLI)
Primary Purpose
Long-term care only
Death benefit + Long-term care
Premium ROI
None if care is never needed
Guaranteed (either care or death benefit)
Underwriting
Strict/Medical
Often Simplified for Executive Groups
Cost Recovery
None for employer
Possible full recovery for employer
Flexibility
High customization of care
Integrated into broader financial plan
Compliance and Company Culture
Choosing the right strategy isn't just about the math; it’s about alignment. Does the plan reflect your company culture? If you pride yourself on being a "family-first" or "legacy-focused" organization, providing a benefit that ensures an executive won't be a burden to their family is a powerful message.
However, you must ensure compliance. Whether you are dealing with 409A plans or complex buy/sell arrangements, the integration of LTC coverage must be handled by experts.
At Schiff Executive Benefits, we guide you through the regulatory environment, ensuring that the consent forms are in order and that the plan is communicated clearly to the participants.
The Path Forward: Which is Best for You?
So, how do you choose?
If you are a solo practitioner or a small business owner with no interest in permanent life insurance, a standalone policy might still hold some appeal for its pure-play simplicity.
However, for the majority of corporations and partnerships looking to solve for the "5 What Ifs," the LTC Rider/Hybrid approach is usually the superior choice. It addresses the senior executive retirement/replacement cost efficiency, provides a guaranteed return on premium, and serves as a formidable tool for retention.
Are you worried that your current retirement strategy is one health crisis away from collapse? Are you concerned that your top talent might be lured away by a competitor offering more security?
These are the questions that define your professional legacy. You don't have to navigate these "unstable" financial environments alone. Building it your way means having a team of advisors who understand that your business and your personal life are inextricably linked.
We invite you to take a breath, sit back, grab your coffee, and let’s look at your current plan. Is it truly The Perfect Plan®? If not, we are here to help you find the alignment you deserve.
Come join us at Schiff Executive Benefits. Let’s make sure your "thousand dreams" remain intact, no matter what the future holds.
Bank-Owned Life Insurance (BOLI) is life insurance a bank purchases on the lives of its officers and directors, where the bank owns the policy, pays the premium, and is the beneficiary. Banks use BOLI as a tax-advantaged balance sheet asset to offset the rising cost of employee benefit programs. Cash surrender value grows tax-deferred, death proceeds are generally received income-tax-free, and the resulting yield typically exceeds what the same capital would earn in taxable short-term instruments of comparable credit quality.
BOLI is permissible for national banks under 12 U.S.C. 24 (Seventh) and is governed by the 2004 Interagency Statement on the Purchase and Risk Management of Life Insurance. The Statement sets supervisory guidelines rather than statutory caps: aggregate cash surrender value is generally expected to stay within 25% of Tier 1 capital, with exposure to any single carrier generally within 15%. It also calls for a documented pre-purchase analysis.
The same structure bought by an operating company is called COLI; bought by an insurance carrier, iCOLI.
A bank is only as strong as its community, and its community is only as strong as the leaders who serve it. In the financial world, stability is the cornerstone of trust. Yet, many bank executives find themselves facing an unstable paradox: how do you maintain a competitive edge and protect your balance sheet while simultaneously funding the escalating costs of employee benefits?
If you are leading a financial institution today, you are likely wrestling with the "What Ifs" that keep even the most seasoned presidents awake at night. What if your top talent is lured away by a larger competitor? What if the cost of your pension and health plans continues to outpace your portfolio’s yield? What if your senior executive retirement costs become a drag on your regulatory capital?
To find the answer, we look toward a strategy utilized by over 65% of banks in the United States. It is a tool designed for Restoring Alignment and Retention: Bank-Owned Life Insurance (BOLI).
What is BOLI, and Why Does It Matter?
At its most fundamental level, Bank-Owned Life Insurance is a life insurance policy purchased by a bank on the lives of its key employees: usually officers and directors. The bank is the owner and the beneficiary of the policy.
While the term "insurance" is in the name, for a financial institution, BOLI is primarily a sophisticated investment and a Tier 1 asset. The bank pays a premium (often a single lump sum), and the cash value of the policy grows over time.
Why is this so popular? Because it solves the problem of "lazy capital." Instead of holding assets in low-yield taxable instruments, banks move capital into a tax-advantaged BOLI structure where the growth can offset specific liabilities. It is a method of taking a "dead" expense: like the cost of executive benefits: and turning it into a high-performing asset.
The Economic Reality: After-Tax Yield and Efficiency
In a world where interest rates are volatile and traditional fixed-income yields are often squeezed by taxes, BOLI stands out as a beacon of efficiency.
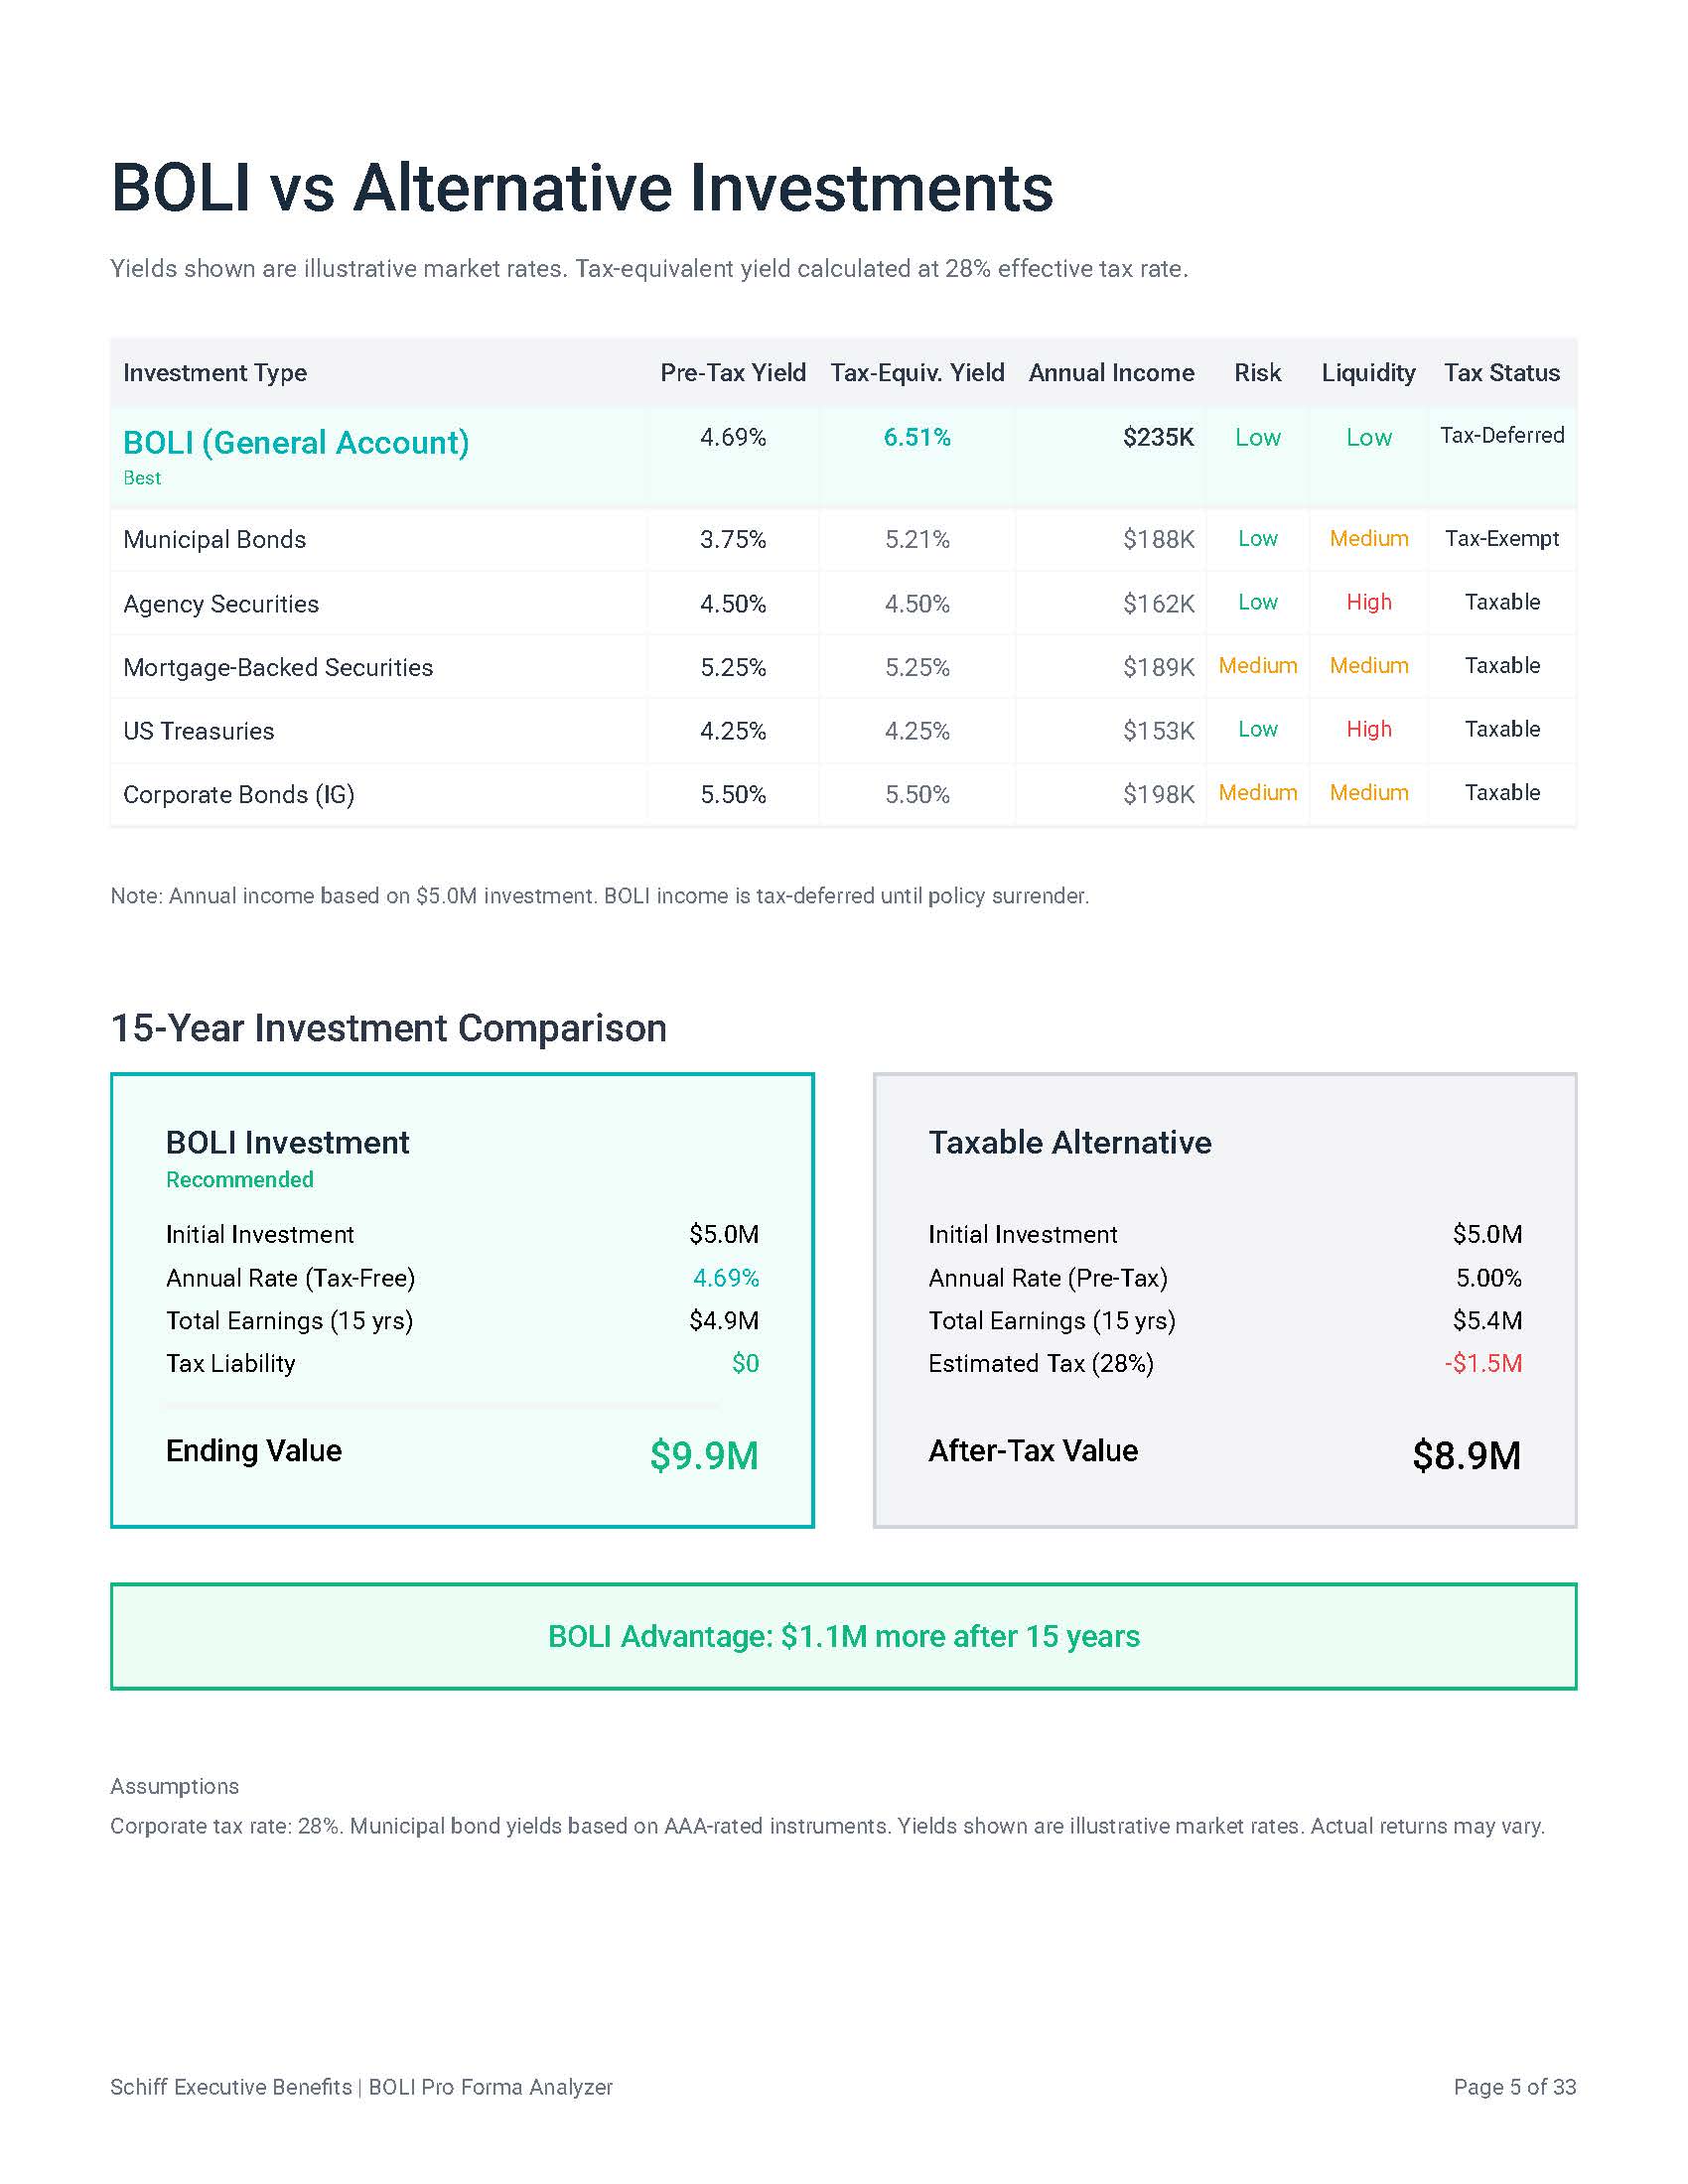
When you compare BOLI to alternative fixed-income investments: such as municipal bonds, agency securities, or Treasuries: the difference is often staggering. Because the cash value growth within a BOLI policy is tax-deferred (and tax-free if held until the death of the insured), the "tax-equivalent" yield is significantly higher than what a bank can typically earn elsewhere.
As shown in our proprietary BOLI Pro Forma Analyzer, a $5 million investment in BOLI can provide a tax-equivalent rate that significantly outperforms corporate bonds or MBS portfolios. This isn't just about "beating the market"; it’s about generating the necessary cash flow to fund Non-Qualified Deferred Compensation (NQDC) and other executive carve-outs that are essential for retention.
Offsetting the Rising Cost of Talent
What is the true cost of losing your CFO or a high-performing VP of Lending? It isn't just the recruiter's fee. It is the loss of institutional knowledge, the disruption of client relationships, and the significant expense of "buying" a replacement in a competitive market.
Most banks use BOLI to recover the costs of:
Post-retirement medical benefits
Supplemental Executive Retirement Plans (SERPs)
Group term life insurance premiums
401(k) matching and pension obligations
By utilizing BOLI, you are essentially creating an informal "sinking fund" to pay for these future obligations. It allows you to offer "ownership-like" benefits without actually diluting your bank’s equity. This is how you retain your key people while keeping the bank’s financial health intact.
Regulatory Compliance: The Tier 1 Advantage
One of the most frequent questions I get from Bank Presidents is: "How will the regulators view this?"
The answer is found in the Interagency Statement on the Purchase and Risk Management of Life Insurance. BOLI is recognized as a permissible investment for banks, provided it is managed within specific guidelines. Most notably, the Office of the Comptroller of the Currency (OCC) and other regulators generally allow BOLI holdings up to 25% of a bank’s Tier 1 capital.
Because BOLI is a high-quality asset backed by highly-rated insurance carriers, it provides a stable foundation for your balance sheet. Unlike securities portfolios, BOLI cash values are typically not subject to the "mark-to-market" volatility that can plague a bank during periods of rising interest rates. This makes it a preferred tool for managing earnings consistency.
The Human Element: Survivor Income as an Incentive
While the bank is the primary beneficiary, BOLI can also be structured to provide a powerful direct benefit to the insured executives.
Through "split-dollar" arrangements, a portion of the death benefit can be directed to the executive’s family. This provides "pre-retirement survivor income": a massive incentive for a key leader who wants to ensure their family is protected while they focus on growing your institution.
Think about the peace of mind you are offering your top officers. You aren't just giving them a salary; you are giving them a legacy. When you align the bank’s financial goals with the personal security of its leaders, you create an environment where talent stays for the long haul.
Why the "Carrier Agnostic" Approach Matters
The BOLI market is nuanced. There are different types of products: General Account, Hybrid Account, and Separate Account: each with its own risk profile and yield potential.
At Schiff Executive Benefits, we believe that your bank deserves a solution tailored to your specific capital structure and risk appetite, not a "product of the month." We operate as independent brokers, which means we work with all the major, highly-rated carriers to find the right fit for you.
Our process, which we call The Perfect Plan®, involves:
A Deep-Dive Needs Analysis: We look at your current benefit liabilities and capital ratios.
Carrier Evaluation: We vet the financial strength and historical performance of potential insurance partners.
Pro Forma Modeling: We show you exactly how BOLI will impact your EPS and ROA over 10, 20, and 30 years.
Implementation and Administration: We handle the heavy lifting, from board education to ongoing compliance monitoring.
The Point of No Return: Why Wait?
Every day that your bank's benefit liabilities grow while your assets remain in taxable, low-yield accounts is a day of lost opportunity. Economic shifts are coming, and the cost of talent is not going down.
Are you prepared for the next five years? What if your replacement cost for your senior team increases by 20%? What if your 401(k) matches become a burden on your margins?
BOLI is not just a financial product; it is a strategic shield. It provides a calm, structured way out of the anxiety of rising costs. It allows you to focus on what you do best: banking: while we ensure your "human capital" is fully funded and protected.
Join Us for a Deeper Conversation
Navigating the complexities of executive benefits and BOLI doesn't have to be a solo journey. Whether you are looking to implement your first BOLI plan or you want a review of your existing holdings to ensure they are performing as promised, we are here to help.
Sit back, grab your coffee, and let's discuss how we can bring stability back to your executive suite. Building your bank’s legacy should be a realization of your dream value, not a source of stress.
Come join us and discover how The Perfect Plan® can help you achieve alignment and retention.
A BOLI purchase is a reallocation of existing bank assets, not new spending. The bank moves capital from a taxable holding — typically short-duration securities or fed funds — into an insurance contract on the lives of consenting officers.
The bank identifies a legitimate business need, usually the cost of an existing or planned benefit obligation.
It performs and documents a pre-purchase analysis covering need, amount, carrier selection, product characteristics, and risk.
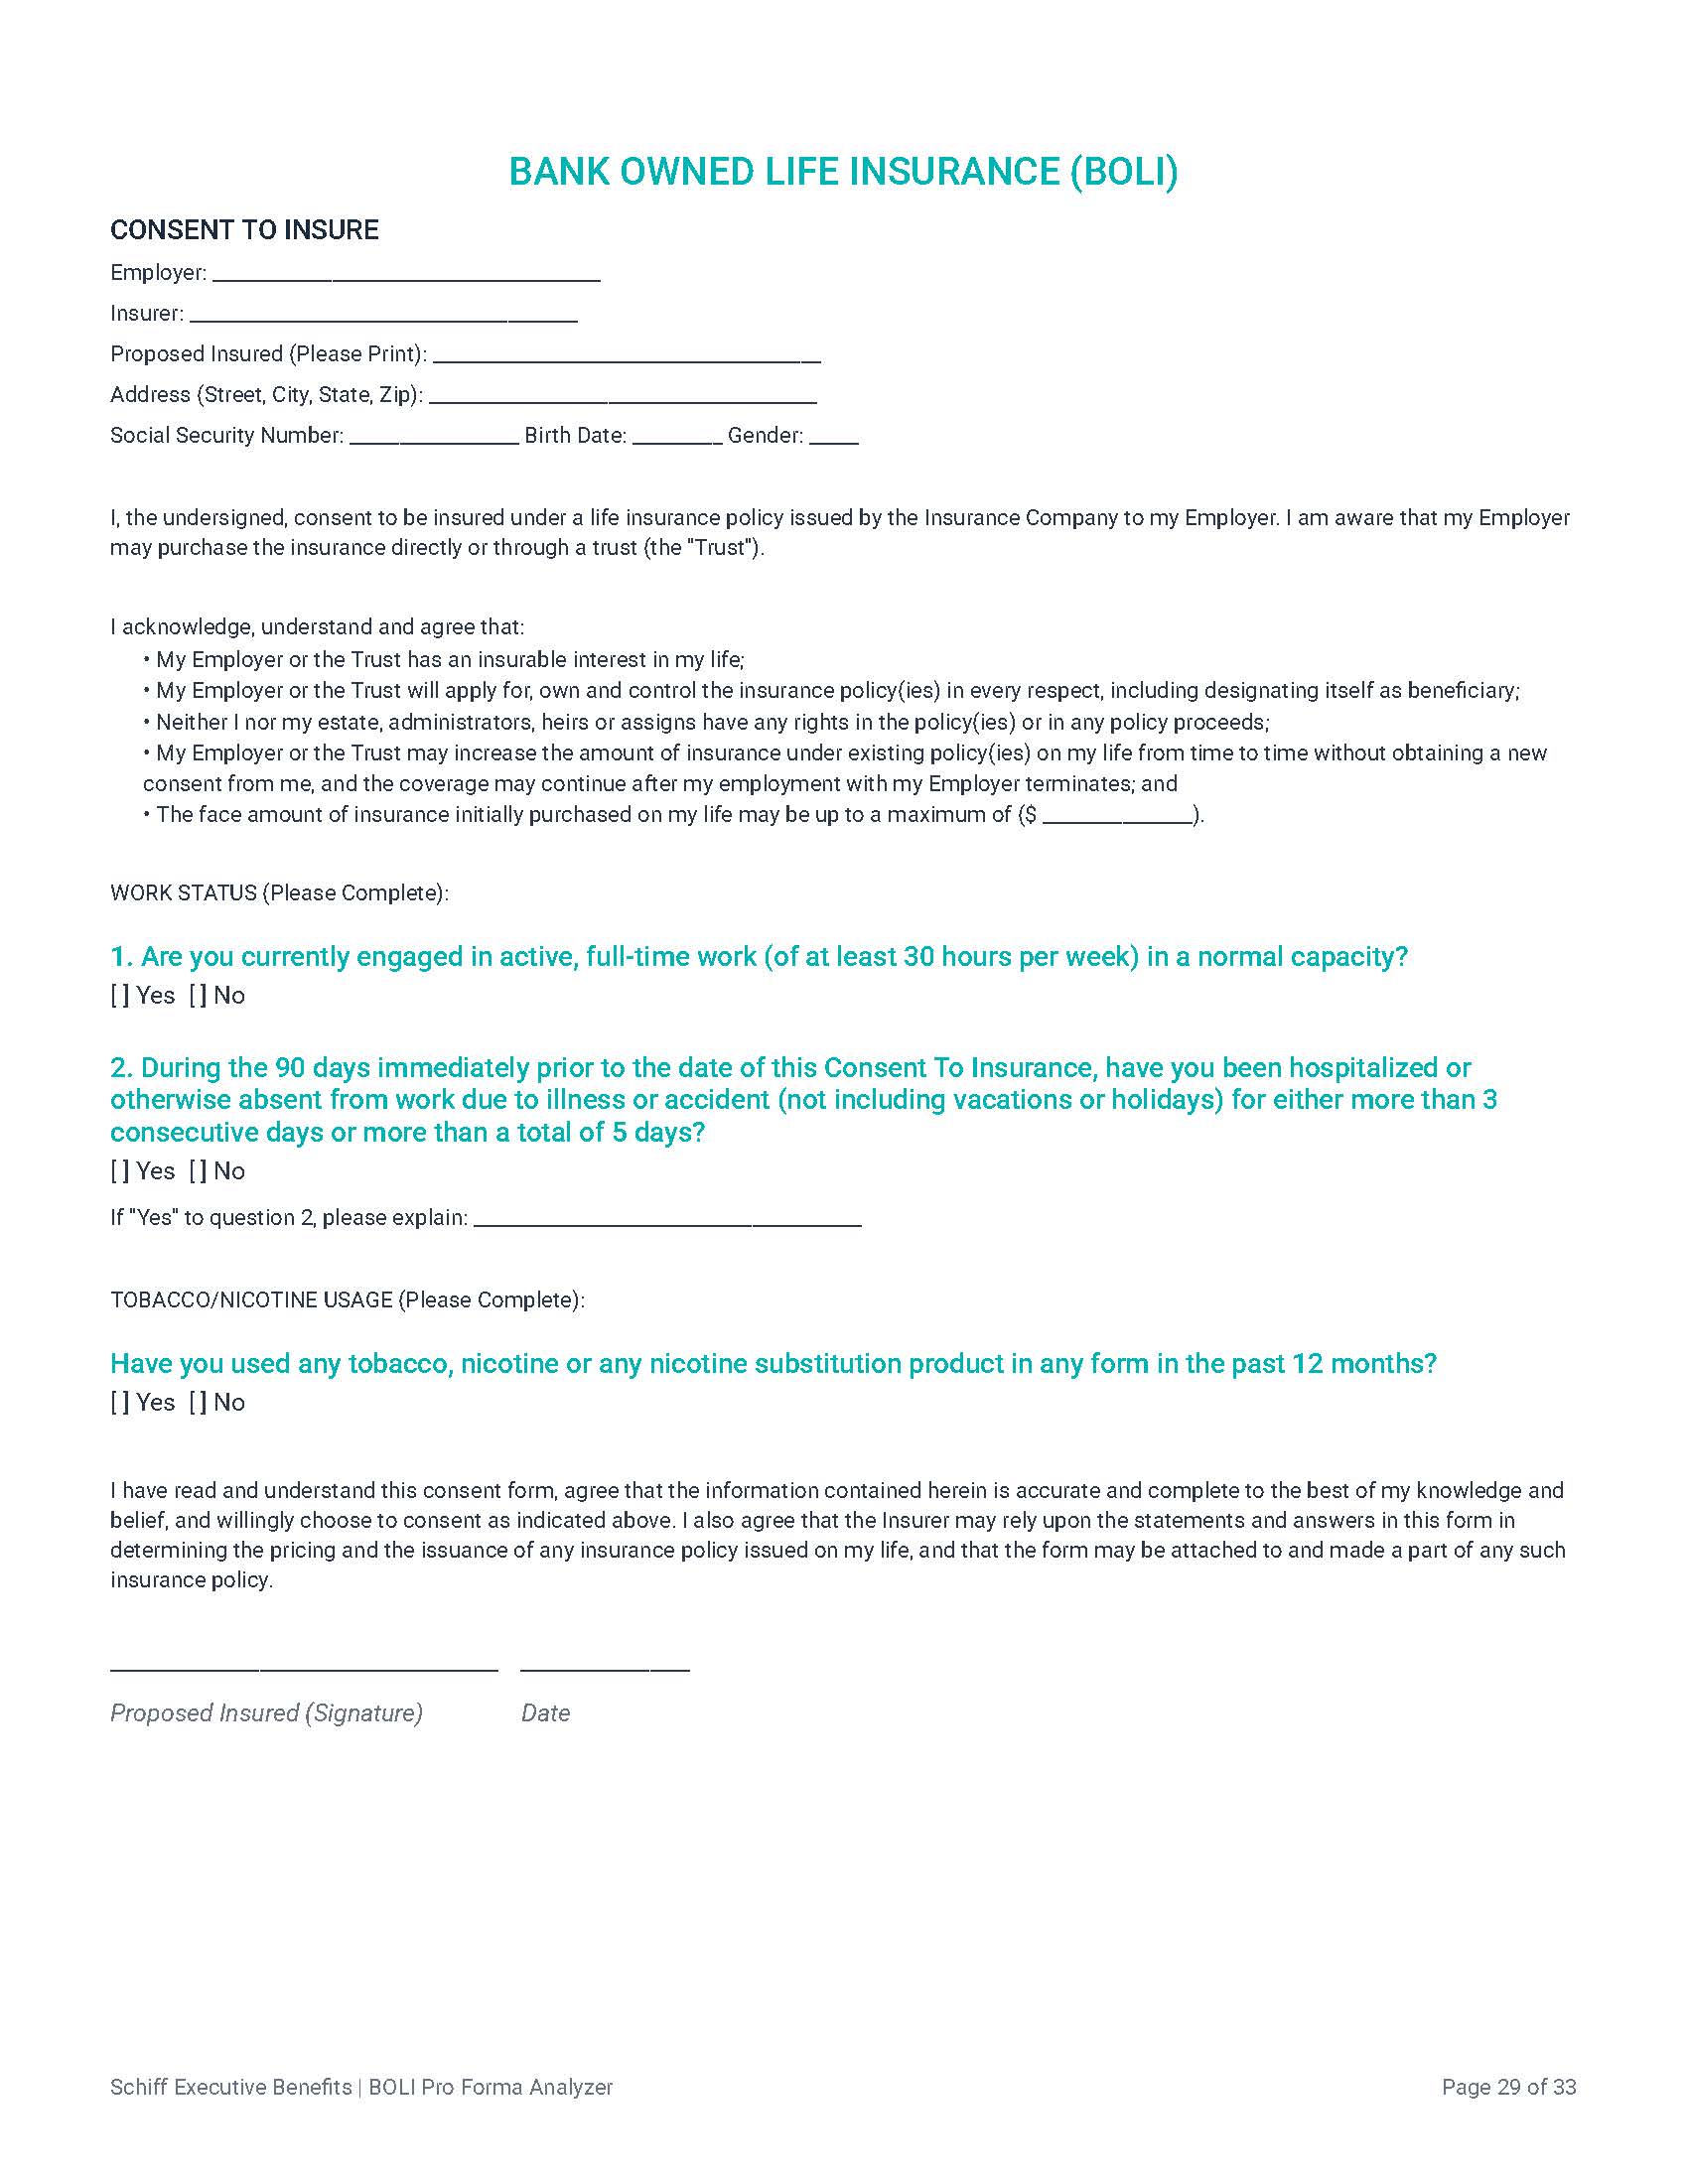
Eligible insureds provide written notice and consent before any policy is issued.
The bank pays a single premium, or a limited series, and records the cash surrender value as an asset.
Cash value accumulates tax-deferred at the credited rate, and the increase is recognized in non-interest income.
At the insured's death, the carrier pays the bank; proceeds above carrying value are generally income-tax-free.
The reason this works economically is the absence of current tax on the inside build-up. A taxable instrument yielding the same nominal rate is worth materially less after tax. That spread is the entire case for BOLI, and it is why the comparison must always be run against the specific alternative the bank would otherwise hold.
BOLI Is a Hold-to-Maturity Asset
Surrendering a policy generally triggers ordinary income on the gain and forfeits the tax-free death benefit — the two features that justified the purchase. BOLI should therefore be underwritten as a permanent allocation. A bank that may need that liquidity inside ten years is not a good candidate, and any presentation that treats cash value as a liquidity source deserves scrutiny.
The Three Account Types
Product selection drives most of the risk difference between two otherwise identical BOLI programs.
General Account — assets sit in the carrier's general account. The carrier declares a credited rate, usually with a guaranteed floor. Simplest to administer, and the bank takes direct credit exposure to the carrier. Suits smaller programs and banks that prefer a declared rate over transparency.
Separate Account — assets are held in a segregated account, insulated from the claims of the carrier's general creditors. Returns track the underlying portfolio, so a stable value protection wrapper is generally used to smooth book value. More transparent, more moving parts, and the wrap provider becomes its own counterparty to diligence.
Hybrid Account — a general account chassis with some separate-account characteristics, typically better rate transparency than pure general account without the full complexity of a wrapped separate account.
Institutional Indexed Universal Life — crediting tied to an index formula subject to caps and floors. Requires the board to understand exactly how the crediting method behaves in a flat or negative index year.
There is no universally correct answer. The right structure follows from the bank's size, its credit appetite, its comfort with mark-to-market mechanics, and how much administrative capacity it has.
Aggregate cash surrender value of all life insurance holdings is generally expected to remain within 25% of Tier 1 capital, with exposure to any single carrier generally within 15%. These are supervisory guidelines rather than statutory caps — a bank exceeding them is not automatically in violation, but is expected to document why the concentration is prudent and how it is managed. In practice, examiners treat an undocumented excess far more harshly than a well-reasoned one.
The Pre-Purchase Analysis
This is where most criticized BOLI programs fail, and the failure is almost always documentation rather than economics. A defensible analysis addresses:
The specific business need and the benefit obligation being offset
The amount of insurance and how that amount was derived
Vendor and carrier selection, including financial strength and the basis for choosing among carriers
Product characteristics, including crediting methodology and surrender charges
Alternatives considered and why BOLI was preferred
The full risk assessment — liquidity, credit, interest rate, operational, compliance, reputation, and price risk
Evidence of board or committee review and approval before purchase
The analysis must exist before the purchase. Reconstructing one after an examiner asks is not the same thing, and examiners can tell the difference.
Ongoing Risk Management
Approval at purchase does not end the obligation. Regulators expect periodic review — at minimum annually — covering carrier financial condition, policy performance against expectations, continued compliance with concentration guidance, and confirmation that the original business purpose still holds. Programs that were bought correctly and then left unmonitored for a decade are a recurring examination finding.
IRC 101(j): Notice and Consent
BOLI is employer-owned life insurance, so IRC 101(j) applies with full force. Since the Pension Protection Act of 2006, death proceeds are taxable to the bank above premiums paid unless, before the policy is issued, the insured has been notified in writing of the intent to insure and the maximum face amount, has consented in writing to coverage that may continue after employment ends, and has been informed the bank will be a beneficiary.
The insured must also fall within a qualifying category, which in a banking context generally means directors and highly compensated employees as defined in the Code. The bank files Form 8925 annually with its return.
Two situations create most of the exposure. The first is acquisition: banks that grow by merger routinely inherit policies without inheriting the consent files. The second is time — programs bought fifteen years ago by people who have since retired, where nobody has verified that the documentation still exists. Both are worth auditing before a claim rather than during one.
Accounting Treatment
An investment in life insurance is reported at the amount realizable under the contract at the balance sheet date, which in practice means cash surrender value net of any surrender charge the bank would actually incur. Periodic increases flow through non-interest income. Death proceeds above carrying value are recognized when realizable.
Two consequences worth raising with your CFO before the first premium: the asset recorded in year one is cash surrender value, not premium paid, and in some product designs those differ meaningfully at the outset. And the carrier's annual statement becomes audit support, so the reporting relationship matters as much as the crediting rate.
What BOLI Actually Funds
BOLI is informal financing, not funding. The policy is a general asset of the bank; it is not pledged, segregated, or promised to any participant. Most programs are used to offset:
Split dollar and endorsement arrangements providing survivor income to officers' families
General group benefit costs — health, disability, and post-retirement obligations
Any plan document or officer communication implying the policy secures the benefit creates a constructive receipt problem and undermines the arrangement. The promise and the asset must stay legally separate.
Where BOLI Programs Go Wrong
Missing 101(j) consent — the most expensive failure, and almost always found at claim rather than at purchase.
Thin or backdated pre-purchase analysis — the most common examination criticism.
Carrier concentration drift — a program that was inside the 15% single-carrier guideline at purchase can breach it as capital changes or as one carrier's block outperforms.
Orphaned programs — the originating producer is gone, nobody reviews performance, and the crediting rate has quietly reset.
Product mismatch — separate account complexity sold to a bank without the staff to administer it, or a general account placement with a carrier whose financial strength has since deteriorated.
Free Download: Bank-Owned Life Insurance (BOLI) Guide
Tell us where to send it. The PDF opens right away, and we will email you a copy.
Frequently Asked Questions About BOLI
What is BOLI in banking?
BOLI is life insurance owned by a bank on the lives of its officers and directors, held as a balance sheet asset to offset employee benefit costs. The bank pays the premium, owns the cash value, and receives the death benefit.
Is BOLI legal for banks?
Yes. National banks may purchase and hold life insurance under 12 U.S.C. 24 (Seventh) in connection with employee compensation and benefit plans, key person coverage, and related purposes. State-chartered institutions operate under comparable state authority. The purchase must address a legitimate business need.
How much BOLI can a bank own?
Supervisory guidance generally expects aggregate cash surrender value within 25% of Tier 1 capital, and within 15% for any single carrier. These are guidelines requiring documented justification if exceeded, not hard statutory ceilings.
Are BOLI premiums tax deductible?
No. Premiums on a policy where the bank is a beneficiary are not deductible. The tax advantage sits in the tax-deferred accumulation and the generally tax-free death benefit.
What happens to BOLI when an insured officer leaves the bank?
The bank continues to own the policy and typically keeps it in force — which is exactly why the 101(j) consent must disclose that coverage may continue after employment ends. Whether to retain it is an economic question about that policy's performance.
Can a bank surrender a BOLI policy?
It can, but surrender generally triggers ordinary income on the gain and forfeits the tax-free death benefit. Surrender charges may also apply in early years. BOLI should be purchased as a permanent allocation, not a liquidity reserve.
What is the difference between BOLI and COLI?
The structure is essentially the same; the owner differs. BOLI is bought by a bank and carries an additional layer of federal banking supervision. COLI is bought by an operating company and is governed by the tax rules without that supervisory overlay. Our side-by-side comparison works through the choice.
What is stable value protection?
In separate account BOLI, a stable value wrap smooths the reported book value of the underlying portfolio so the bank is not exposed to mark-to-market swings in earnings. The wrap provider is a distinct counterparty and belongs in the pre-purchase credit analysis alongside the carrier.
How often should a BOLI program be reviewed?
At least annually, covering carrier financial condition, actual versus expected performance, concentration against current Tier 1 capital, and continued alignment with the original business purpose. Many banks also commission an independent review every few years.
Can BOLI be restructured without triggering tax?
A 1035 exchange may permit moving from one contract to another without current recognition, but the analysis is fact-specific and interacts with 101(j) and the transfer-for-value rules. A wholesaler's illustration is not a substitute for that analysis.
It is often said that a business is only as strong as the foundation upon which it is built. You have spent decades pouring your sweat, late nights, and creative energy into your company. You have survived market crashes, global shifts, and the daily grind of management. But here is an undeniable truth: building a business is a labor of love, yet leaving one should not be a labor of grief.
For many business owners, the "exit" feels like a distant shore. However, the reality of business succession is that it often happens when we least expect it. Whether it is a sudden health crisis or a partner deciding to walk away, the stability of your legacy depends entirely on a document that is likely sitting in a dusty drawer: your buy-sell agreement.
Are you certain that document will protect your family? Does it guarantee that you won't end up in business with a widow? Or worse, does it inadvertently hand over your hard-earned equity to the IRS?
At Schiff Executive Benefits, our mission is Restoring Alignment and Retention. We believe that a plan is only as good as its execution. Today, let’s walk through the common pitfalls that keep business owners up at night and how you can secure your professional legacy.
The "What If" Reality Check
We often ask our clients five core "What If" questions. Two of them are particularly relevant here:
What if you end up in business with your partner’s spouse?
What if you need a business buy-out tomorrow but don’t have the cash?
If you don't have a properly structured and funded agreement, these aren't just hypothetical scenarios: they are impending financial disasters. A buy-sell agreement is essentially a "business will." It dictates who can buy the departing owner's share, at what price, and where the money will come from. Without it, or with a flawed one, you are inviting litigation and chaos into your boardroom.
Mistake #1: The Ownership Trap (Redemption vs. Cross-Purchase)
One of the most frequent business owner issues we see involves the choice between an Entity-Purchase (Redemption) agreement and a Cross-Purchase agreement. While both aim to solve the same problem, their tax and legal implications are worlds apart.
The Redemption Model
In a redemption or entity-purchase agreement, the business itself buys the life insurance policy on each owner. When an owner passes away, the company receives the death benefit and uses it to buy back the shares.
The Pro: It is simple. Only one policy per owner is needed.
The Con: The surviving owners do not receive a "step-up" in tax basis. If you eventually sell the company, your tax bill could be significantly higher because your cost basis in the shares remained the same, even though you now own a larger percentage of the company.
The Cross-Purchase Model
In a cross-purchase agreement, the owners buy policies on each other.
The Pro: When a partner dies, you receive the insurance proceeds personally (tax-free) and use them to buy the deceased partner’s shares. This gives you a "step-up" in basis, potentially saving you millions in future capital gains taxes.
The Con: It can become administratively complex if there are many partners. If you have four partners, you might need 12 separate policies to cover everyone.
Which is right for you? There is no one-size-fits-all answer. Often, we utilize a cross-purchase partnership or a "Trusteed" cross-purchase to simplify the administration while retaining the tax benefits. Failing to analyze this choice is a mistake that often isn't discovered until it's too late to fix.
Mistake #2: The IRC 101(j) Compliance Trap
This is the "Life Insurance Warning" that many generalist advisors miss. Under Internal Revenue Code Section 101(j), if a business owns a life insurance policy on an employee (including owner-employees), specific notice and consent requirements must be met before the policy is issued.
If you fail to comply with 101(j), the death benefit: which you expected to be tax-free: could be treated as taxable income. Imagine needing $5 million to buy out a partner, receiving the check, and then realizing the IRS wants 37% of it.
This is what we call the "Employer-Owned Life Insurance" trap. Compliance requires:
Informing the insured in writing that the employer intends to insure their life.
Disclosing the maximum face amount for which the employee could be insured.
Obtaining written consent from the employee.
At Schiff Executive Benefits, we specialize in navigating these regulatory waters to ensure your COLI (Corporate Owned Life Insurance) strategies remain a source of security, not a tax liability.
Mistake #3: Using a Stale Valuation
When was the last time you valued your company? If your buy-sell agreement uses a fixed dollar amount from 2018, you are playing a dangerous game.
If the business has grown, the surviving partners may be getting a "steal," leaving the deceased partner’s family under-compensated and likely to sue. If the value has dropped, the company might be forced to overpay, potentially bankrupting the business.
We recommend a dynamic valuation formula or a requirement for an annual appraisal. Your legacy deserves an accurate price tag. Business values fluctuate; your agreement must be agile enough to keep pace.
Mistake #4: The Funding Gap
A buy-sell agreement without funding is just a piece of paper with good intentions. How will you come up with the cash to buy out a partner?
Cash on hand? Most businesses don't keep millions in idle cash.
A bank loan? Banks are often hesitant to lend to a company that just lost a key partner.
Installment payments? This puts a massive strain on future cash flow and leaves the departing family at risk if the business fails.
This is where life insurance buy/sell agreements shine. Life insurance provides immediate, tax-free liquidity at the exact moment it is needed. It creates the "certainty" in an uncertain time. By using COLI or personal policies, you ensure that the surviving partners keep the business and the departing family gets their fair value immediately.
The Power of The Perfect Plan®
Navigating these complexities requires more than just an insurance agent; it requires a team of advisors who understand the intersection of law, tax, and corporate finance. This is the philosophy behind The Perfect Plan®.
We don't just sell policies; we help you engineer a succession strategy that stands the test of time. We look at the "point of no return": the moment when a triggering event occurs: and we work backward to ensure every piece of the puzzle is in place today.
Have you considered what happens if a partner becomes disabled rather than passing away? Most buy-sell agreements are silent on disability, yet the statistical likelihood of long-term disability is far higher than premature death. Our team at Schiff Executive Benefits looks at the holistic picture to ensure no "What If" goes unanswered.
Take the Next Step
The unstable nature of today's economic environment means that waiting "until next year" to review your succession plan is a risk you cannot afford. Economic shifts and tax law changes are happening at an accelerated pace.
Are you making these common mistakes?
Is your agreement funded?
Is it 101(j) compliant?
Does it offer a step-up in basis?
Is the valuation current?
If you aren't 100% sure of the answers, it's time for a professional review.
Sit back, grab your coffee, and let’s have a conversation about your professional legacy. We invite you to join us for a consultative review where we can explore how to bring your buy-sell agreement into alignment with your current goals.
Don't let the foundation you've built crumble because of a technicality. Let's work together to ensure your business continues to thrive, your partners stay protected, and your family is provided for: exactly the way you intended.
Restoring Alignment and Retention. It’s not just our tagline; it’s our promise to you.
Ready to secure your future? Contact us today to learn more about how we can help you implement The Perfect Plan®.
There is a universal truth in the world of commerce that every seasoned entrepreneur eventually realizes: It is not what you make; it is what you keep. You have spent years, perhaps decades, pouring your sweat, late nights, and capital into building a successful enterprise. You’ve navigated market volatility, managed complex teams, and scaled your vision into a reality. Yet, when you look at your personal balance sheet compared to the company’s revenue, a frustrating disconnect often appears.
Why is it that the business can afford top-tier equipment, expansive marketing budgets, and plush office spaces, but when you try to move that same capital into your personal pocket, the IRS stands at the gate demanding a 30%, 40%, or even 50% "toll"?
If you feel like you are "business rich" but "personally capped," you aren't alone. Most business owners are stuck in the traditional qualified plan trap. You maximize your 401(k), perhaps add a profit-sharing component, and then... you hit a wall. Federal limits dictate how much you can save, and as a high-earner, those limits are often a drop in the bucket compared to the lifestyle you’re building or the legacy you want to leave.
What if there was a way to use corporate dollars: money already sitting inside your business: to build personal wealth that grows tax-deferred and comes out tax-free?
The Tax Trap: Why Traditional Advice Fails High-Earners
Standard financial advice is built for the "average" employee. For the person earning $100,000 a year, a 401(k) is a fantastic tool. But for the business owner or the key executive driving millions in value, the math just doesn't work. When you factor in the "Top Heavy" testing rules and the strict contribution caps, you quickly realize that the traditional system is designed to limit your ability to accumulate wealth.
Furthermore, traditional retirement accounts are "tax-deferred," not "tax-exempt." This means you are essentially making a bet with the federal government. You’re betting that tax rates will be lower thirty years from now than they are today. Given the current trajectory of national debt and government spending, is that a bet you really want to make?
We believe there is a better way. We call it the Perfect Plan® model.
Introducing the Perfect Plan® Model
At Schiff Executive Benefits, we focus on a methodology that aligns corporate objectives with personal wealth goals. The Perfect Plan® isn't a single product; it is a strategic framework designed to move money from the business to the individual in the most tax-efficient manner possible.
The goal of the Perfect Plan® is to achieve three specific outcomes:
Tax-Deductible Contributions: The business gets a deduction for the cost of the benefit.
Tax-Deferred Growth: The assets grow without being eroded by annual capital gains or income taxes.
Tax-Free Distribution: You can access the wealth in retirement without triggering a massive tax bill.
Does this sound too good to be true? It isn't. Large corporations and banks have been using these strategies for decades: often referred to as Bank-Owned Life Insurance (BOLI) or Corporate-Owned Life Insurance (COLI). The secret is simply scaling these institutional strategies down to the private business level.
Strategy 1: The Executive "Bonus" That Actually Works
Most bonuses are a tax nightmare. You pay the employee (or yourself) $100,000; the business loses $100,000 in cash, and the individual receives about $60,000 after taxes. That’s a 40% loss of friction right out of the gate.
Using an Executive Bonus Plan (Section 162), we can restructure this. The business pays the premium on a high-cash-value life insurance policy owned by the executive. The premium is deductible to the business and taxable to the executive, but we can "double bonus" the tax amount so the executive has zero out-of-pocket cost. Inside that policy, the money grows tax-deferred. When it’s time to retire, the executive can take loans against the policy: which are generally tax-free: to fund their lifestyle.
You’ve essentially used corporate dollars to create a private "bank" for yourself, bypass the 401(k) limits, and secure a tax-free income stream.
Strategy 2: Split-Dollar Arrangements
For the owner looking to move significant wealth out of the company without an immediate tax hit, "Split-Dollar" arrangements are the gold standard. In this scenario, the company and the executive "split" the costs and benefits of a permanent life insurance policy.
The company pays the premiums, which are treated as a series of loans to the executive (at very low IRS-mandated interest rates). Because it’s a loan, there’s no immediate income tax for the executive. The cash value inside the policy grows, often far exceeding the interest on the loan. At death or at a pre-determined rollout point, the company is paid back its premiums, and the executive (or their heirs) keeps the remaining millions: often entirely tax-free.
The Power of Tax-Free Growth and Distribution
Think about your current portfolio. If you have $5 million in a traditional IRA, you don't actually have $5 million. You have $3 million, and the IRS has a $2 million lien on your account. Every time the market goes up, the IRS’s share grows. Every time tax rates go up, your share shrinks.
When you build wealth using the corporate dollar strategies we advocate for, you are removing the IRS as a partner in your future. You are locking in a 0% tax rate on those distributions. This provides a level of certainty that no traditional stock-and-bond portfolio can match.
As Matthew Schiff often says on The Perfect Plan® Podcast, "The greatest risk to your retirement isn't market volatility; it's the uncertainty of future tax legislation." By using corporate dollars now to fund tax-advantaged vehicles, you are essentially "tax-morphing" your wealth: changing it from a taxable liability into a private, protected asset.
Why Retention and Wealth Building Go Hand-in-Hand
While you are building your own wealth, these same plans serve as the ultimate "Golden Handcuffs" for your key employees. In today’s competitive talent market, a simple 401(k) match isn't enough to keep a CFO or a VP of Sales from being recruited away.
By offering a Deferred Compensation or a tax-efficient executive benefit plan, you are providing them something they cannot get anywhere else: a path to tax-free wealth. If they leave, they leave the benefit behind. If they stay, they retire wealthy. It’s a win-win that uses the company’s cash flow to solve two problems at once: tax efficiency for you and retention for the business.
The Point of No Return: Why Now?
We are currently living in a unique economic window. Tax rates are historically low, but the clock is ticking on the expiration of the Tax Cuts and Jobs Act (TCJA). Furthermore, as the national debt continues to climb, the pressure to raise revenue through higher income and estate taxes is mounting.
Waiting until you are ready to exit the business to think about tax efficiency is a mistake. The best time to start moving corporate dollars into personal, tax-efficient buckets was ten years ago. The second best time is today.
Are you currently maximizing every dollar your business generates? Or are you leaving a "tip" for the IRS every year because your benefit plan is stuck in the 1990s?
Take the Next Step Toward Your Perfect Plan®
Building wealth tax-efficiently requires more than just a good accountant; it requires a specialized architect who understands the intersection of corporate tax law, executive compensation, and insurance design.
At Schiff Executive Benefits, we don't just sell plans; we design outcomes. We help you look at your business not just as a source of current income, but as a powerful engine for personal wealth accumulation.
If you’re ready to stop overpaying the IRS and start using your corporate dollars to secure your personal legacy, let’s have a conversation. It’s time to move beyond the limitations of standard retirement planning and start building your Perfect Plan®.
Sit back, grab a coffee, and let’s look at the math together. You’ve done the hard work of building the business: now let’s make sure you get to keep what you’ve earned.