Hi, How Can We Help You?
  • Planning for all of life's "What Ifs".

Monthly Archives: April 2026


It is a universal, undeniable truth that the roles we play in our families eventually come full circle. We spend the first quarter of our lives being cared for by our parents, and if we are fortunate enough to reach our professional peak, we often spend the third quarter returning the favor.


For many high-achieving leaders, this isn’t just a personal transition; it’s a strategic collision. You are currently in what I call the Executive Sandwich.


In Part 1: The Executive Sandwich: Why Your Career Peak is Often Your Family’s Riskiest Decade, we explored how the height of your earning years is simultaneously the height of your financial vulnerability. In Part 2: Beyond the 401(k) Cap: Solving the Executive College Funding Gap, we looked at the pressure of launching the next generation. Today, we face the most emotionally taxing and financially unpredictable layer of the sandwich: caring for aging parents.


How do you provide the dignity and care your parents deserve without siphoning away the wealth you’ve spent decades building? How do you manage a C-suite schedule when a midnight phone call changes everything?


At Schiff Executive Benefits, we believe in Restoring Alignment and Retention, and that includes the alignment of your personal peace of mind with your professional legacy.


The Hidden Cost of Longevity


We often talk about market risk or interest rate risk, but for the modern executive, the greatest "What If" is often Longevity Risk.


In our framework of the "5 What Ifs," we frequently ask: What if you run out of money in retirement? But long before you face that question for yourself, you may face it for your parents. Modern medicine is a miracle, but it has created a financial paradox: our parents are living longer, but not necessarily healthier.

Matt Schiff - Professional Smile Blue Suit


The cost of long-term care: whether home health aides, assisted living, or skilled nursing: is rising at a rate that far outpaces general inflation. For an executive, the cost isn't just the invoice from the facility. It is the "opportunity cost" of your time and the potential "leakage" from your investment portfolio to cover gaps in their care.


Are you prepared to liquidate a portion of your estate to cover a $15,000-a-month nursing bill that could last five or ten years? Most executives aren't. They assume they can "cash flow" it, only to realize that doing so compromises their own retirement goals and the legacy they intended to leave for their children.


The Emotional Vice


Caregiving is a full-time job. When you are managing a global team or overseeing a complex merger, the emotional weight of a parent’s declining health can be paralyzing. You find yourself in a consultative dialogue with doctors, siblings, and care coordinators, all while trying to maintain the "authoritative presence" required in the boardroom.


I recently spoke with a client: let's call him David: a CEO who was in the middle of a major acquisition. His mother suffered a stroke. Suddenly, David wasn't just managing a billion-dollar deal; he was navigating Medicare gaps and searching for a memory care facility that didn't feel like a hospital. The stress didn't just affect his sleep; it affected his decision-making.


David’s story is not unique. It is the reality of the sandwich generation. The question is: do you have a plan that protects your focus as much as it protects your capital?

Executive reflecting on aging parents photo, highlighting the financial strain of the sandwich generation.


The Strategy: Shifting the Burden to the Business


One of the most overlooked solutions in executive wealth planning is the use of Long-Term Care (LTC) riders and business-paid policies.


Many executives assume that LTC is an individual expense, paid with after-tax dollars. However, for business owners and key executives, there is a much more efficient way.


1. The Business-Paid Deductible Policy


If structured correctly through a corporation or partnership, the business can pay the premiums for a Long-Term Care policy. In many cases, these premiums are tax-deductible to the business and are not considered taxable income to the executive. This is a powerful tool for attracting and retaining top talent who are feeling the squeeze of the sandwich generation.


2. COLI with LTC Riders


Corporate Owned Life Insurance (COLI) is a cornerstone of The Perfect Plan®. By adding a Long-Term Care rider to a COLI or specialized life insurance policy, you create a "multipurpose" asset. If you (or your parents, depending on the structure) need the care, the death benefit is accelerated to pay for those expenses tax-free. If the care is never needed, the death benefit remains intact for your heirs.


3. Protecting the Portfolio


By using an insurance-based solution, you create a "firewall" around your investments. Instead of selling stocks in a down market to pay for a home health aide, you leverage the insurance company's capital. This ensures that your personal legacy: your "dream value": remains untouched.


Longevity Risk and The Perfect Plan®


When we design The Perfect Plan®, we don't just look at your balance sheet; we look at your life’s timeline. We integrate these "What If" scenarios into a cohesive strategy.


If you are a business owner, providing LTC benefits to your senior executive team is one of the most empathetic and strategic moves you can make. It rewards your best people by solving a problem that keeps them up at night, ensuring they stay focused on the business because their home life is secure.

Modern Meeting Work Scene


Starting the Conversation: A Consultative Approach


Caring for aging parents requires more than financial products; it requires a team of advisors. You need to have honest, often difficult conversations today to avoid a crisis tomorrow.


Here are three steps you can take right now:


  • Audit Your Parents' Documents: Do they have a clear Power of Attorney and a Healthcare Proxy? Without these, your ability to manage their care will be legally hamstrung.

  • Evaluate the "Care Gap": Look at their current assets versus the cost of care in their area. Where is the shortfall?

  • Explore Hybrid Solutions: Look into life insurance policies with LTC riders. These are often more palatable than "use-it-or-lose-it" traditional LTC insurance because they guarantee a payout in one form or another.


The Point of No Return


The window of opportunity to put these protections in place is often smaller than we realize. Once a diagnosis is made or a health event occurs, many of the most efficient financial strategies are off the table.


Waiting is the greatest risk to your legacy. By acting now, you aren't just buying insurance; you are buying the ability to be a daughter or a son again, rather than just a care manager. You are buying the peace of mind to sit back, grab your coffee, and focus on the people who matter most.


At Schiff Executive Benefits, we specialize in navigating these complexities. Whether it’s through Trust Owned Life Insurance (TOLI) to manage estate taxes or building a robust executive benefit suite, our mission is to ensure that your success isn't eroded by the natural cycles of life.


Conclusion: Join the Conversation


The Executive Sandwich doesn't have to be a source of constant anxiety. With the right structure, it can be a season of your life where you demonstrate your values through your actions and your foresight.


If you’re feeling the pressure of the sandwich generation and want to see how The Perfect Plan® can protect your legacy while providing for your parents, I invite you to reach out. Let’s look at your specific "What Ifs" and build a plan that restores alignment to your world.


Come join us at our next NQDC Panel or listen to The Perfect Plan® Podcast for more insights into securing your professional and personal future.


Sit back, grab your coffee, and let’s start building it your way.


: Matt Schiff
President, Schiff Executive Benefits


To explore more about our strategies for executives and corporations, visit our services page.


They say that a bird in the hand is worth two in the bush, but when you are standing at the threshold of retirement, you start wondering exactly which bush you should reach into first. For decades, you’ve been focused on one thing: accumulation. You’ve watched the numbers grow, checked your statements, and contributed to your 401(k) with the discipline of a marathon runner.


But then, the finish line appears. Suddenly, the game changes. You aren't just putting money away anymore; you have to figure out how to take it out without the tax man taking a massive bite or, even worse, running out of it before you run out of breath.


At Schiff Executive Benefits, we often talk about the five core "What If" questions that keep executives and business owners up at night. The big one we’re tackling today is the fifth: What if you run out of retirement money?


Solving that "What If" isn't just about how much you’ve saved; it’s about the design of your retirement paycheck.


The Story of Ruth: A Study in Transition


To make this real, let’s look at a case study we recently handled. Let’s call her Ruth. Ruth is a single nurse who spent her entire career caring for others. She’s been incredibly diligent, building up a solid nest egg. But as she approached her mid-60s, she felt a sense of paralysis.


Ruth had several different "buckets" of money, but no clear map on how to spend them. She was worried about whether she should take Social Security now or later. She was worried about her traditional IRA vs. her Roth. And as a single person, she was particularly concerned about the long-term: who would care for her if her health declined?


Ruth’s situation is common. Whether you are a high-level executive or a dedicated professional like Ruth, the transition from "saver" to "spender" is a psychological and mathematical hurdle. We needed to create The Perfect Plan® for her, one that turned her pile of assets into a predictable, sustainable stream of income.


Matt Schiff - Professional Smile


Understanding Your Tax Buckets


Before you can decide where your income should come from first, you have to categorize your assets. Not all dollars are created equal. In the eyes of the IRS, they live in very different neighborhoods:


  • The Pre-Tax Bucket (Traditional IRA/401(k)): This is where most people have the bulk of their savings. It’s "forever taxed" money. Every dollar you take out is taxed as ordinary income.

  • The Tax-Free Bucket (Roth IRA/401(k)): This is the holy grail. You’ve already paid taxes on this money, so it grows and comes out tax-free.

  • The Non-Qualified Bucket (Brokerage Accounts): This is money sitting in stocks, bonds, or mutual funds outside of a retirement account. You only pay taxes on the gains (capital gains), not the "cost basis" (the money you originally put in).

  • The Cash Bucket (Bank Accounts/CDs): Highly liquid, but the interest is taxed annually. In a low-interest environment, this bucket often loses purchasing power to inflation.


The goal of Retirement Paycheck Design is to coordinate these buckets so you aren't paying more to Uncle Sam than is absolutely necessary.


The Social Security Tug-of-War: 62 vs. 67 vs. 70


One of the first questions Ruth asked was, "When should I start my Social Security?"


There is a lot of "conventional wisdom" out there, but "conventional" rarely means "perfect." Here is how we look at the Social Security timeline:


Age 62: The Liquidity Play


Taking Social Security at 62 gives you immediate cash flow. For some, this is a "protection" move. If you have concerns about your health or you want to preserve your investment principal during a market downturn, taking it early might make sense. However, you are locking in a permanently reduced benefit, roughly 30% less than your full retirement age amount.


Age 67: The Full Retirement Age (FRA)


For most people retiring today, this is the "baseline." You get 100% of your promised benefit.


Age 70: The Max Benefit


If you wait until 70, your benefit increases by about 8% for every year you delay past your FRA. This is a massive "guaranteed" return that is hard to find anywhere else. However, there’s a catch: to wait until 70, you have to live off your other assets for those intervening years. You are essentially "spending down" your IRAs or brokerage accounts to "buy" a higher Social Security check later.


For Ruth, we had to weigh the math. Does she drain her liquid investments now to get a bigger check at 70? Or does she take the check now to keep her investments growing? There is no one-size-fits-all answer, which is why a customized design is essential.


Executive desk with financial planning documents for retirement income and Social Security strategy.


Beware the Age 73 "Tax Bomb"


There is a ticking clock in your retirement plan called the Required Minimum Distribution (RMD). Currently, once you hit age 73 (and moving to 75 in the future), the government forces you to take money out of your pre-tax accounts.


If you’ve been a great saver and your IRA has grown to $2 million or $3 million, those mandatory withdrawals can be huge. They can push you into a higher tax bracket, increase the cost of your Medicare premiums, and make your Social Security benefits more taxable.


We call this the RMD Tax Bomb. One of the primary goals of our design process is to "defuse" this bomb by strategically taking distributions before you are forced to, or by utilizing Roth conversions during lower-income years.


Managing the Silent Killer: Inflation


Ruth was worried about inflation, and rightly so. But we look at inflation through two different lenses: fixed costs and rising lifestyle costs.


  1. Fixed Costs: If Ruth has a mortgage with a fixed 3% interest rate, her "inflation" on that expense is effectively 0%. The payment stays the same while the value of the dollar drops.

  2. Rising Costs: Healthcare and general lifestyle expenses (travel, dining, gas) do not stay fixed. Healthcare inflation, in particular, often runs much higher than the standard Consumer Price Index (CPI).


In Ruth’s design, we ensured that her guaranteed income sources (Social Security and potential annuities) covered her fixed "must-pay" bills, while her investment portfolio was positioned to provide the "inflation-adjusted" raises she would need for her lifestyle over the next 20 to 30 years.


The Single Professional’s Risk: Long-Term Care


As a single nurse, Ruth knew better than anyone that "hope is not a strategy" when it comes to aging. Without a spouse to provide "informal" care at home, the financial burden of a long-term care event is much higher for singles.


We incorporated a strategy that looked at her assets not just as an income source, but as a reserve for care. By Restoring Alignment and Retention of her capital, we could ensure that if she ever needed help, she wouldn't have to rely on the state or be a burden on her extended family.


Modern Meeting Work Scene


Designing Your Perfect Plan®


Retirement shouldn't feel like a series of stressful guesses. It should feel like a well-earned victory lap. Whether you are concerned about your own retirement or you are an employer looking at how to attract, retain, and reward the top talent in your firm by helping them solve these same problems, the framework remains the same.


We help executives and professionals navigate the complexities of:


If you are wondering which bucket you should dip into first, don't guess. The difference between an accidental retirement and a designed one can be hundreds of thousands of dollars in taxes saved and a lifetime of peace of mind.


At Schiff Executive Benefits, we specialize in helping you find that clarity. We invite you to explore our services and video library to see how we’ve helped others in your shoes.


Ready to talk about your specific situation?


Sit back, grab your coffee, and let’s start a conversation. We can help you design a paycheck that lasts as long as you do.


Ready to talk? Click here to schedule your initial meeting.


Restoring Alignment and Retention.


Disclaimer: This blog post is for educational purposes only and does not constitute financial, legal, or tax advice. Please consult with your professional advisors before making any significant financial decisions.


Learn more: See how decanting assets turns your portfolio into retirement income you can’t outlive.


A parent’s greatest ambition is to provide a better life for their children than the one they had. It is a universal, undeniable truth that spans generations and tax brackets. We work late, we climb the corporate ladder, and we navigate high-stakes environments, often with the singular goal of ensuring our children have every opportunity: starting with a world-class education.


But for the modern executive, that ambition often runs head-first into a "math problem" that most people don’t even realize exists.


In Part 1 of our "Sandwich Generation" series, we looked at the emotional and financial toll of caring for aging parents while raising children. Today, in Part 2, we are getting tactical. We are looking upward at the looming cost of higher education and how the current legislative environment actually penalizes the highest earners in the room.


If you are an executive making $450,000 or more, you aren't just facing higher tuition bills; you are facing a structural disadvantage in how you are allowed to save for them.


The 401(k) Math Problem: A 10% Disadvantage


Most people view the 401(k) as the gold standard of retirement and savings. For the average American worker, it is. If an employee earns $150,000 a year and contributes the 2026 limit of $24,500 (plus any catch-up contributions), they are shielding roughly 16% of their income from taxes and growing it for the future.


Now, let’s look at the C-suite.


If you are an executive earning $460,000, that same $24,500 contribution represents only about 5% of your income. While your peers are saving 15% to 20% of their earnings in a tax-advantaged environment, you are capped at 5%. The remaining 95% of your income is subject to the highest marginal tax rates.


This creates a massive "Savings Gap." When the time comes to write a check to Tulane, Harvard, or Michigan, most executives are forced to do so with "expensive" dollars: money that has already been taxed at 37% or higher.


Furthermore, if you try to tap into your 401(k) to cover a tuition spike, you aren't just hit with the tax; you’re hit with a 10% early withdrawal penalty if you are under age 59½. For the Sandwich Generation executive, whose children hit college age while they are in their peak earning years (usually their 40s or 50s), the 401(k) is a locked box that is too small to begin with.


An executive reviewing university brochures while considering college funding strategies beyond the 401k cap.


The 401(k) Mirror Plan: A Pre-Tax Tuition Solution


At Schiff Executive Benefits, we focus on Restoring Alignment and Retention. One of the most powerful ways to do that is through a Nonqualified Deferred Compensation (NQDC) plan, often referred to as a "Mirror Plan."


A Mirror Plan allows executives to defer a much larger percentage of their compensation: sometimes up to 80% or 90%: into a tax-deferred account. Unlike a 401(k), there are no IRS-mandated contribution caps on NQDC plans. If you need to save $100,000 a year for your children’s education, a Mirror Plan allows you to do that with pre-tax dollars.


But the real "magic" for college funding lies in the Specific Date Withdrawal feature.


Navigating 409A: The Specific Date Strategy


Under Internal Revenue Code Section 409A, NQDC plans allow participants to schedule distributions for specific times. Unlike a 401(k), where you generally have to wait until retirement or 59½ to avoid penalties, an NQDC plan can be structured to pay out while you are still working.


Imagine your daughter is 10 years old. You know that in eight years, you will need to start paying tuition. Under a Mirror Plan, you can elect to defer a portion of your salary or bonus today and schedule that distribution to hit your bank account in exactly eight years.


The benefits are twofold:


  1. Pre-Tax Funding: You are funding the "College Fund" with gross dollars, not net dollars. This significantly increases your "buying power" for tuition.

  2. No 10% Penalty: Because these plans are designed for flexibility, you avoid the early withdrawal penalties associated with traditional retirement accounts.


It is a tactical, solution-oriented way to ensure that your "Sandwich" years don't result in you running out of retirement money: one of the core "What Ifs" we help business owners and executives solve.


Matt Schiff Speaking NQDC


Why Companies Offer the "College Funding" Benefit


You might ask, "Why would my company set this up for me?"


The answer is simple: Executive Retention.


In today’s market, losing a top-tier executive costs a company significantly more than just their salary. It costs institutional knowledge, client relationships, and momentum. By offering a Mirror Plan, a company provides a "Golden Handshake" that solves the executive's most pressing personal anxiety: paying for their children’s future without sacrificing their own retirement.


When a company helps an executive solve the "401(k) Math Problem," they aren't just providing a benefit; they are building a bridge of loyalty. We call this The 401(k) Cap Problem: How a Mirror Plan Rewards Your Best People.


Integrating the Mirror Plan into The Perfect Plan®


At Schiff Executive Benefits, we don't look at these tools in a vacuum. A Mirror Plan is one piece of a larger puzzle we call The Perfect Plan®.


Whether we are discussing Corporate Owned Life Insurance (COLI) to informally fund these obligations or structured buy/sell arrangements, the goal is always the same: clarity.


We often see executives who are "over-funded" in their 401(k) but "under-saved" for their specific life goals. They have the assets, but they don't have the liquidity or the tax efficiency they need when the tuition bill arrives.


By utilizing a Mirror Plan, you can keep your 401(k) on track for your 70s while using your deferred compensation to handle your 50s.


Executive couple meeting with a consultant to discuss a Mirror Plan for retirement and education savings.


The Professional’s Legacy


We often talk about the "5 What Ifs" that keep business owners awake at night. When it comes to the Sandwich Generation, the fear of Senior exec retirement/replacement cost efficiency and running out of retirement money are top of mind.


But there is a deeper, more personal "What If": What if I can't provide the same level of education for my kids that my parents provided for me?


Economic shifts and rising tuition costs have made the "standard" path: saving in a 529 and maxing out a 401(k): insufficient for high earners. You need a strategy that reflects your income level. You need a strategy that recognizes that as an executive, the rules of the game are different for you.


Tactical Summary for the Executive


If you are looking at your 401(k) and realizing it won't cover the gap, consider these steps:


  • Audit your "Savings Gap": Calculate what percentage of your total income is actually protected by tax-advantaged accounts. If it's less than 10%, you have a cap problem.

  • Review the Plan Documents: Does your company offer an NQDC or Mirror Plan? If so, does it allow for "In-Service" or "Specific Date" distributions?

  • Coordinate with your Team: Ensure your tax advisor and financial consultant are looking at your deferrals as part of a holistic education funding strategy, not just a retirement strategy.


Join the Conversation


Solving the college funding gap is about more than just numbers; it’s about peace of mind. It’s about knowing that while you are leading your company toward its goals, your family’s future is being secured with the same level of executive precision.


If you are a business owner looking to reward your top talent, or an executive trying to navigate the "Sandwich" years, we invite you to sit back, grab your coffee, and explore how we can help.


Check out our latest insights on The Perfect Plan® Podcast or reach out to our team to discuss how a Mirror Plan can work for your organization.


Stay tuned for Part 3 of our series, where we will dive into the "Downstage" of the Sandwich: Caring for Aging Parents without Derailing Your Corporate Legacy.


Official SEB Mini Logo


Restoring Alignment and Retention.


In sports, as in business, the name on the front of the jersey is far more important than the name on the back. However, any coach will tell you that you can’t win the championship if your star players decide to take their talents to a rival team halfway through the season.


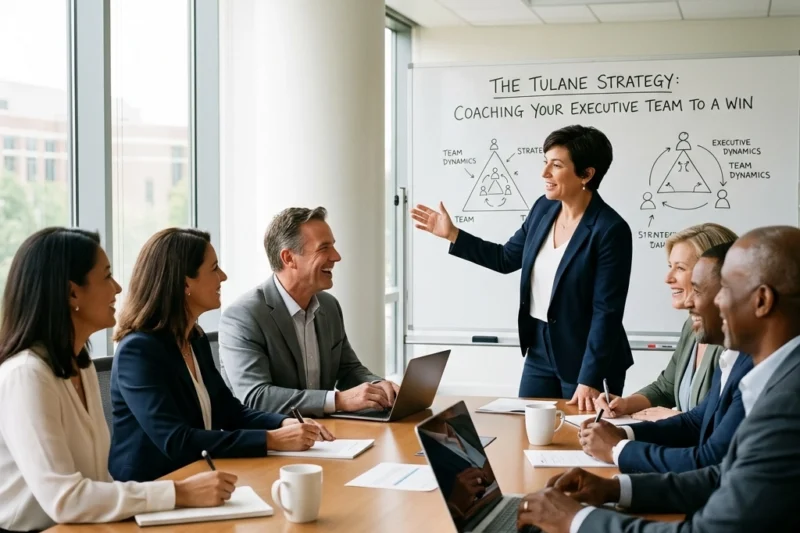
Success is never an accident. It is the result of high intention, sincere effort, intelligent direction, and skillful execution. At Tulane, we call it the "Roll Wave" spirit: that relentless drive to overcome the odds and build something lasting. In the corporate world, I call it The Tulane Strategy. It’s about more than just "benefits"; it’s about coaching your executive team to a win by aligning their personal success with the company’s long-term goals.


When we talk about executive benefits at Schiff Executive Benefits, we aren't just talking about spreadsheets and tax codes. We are talking about Restoring Alignment and Retention.


The Freeman School Mindset: Building for the Long Game


If you’ve ever walked through the Goldring/Woldenberg Business Complex at Tulane’s Freeman School of Business, you feel the weight of legacy and the energy of innovation. It’s where I learned that a business is only as strong as its leadership core.


Tulane Freeman School Business Complex


In the current economic climate, many business owners are looking at their roster and feeling a sense of unease. They see the "Top Talent Leaving" (one of our core 5 What Ifs) and wonder if their current playbook is enough to keep their key players on the field.


Are you playing defense, or are you coaching to win?


Most companies offer a standard 401(k) and call it a day. But for your top-tier executives, the standard plan often isn't enough. Due to IRS limits, your highest-paid people are often the ones most restricted in their ability to save for retirement. This is known as The 401(k) Cap Problem. When your stars realize they are being sidelined by contribution limits, they start looking for a team that will let them play the full game.


What Keeps You Up at Night?


As a business owner or CEO, you’ve likely asked yourself the hard questions. At SEB, we’ve distilled these into five thematic anchors that we call the "What Ifs." These aren't just hypothetical scenarios; they are the "fumbles" that can cost you the game:


  1. The Widow Question: What happens if your partner passes away and you find yourself in business with their spouse?

  2. The Buy-Out: How do you fund a buy-sell agreement without draining the company’s cash flow?

  3. The Talent Drain: What if your VP of Sales or your CTO is recruited by your biggest competitor tomorrow morning?

  4. The Retirement Gap: Are your senior executives actually on track to retire, or will their replacement costs cripple your bottom line?

  5. The Longevity Risk: Will you: and your team: run out of money in retirement because you didn't plan for the tax environment of the future?


If these questions keep you awake, you aren’t alone. But a good coach doesn’t just identify the problem; they design a play to overcome it.


The Perfect Plan®: Restoring Alignment


To win, you need a strategy that rewards performance while ensuring loyalty. This is where The Perfect Plan® comes into play.


The Perfect Plan® isn't a one-size-fits-all product. It is a consultative framework designed to restore the alignment between what the executive needs and what the company wants. Think of it as the "scholarship" that keeps the star athlete committed to the university. It’s a promise of future value that is earned through current performance.


Matt Schiff - Confident Blue Suit Standing


The Defensive Line: Corporate Owned Life Insurance (COLI)


In the corporate world, especially for non-banking entities, Corporate Owned Life Insurance (COLI) is a foundational tool. It provides a tax-efficient way to fund the promises you make to your executives. Whether it’s funding a Supplemental Executive Retirement Plan (SERP) or securing a buy-sell agreement, COLI acts as the defensive line that protects your company’s balance sheet from the unexpected.


When we implement a COLI strategy, we aren't just looking at the death benefit. We are looking at the cash value growth that can offset the liabilities of executive benefits. It’s about making the math work so you can focus on making the business work.


The Offensive Play: Non-Qualified Deferred Compensation (NQDC)


If COLI is the defense, then Non-Qualified Deferred Compensation (NQDC) is the offense. A well-structured NQDC plan (often referred to as a "Mirror Plan") allows your executives to defer a portion of their compensation: above and beyond 401(k) limits: on a pre-tax basis.


This does two things:


  1. It helps the executive solve their retirement gap.

  2. It creates "golden handcuffs" that keep them tied to your organization's success.


By incorporating vesting schedules, you ensure that your team stays together long enough to see the vision through to the end. You aren't just paying them to show up; you are coaching them to stay and win.


Leadership from the Sidelines to the C-Suite


I recently had the privilege of speaking at the NQDC Industry Updates panel in NYC. Sitting there with other industry leaders, it became clear that the challenges we face in 2026: market volatility, changing tax laws, and a hyper-competitive talent market: require a new kind of leadership.


Matt Schiff Speaking NQDC


It requires an authoritative yet empathetic approach. We understand that your business is your legacy. It’s not just about the numbers; it’s about the people who built those numbers with you.


When you look at your executive team, do you see a group of individuals, or do you see a championship team? A championship team has a shared vision and a shared reward. If your current benefits package feels like a "participation trophy" rather than a "championship ring," it might be time to redraw the playbook.


Realizing Your Dream Value


Every business owner has a "dream value" for their company: the point at which they can step away knowing the business is secure and their lifestyle is protected. But you can't reach that dream value if you are constantly stuck in a cycle of "recruit, train, lose, repeat."


By implementing The Perfect Plan®, you are building it your way. You are creating an environment where your top people feel valued, secured, and aligned with your long-term objectives.


As we look toward the future, the economic environment remains "unstable" at best. National debt is rising, and tax rates are a moving target. In this environment, doing nothing is the riskiest move you can make. It is the point of no return.


Come Join Us in the Winner’s Circle


At Schiff Executive Benefits, we don't just sell plans; we build partnerships. We want to act as your guide through the complexities of COLI, Split Dollar arrangements, and 401(k) mirror plans. We want to help you answer those "What If" questions with a confident, "We’ve got a plan for that."


Matt Schiff - Grand Staircase Wisdom Inscription


So, I invite you to take a breath. Sit back, grab your coffee, and think about your team. Are they positioned to win? Are you?


If you're ready to explore how the Tulane spirit of grit and strategy can transform your executive retention, let's talk. We’re here to help you restore alignment and ensure that when the final whistle blows, your team is the one holding the trophy.


Schiff Executive Benefits Full Logo


Ready to start coaching your team to a win?
Contact us today to learn more about how The Perfect Plan® can secure your company's future. You can also browse our latest insights and industry updates on our posts page.

Roll Wave!


The only thing more expensive than a highly compensated executive is a departed one. In the modern arms race for talent, we often talk about culture, purpose, and flexibility. But when you strip away the office perks, the foundation of any executive retention strategy is security. If your key people don't feel their family’s future is anchored, they’ll eventually look for a sturdier harbor.


For years, the "anchor" for many firms was a standard group term life policy or a basic executive carve-out. But as executive salaries and the cost of living have skyrocketed, those old underwriting limits haven't just become outdated: they’ve become a liability. We’ve seen it time and again: a CEO or EVP realizes their total coverage barely covers two years of their current lifestyle, and suddenly, they’re listening to recruiters.


At Schiff Executive Benefits, we specialize in what we call the "reverse engineering" approach. We don't start with a product; we start with the "What Ifs." Specifically, what if your top talent leaves because they found a better "safety net" elsewhere? Or worse, what if you have to face their widow or widower and explain why the coverage was capped at a fraction of their value?


The good news? The insurance landscape has shifted dramatically. If you haven't looked at your executive underwriting limits in the last 24 months, you’re likely operating on old data. Here are five things you need to know about the new frontier of executive coverage.


1. The $10M+ Ceiling: Guaranteed Issue (GI) is Growing Up


In the "old days": which, in our industry, was about five years ago: getting $2 million or $3 million in life insurance without a medical exam was considered a win. If an executive wanted more, they had to prepare for the "parmed" exam: blood draws, physicals, and weeks of waiting.


Today, the game has changed. For groups of a certain size, we are seeing Guaranteed Issue (GI) limits climb to $5 million, $10 million, and in some specialized cases, even higher. This means that if you have a group of executives, the carrier "guarantees" the issue of these high-limit policies without asking a single medical question.


Why does this matter? Because high-performers are busy. They don't want to spend their Tuesday morning with a nurse in the conference room. By leveraging multi-life programs, we can secure substantial death benefits that actually move the needle for a high-net-worth individual, all while bypassing the traditional friction of individual underwriting. This is a core component of how we help clients build The Perfect Plan®.


2. From Biology to Business: The Shift to Financial Underwriting


One of the most significant shifts we’ve navigated recently is the move toward Financial Underwriting over medical scrutiny. In the past, carriers were obsessed with your cholesterol levels. Today, they are more interested in your "Why."


If an executive is looking for $15 million in coverage, the underwriter isn't just looking at their heart rate; they are looking at their income, their assets, and their value to the company. This is where "justifying the need" comes into play. We help firms document the economic loss the company would suffer: or the gap in the executive's personal estate plan: to satisfy the "financial" side of the house.


When we use Corporate Owned Life Insurance (COLI) to fund these benefits, the financial justification is built into the plan design. It’s no longer about whether you’re a marathon runner; it’s about whether the coverage amount makes sense relative to your professional impact.


Financial reports and glasses on a mahogany desk representing executive financial underwriting limits.


3. Simplified Issue (SI): The "Fluidless" Revolution


Even when a group doesn't qualify for full Guaranteed Issue, we rarely have to resort to the "old way." The rise of Simplified Issue (SI) or "fluidless" underwriting has been a godsend for executive convenience.


Modern algorithms and access to digital health records mean that many carriers can now offer millions in coverage based on a digital application and a phone interview. No needles, no vials, no waiting six weeks for a lab report. This speed is a massive advantage when you’re trying to close a new executive hire or finalize a buy/sell agreement.


If you’re still putting your board of directors through the medical wringer, you’re using a 1990s solution for a 2026 problem. We advocate for these "low-touch, high-value" paths whenever possible to keep the momentum of the plan moving forward.


4. Portability: Why Executives Love Individual Ownership (REBA)


One of the "5 What Ifs" we constantly talk about is: What if your top talent leaves? Usually, when an executive leaves a company, their group term insurance stays behind. They’ve spent ten years building a career, and they walk out the door with zero life insurance coverage.


This is why we’ve seen a massive surge in Restricted Executive Bonus Arrangements (REBA).


A REBA uses an individual policy, often funded by the employer, but owned by the executive. Because the underwriting is handled at the individual level (often using the SI or GI methods mentioned above), the policy is portable. If the executive retires or moves on, they take the policy: and the death benefit: with them.


From the company’s perspective, you can still add "golden handcuffs" by placing a restrictive covenant on the policy's cash value. This creates a "win-win":


  • The Executive gets a high-limit, permanent policy they own.

  • The Employer gets a powerful retention tool that "restores alignment."


It’s about moving away from "renting" coverage through group term and toward "owning" a piece of their financial legacy. You can hear more about these structures on The Perfect Plan® Podcast.


5. The "Spread of Risk" Benefit for Large Firms


Insurance, at its heart, is a game of math. For larger firms, the "Spread of Risk" allows for much more aggressive underwriting. When a carrier looks at a group of 50 or 100 executives, they aren't worried about one person having a health hiccup; they are looking at the law of large numbers.


This "multi-life" approach allows us to negotiate terms that would be impossible for an individual. We can often secure higher limits, lower internal costs, and better policy riders because the carrier is taking on a "portfolio" of risk rather than a single life.


This is particularly relevant for partnerships and professional service firms. By treating the executive suite as a single "risk pool," we can often eliminate the "uninsurable" executive problem. We’ve had cases where an executive who was previously declined for individual coverage was able to get $5M+ in coverage because they were part of a multi-life GI program.


Restoring Alignment and Retention


At the end of the day, these technical shifts in underwriting aren't just "industry news." They are tools you can use to answer the questions that keep you up at night.


  • What if your senior exec retires, and the cost of replacement is double what you expected?

  • What if a key partner passes away and the buy-out funding is insufficient?


We don't just sell insurance; we design systems to protect your professional legacy. We look at your current plan, find the gaps where underwriting limits are choking your goals, and then we "reverse engineer" a solution that fits your specific culture.


Whether you’re looking at COLI to fund a deferred comp plan or exploring how to modernize your buy/sell funding, the goal is always the same: Restoring Alignment and Retention.


If you’re wondering if your current limits are leaving you: and your team: exposed, let’s have a conversation. No pressure, no "hard sell." Just a look at the math and a discussion about your "What Ifs."


Sit back, grab your coffee, and reach out to us. We’d love to help you build your version of The Perfect Plan®.


Ready to talk?


If you’re thinking through one of those big “What If” questions—top talent leaving, retirement readiness, or whether your current benefit structure is really doing its job—let’s talk it through.


Schedule an initial meeting.


To stay updated on the latest in executive benefits, tax-efficient strategies, and talent retention, check out our full video library or browse our latest posts.


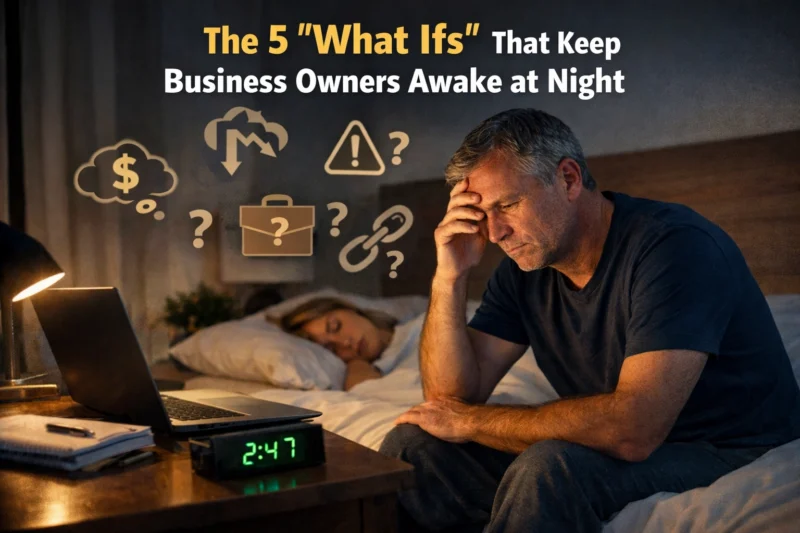
title: "The 5 'What Ifs' That Keep Business Owners Awake at Night"
meta_title: "The 5 What Ifs for Business Owners | Schiff Executive Benefits"
description: "The 5 What Ifs every business owner should address: succession, buy/sell planning, executive retention strategies, COLI funding, and retirement income certainty."
meta_description: "The 5 What Ifs every business owner should address: succession, buy/sell planning, executive retention strategies, COLI funding, and retirement income certainty."
keywords:
- executive retention strategies
- business succession planning
- buy sell agreement funding
- COLI
- deferred compensation
- retirement income planning


"Success is a lousy teacher; it seduces smart people into thinking they can't lose." This observation, often attributed to Bill Gates, captures the precarious nature of business ownership. You have spent years, perhaps decades, building an engine of growth. You have weathered economic cycles, navigated hiring crises, and outmaneuvered competitors. Yet, in the quiet hours of the night, when the emails stop and the house is still, a different kind of tension takes hold. It isn't the tension of what happened today, but the anxiety of what could happen tomorrow.


At Schiff Executive Benefits, we believe that the foundation of any great enterprise isn't just its current balance sheet: it’s the strength of its contingencies. We call these the "What Ifs." Our mission is simple: Helping Business Owners, Executives, and their families plan for all of life’s "What Ifs."


By addressing these five core scenarios, we focus on Restoring Alignment and Retention, ensuring that your legacy is protected and your future is guaranteed.


Quick next step: Start your own Business Valuation here: https://schiffbenefits.com/articles-and-forms/business-valuation/


1. What if you ended up in business with your partner’s widow or widower?


It is an uncomfortable thought, but a necessary one. Most business partnerships are built on a foundation of mutual skill and shared vision. You and your partner "click." But what happens if that partner passes away unexpectedly? Without a robust, funded buy/sell agreement, their shares of the company typically pass to their heirs.


Suddenly, your new 50% business partner might be a grieving spouse who has never stepped foot in your warehouse or attended a board meeting. They may want to be involved in operations they don't understand, or more likely, they may demand dividend distributions to replace the deceased partner's income: distributions the company might not be able to afford while trying to replace a key leader.


Effective business succession isn’t just a legal document in a drawer; it is a financial strategy. Are you using Split Dollar Life Insurance to fund the buyout? Does your agreement have a clear valuation formula that prevents a legal battle during an already emotional time?


Business partners discussing succession strategies and legacy planning in a professional office.


2. What if someone came to you today and said they wanted to buy your business?


Every owner has a "number": that figure that would make all the years of sacrifice worth it. But an unexpected buyout offer is a double-edged sword. If an offer arrived tomorrow, would your business be "exit-ready"?


Potential buyers don't just look at your EBITDA; they look at the stability of your leadership team. If the value of your company is entirely tied to you, the buyer will likely discount the price or insist on a long, grueling earn-out period. To realize your dream value, you need to prove that the business can thrive without you.


This is where exit strategies and incentives like Phantom Stock come into play. By giving your key executives a "stake in the outcome" without giving away actual voting equity, you align their interests with yours. When a buyer sees a motivated management team with "Golden Handcuffs" in place, your valuation skyrockets. You move from selling a job to selling a high-performing machine.


Want to pressure-test what your business is worth before an unsolicited offer lands on your desk? Start here: https://schiffbenefits.com/articles-and-forms/business-valuation/


3. What if your top salesperson or manager left for any reason?


Imagine your top revenue generator walks into your office on a Monday morning and hands you a resignation letter. They aren’t just leaving; they are heading to a competitor for a 20% raise and a "better" benefits package.


The cost of losing a key executive is often calculated at 200% to 300% of their annual salary when you factor in lost momentum, recruitment costs, and the "brain drain" of institutional knowledge. In today’s talent-starved market, standard 401(k) plans and basic health insurance are no longer enough to win the war for talent.


To keep your "MVPs," you need executive retention strategies that actually resonate. We specialize in Non-Qualified Deferred Compensation (NQDC) and Executive Bonus Plans that create a powerful incentive for leaders to stay. We ask the hard question: What is the cost of doing nothing? If you aren't providing a Perfect Plan® for their future, your competitor will.


Confident executive in a modern office, representing effective retention and talent management strategies.


4. What if you could incent senior execs to retire while also retaining their replacement cost-efficiently?


There comes a point in every organization’s lifecycle where a transition is necessary. You have a loyal, senior executive who has been with you for twenty years. They are ready to slow down, but the cost of funding their retirement "promise" while simultaneously paying a high salary to recruit their successor can put a massive strain on company cash flow.


This is a common friction point in corporate and bank leadership. The solution lies in Corporate Owned Life Insurance (COLI). This is not just an insurance policy; it is a sophisticated financial asset that can provide tax-deferred growth to help offset the liabilities of executive benefits.


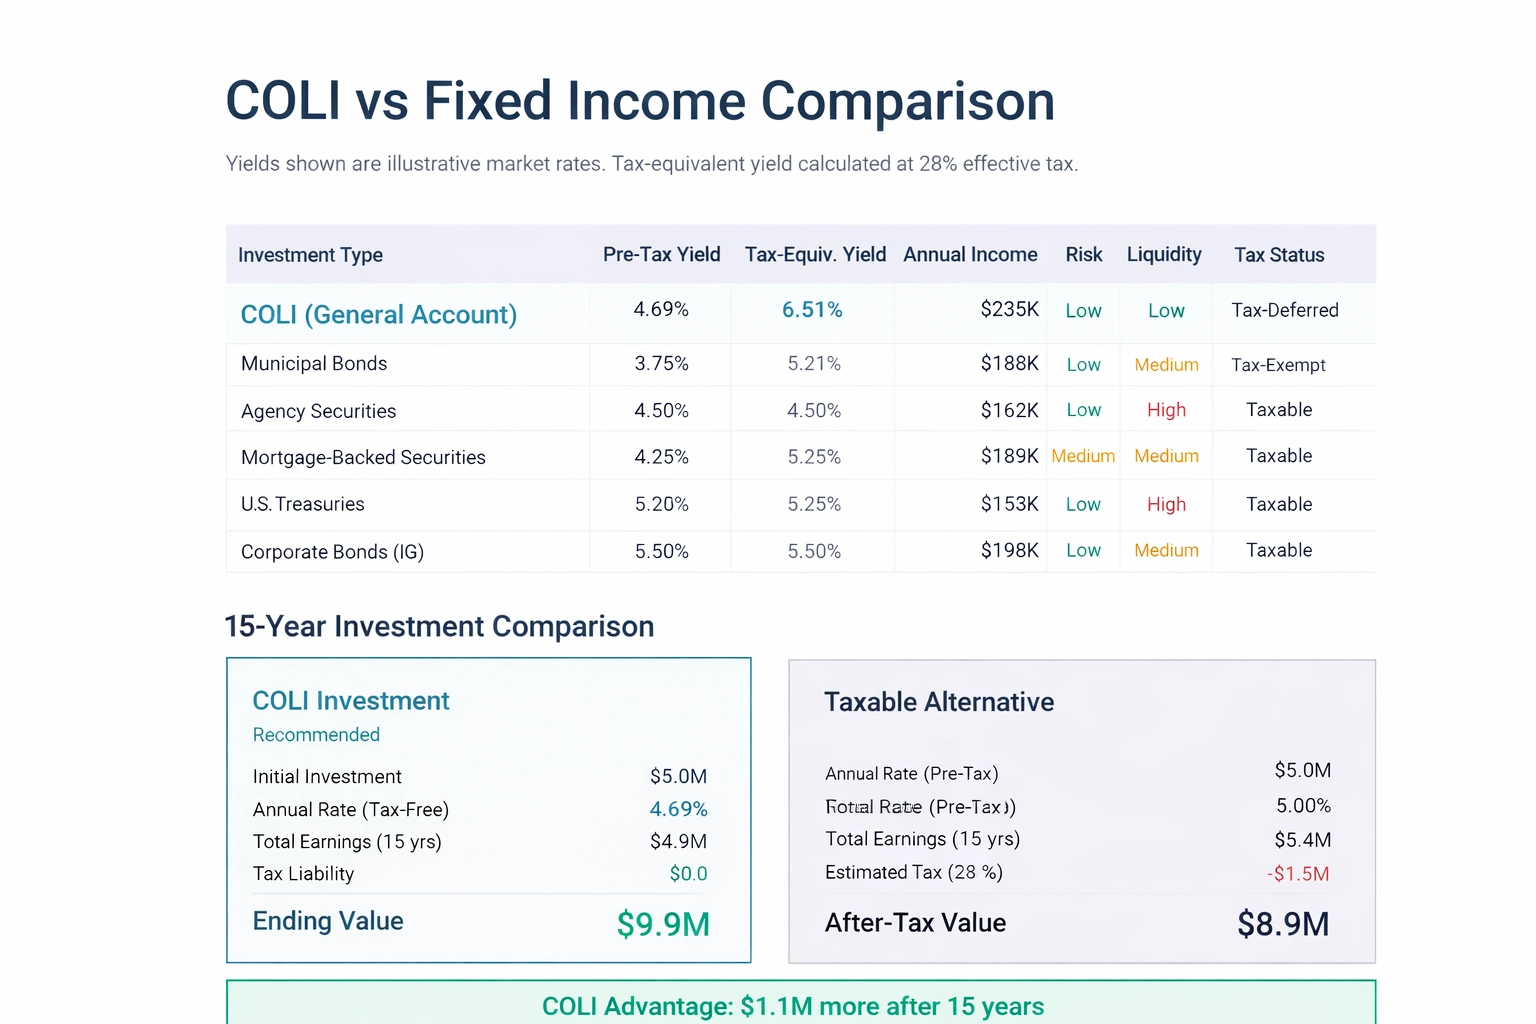
COLI vs Fixed Income Comparison


As shown in the chart above, strategies like COLI can significantly outperform traditional fixed-income investments, providing the liquidity and yield necessary to fund retirement obligations without depleting the company’s operating capital. It allows the senior executive to retire with dignity while giving the company the financial "breathing room" to hire the next generation of leadership. You can learn more about how we structure these for corporations on our COLI information page.

5. Lastly, when I retire, what if I run out of money?


This is the ultimate "What If." You have spent your life managing risk for your company, your employees, and your customers. But who is managing the risk for you?


Many high-net-worth business owners are surprised to find that their standard of living in retirement requires a cash flow that their traditional investments might not guarantee, especially in a volatile market or a high-tax environment. The fear isn't just about "having enough"; it's about the "sequence of returns" and the impact of taxes on your distributions.


This is why we developed The Perfect Plan®.


The Perfect Plan® is designed to provide a fixed rate and a fixed flow of income, removing the guesswork from your post-career life. It is about moving from "accumulation" to "distribution" with absolute certainty. We focus on tax-efficient strategies that ensure your wealth lasts as long as you do, protecting your family’s lifestyle and your professional legacy.


Moving from Anxiety to Authority


These five questions are not meant to cause alarm; they are meant to spark action. In the world of executive benefits, silence is the greatest risk. The longer you wait to address these "What Ifs," the fewer options you have when the crisis finally hits.


Are you ready to stop reacting to the market and start leading your legacy?


At Schiff Executive Benefits, we don't just sell products; we architect security. We work alongside your existing team of advisors: your CPAs and attorneys: to ensure that every piece of your financial puzzle fits together. Whether you are a corporation looking to optimize your COLI strategy or a private business owner looking to secure your family's future, we are here to guide you through the "unstable" and into the "guaranteed."


Succession, retention, and retirement are not separate silos; they are the three pillars of a healthy business. When they are aligned, you sleep better. When they are funded, you lead better. If you are evaluating broader executive retention strategies, the right structure can help you attract, retain, and reward key people without forcing a one-size-fits-all approach.


Sit back, grab your coffee, and let’s start a conversation.


You’ve built something incredible. Now, let’s make sure it’s built to last. Come join us at Schiff Executive Benefits and discover how we can help you plan for all of life's "What Ifs."


To dive deeper into these strategies, listen to our latest episodes on The Perfect Plan® Podcast, where we break down the technicalities of 409A compliance, exit planning, and the macro-economic trends affecting business owners today.


Additional resources (go deeper, stay in one place):


The Perfect Plan® Podcast Banner


Ready to address your "What Ifs"? Contact us today for a confidential consultation.


Ready to talk?


If you’re thinking about deferred compensation, executive retention, or how to structure a plan that fits your goals, let’s talk it through.


Schedule an initial meeting


They say that building a business is like raising a child: it takes years of sleepless nights, total devotion, and a fair amount of luck. But here is the undeniable truth that most entrepreneurs ignore until it is too late: it is much easier to build a business than it is to keep one together when life goes sideways.


As business owners, we spend 99% of our time focused on growth, culture, and the bottom line. We rarely want to talk about the "What Ifs." But those "What Ifs" are the very things that can dismantle a lifetime of work in a single afternoon. At Schiff Executive Benefits, we focus on Restoring Alignment and Retention, and nowhere is that alignment more critical than in your Buy/Sell arrangement.


If you don’t have a plan, or if your plan is a dusty document sitting in a drawer from ten years ago, you aren't just taking a risk: you are gambling with your legacy.


The Emotional Reality: Who Is Sitting in That Chair?


Let’s skip the legal jargon for a second and talk about the real world. Imagine it’s Monday morning. You walk into the office, grab your coffee, and head to your partner’s office. But your partner isn't there. Instead, sitting in that chair is your partner’s spouse.


They are grieving, they are overwhelmed, and they have just inherited 50% of your company.


Now, you love your partner, and you probably like their spouse. But do you want to be in business with them? Do they understand the nuances of your industry? Do they share your vision for the next five years? Most importantly, they likely need liquidity: they need the income your partner used to bring home. But the business needs that cash to stay afloat and grow.


Suddenly, your best friend’s spouse has become your most difficult board member. This is the first of our "Five What Ifs," and it is the one that keeps most owners up at night.


Or consider a different "What If": An unsolicited buyout from a competitor. Your partner decides they want out, and instead of selling back to you, they find a "strategic buyer": the very person you’ve been competing with for a decade. Now, your greatest rival has a seat at your table and access to your trade secrets.


How does that feel? It feels like a loss of control. And in business, control is everything.


Business partners discussing legacy planning and their Buy/Sell agreement in a modern office.


The Trap of the "Generic" Buy/Sell Agreement


Most business owners believe they are covered because they have a Buy/Sell agreement tucked away in a file. But let me ask you: When was the last time you looked at it? Does it reflect the actual value of your business today?


Many agreements are "form" documents provided by a lawyer years ago. They often lack a clear valuation methodology or, worse, they aren't funded. A Buy/Sell agreement without a funding mechanism is just a polite piece of paper. It tells you that you have to buy out your partner, but it doesn't tell you where the millions of dollars are going to come from to make that happen.


Without proper funding, you are forced to choose between three bad options:


  1. Draining Company Cash: Killing your working capital and stalling growth.

  2. Taking on Debt: Going to the bank at a time of crisis to borrow money for a buyout.

  3. Selling Assets: Fire-selling parts of the business to cover the cost.


The Technical Edge: Reverse-Engineering the Solution


At Schiff Executive Benefits, we don't start with products. We start with your intent. We look at your company culture and the specific goals of the owners. We use a process we call The Perfect Plan® to ensure that every piece of the puzzle fits together.


The SEB Executive Benefits Design Checklist (a.k.a. “Let’s Stop Guessing”)


Here’s a universal truth: most benefit and succession plans don’t fail because the math is wrong. They fail because the motivations are misaligned.


So before we talk about funding mechanisms and legal language, we run what we call the SEB Executive Benefits Design checklist. It’s a diagnostic. Not a sales pitch. Think of it like a pre-flight checklist—because “we’ll figure it out on the way down” is not a strategy.


We put two columns on the table:


What the employer typically needs:


  • Deductions / cost efficiency (or at least a clear path to cost recovery)

  • Retention (handcuffs… but the friendly, culture-approved kind)

  • Control (who’s in, who’s out, and what happens when life happens)


What the employee typically wants:


  • Tax-free income (especially when it matters most)

  • Long Term Care (LTC) benefits (because aging is undefeated)

  • No caps (because top performers don’t love being told “that’s the limit”)


Then we ask the questions that actually move the needle:


  • If you’re paying for this, what behavior are you buying?

  • If they’re staying for this, what promise are they counting on?

  • If the “What Ifs” show up early, does this plan still do what it said it would do?


When those two columns line up—employer needs and employee wants—you don’t just get a plan that looks good on paper. You get The Perfect Plan®. And yes, it’s as rare (and valuable) as it sounds.


1. The Valuation Piece


You cannot protect what you haven't valued. Most owners have a "gut feeling" about what their business is worth, but that doesn't hold up in court or with the IRS. To get started, you need an objective baseline. I encourage you to use our tool to start your own Business Valuation right now. Knowing your number is the first step toward security.


2. Trigger Events


A good agreement covers more than just death. It needs to address disability, retirement, divorce, and even personal bankruptcy. What happens if a partner is permanently disabled? Who decides when they are "disabled enough" to trigger a buyout? We help you define these terms so there is no ambiguity when emotions are running high.


3. Funding with COLI (Corporate Owned Life Insurance)


This is where technical expertise meets practical execution. One of the most efficient ways to fund a Buy/Sell arrangement is through Corporate Owned Life Insurance (COLI).


COLI allows the company to own policies on the lives of the owners. If a "What If" occurs, the death benefit provides immediate, tax-free liquidity to the company. The company then uses that cash to buy out the heirs. The family gets the money they need, and you get 100% control of the business back.


But it goes deeper than that. Properly structured COLI can provide cost recovery. The cash value growth within the policy can help offset the costs of the premiums over time, and in some cases, even provide a way to fund an owner's retirement if they don't pass away while active in the business. It’s about making the company's balance sheet work harder for you.


Expanding the Horizon: ESOPs and The Dilemma


Sometimes, the best exit strategy isn't a simple partner buyout. We often talk about "The Business Owner's Dilemma," a concept popularized by Ali Nasser. In our discussions on The Perfect Plan® Podcast, we dive deep into the tension between business wealth and personal freedom. Are you building a business that owns you, or a business that fuels your life?


For some companies, an Employee Stock Ownership Plan (ESOP) is a powerful alternative. I recently had a great conversation with Dan Zugell on ESOPs, which you can find in our podcast channel and on our YouTube channel. An ESOP can provide a market for your shares, incredible tax advantages, and a way to reward the people who helped you build the company: all while you maintain a level of control during the transition.


Whether it’s a standard Buy/Sell or a more complex ESOP structure, the goal remains the same: ensuring that the transition happens on your terms, not because of a crisis.


Why "Wait and See" Is Not a Strategy


I’ve sat across the table from many owners who say, "Matt, we’ll figure it out when the time comes. We’re all healthy, and we’re all friends."


That is a dangerous sentiment. Business is unstable enough as it is. Why leave the most important transaction of your life to chance? The national debt is rising, tax laws are in constant flux, and market trends can shift overnight. You need a "security" that acts as a guarantee against these external forces.


By implementing a properly designed Buy/Sell arrangement funded by COLI, you are effectively "de-risking" your legacy. You are ensuring that if the unthinkable happens, the business stays intact, the employees stay employed, and the families are taken care of.


A business owner and advisors collaborating on a de-risked corporate succession strategy.


Your Next Steps: Building Your Way


So, where do you go from here?


First, sit back, grab a coffee, and think about those "What Ifs." If your partner wasn't there tomorrow, what happens to your desk? What happens to your bank line of credit?


Second, get a real number. Go to our Business Valuation tool and start the process. It’s confidential and provides the clarity you need to move from anxiety to action.


Third, let’s talk. At Schiff Executive Benefits, we aren't just selling insurance policies; we are architects of The Perfect Plan®. We work alongside your team of advisors: your CPAs and attorneys: to make sure the technical design of your Buy/Sell matches the emotional intent of your heart.


Your professional legacy is too important to be left to a "standard" agreement. Let's make sure your plan is as unique as the business you’ve built. Come join us in the process of Restoring Alignment and Retention for your company.


Are you ready to realize your dream value and build it your way? Let’s get started.


Learn more: planning your business succession.


Efficiency is not just a goal in the insurance industry; it is a prerequisite for survival. There is an old adage in our business that "capital follows the path of least resistance and greatest efficiency." Yet, for many insurance carriers, significant portions of their surplus capital remain trapped in traditional, tax-inefficient investment vehicles that barely keep pace with inflation after the tax man takes his cut.

If you are leading an insurance company, you know the pressure: the constant tug-of-war between maintaining robust Risk-Based Capital (RBC) ratios and the need to generate yields that can actually offset the rising costs of attracting and retaining elite executive talent. You might find yourself asking: What if our surplus capital could work twice as hard without increasing our regulatory burden? Or more pointedly: What if we could fund our executive retirement obligations with the very same dollars we use to optimize our balance sheet?

This is where Insurance Company Owned Life Insurance, or iCOLI, enters the conversation. It is a specialized application of COLI tailored specifically for the unique regulatory and tax environment of insurance carriers.

The Problem: The Hidden Drag on Surplus Capital


Insurance companies are often their own worst enemies when it comes to asset allocation. Because of stringent regulatory requirements, a large portion of surplus is typically parked in high-grade corporate bonds or Treasuries. While safe, these assets are fully taxable, and their "drag" on the bottom line is often underestimated.

Consider a carrier holding $100 million in a taxable investment account. If that account earns an average of 8% over 20 years, it grows to approximately $466 million. However, at a 21% corporate tax rate, that carrier will hand over roughly $76.9 million in taxes.

Beyond the tax burden, there is the issue of executive benefits. In an industry where the competition for top-tier underwriting and actuarial talent is fierce, the cost of funding Supplemental Executive Retirement Plans (SERPs) and deferred compensation arrangements continues to climb. How do you cover these liabilities without eroding the capital you need for growth and claims-paying ability?

The Solution: iCOLI as a Strategic Engine


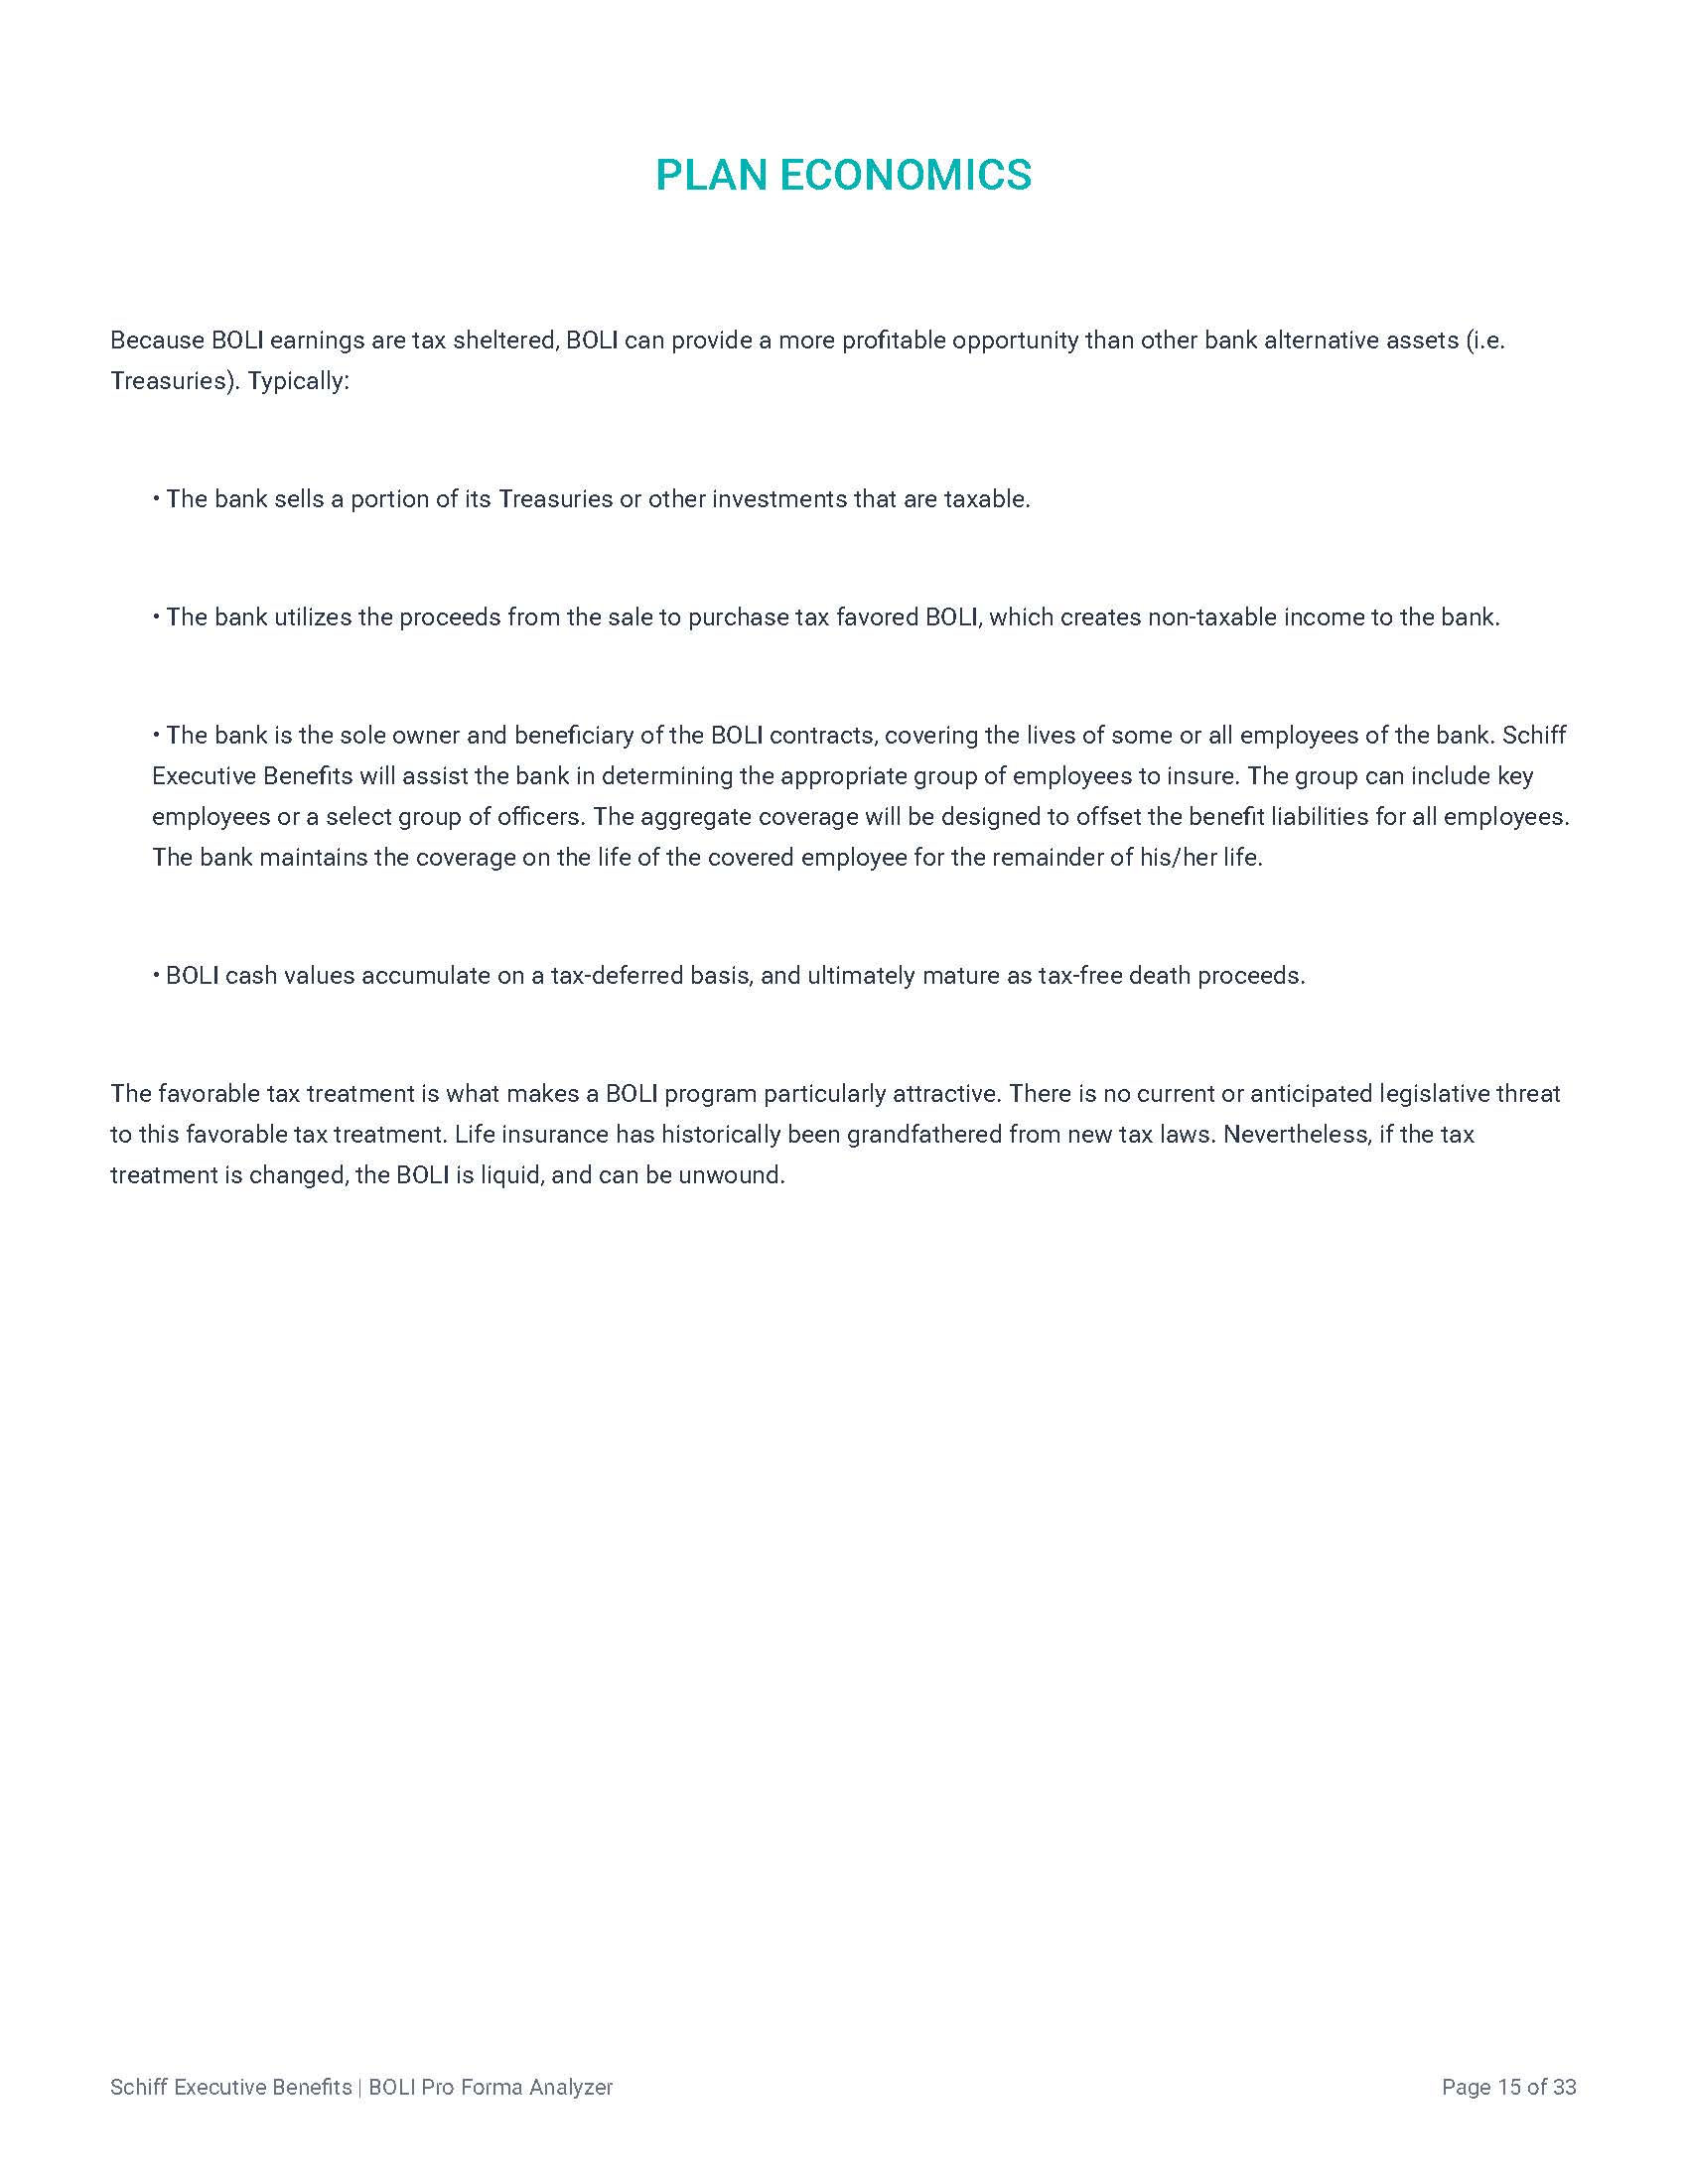
iCOLI is not just an insurance product; it is a corporate financing tool. At its core, iCOLI involves the insurance company purchasing life insurance policies on a select group of senior executives. The company is the owner and beneficiary, and the internal cash value of the policy grows on a tax-deferred basis.

By shifting a portion of surplus capital into an iCOLI program, carriers can achieve three primary objectives:

  1. Capital Optimization: Significantly reducing RBC charges.

  2. Yield Enhancement: Accessing alternative investment classes with tax-free growth.

  3. Cost Recovery: Creating a dedicated asset to offset executive benefit liabilities.


Insurance executives discussing iCOLI strategies for capital optimization and yield enhancement in a boardroom.

1. Optimizing Capital through RBC Advantages


For an insurance carrier, the Risk-Based Capital ratio is the ultimate scorecard. Traditional investments carry varying degrees of capital charges that can tie up your "free" capital.

One of the most compelling reasons carriers adopt iCOLI is the favorable regulatory treatment. For Life and Health (L&H) insurance companies, iCOLI typically receives a 0% RBC charge. For Property and Casualty (P&C) insurers, the charge is often as low as 5%.

When you compare this to the much higher charges associated with equities or even certain lower-rated bond portfolios, the math becomes clear. By utilizing iCOLI, you are essentially freeing up capital that can be deployed elsewhere in your business, whether that’s for acquisitions, technology upgrades, or expanding your book of business. It is a way of building it your way, ensuring your balance sheet reflects your long-term strategic goals rather than just regulatory necessity.

2. Improving Investment Yields


iCOLI programs offer access to specialized investment vehicles that are often unavailable through traditional corporate accounts. Through Insurance-Dedicated Funds (IDFs) and Separately Managed Accounts (SMAs), carriers can diversify into:

  • Private Equity and Hedge Funds

  • Private Credit

  • Real Estate

  • Alternative Credit Strategies


Because these investments are held within the iCOLI "wrapper," the earnings grow tax-deferred. Furthermore, the carrier can reallocate assets within the policy without triggering a taxable event. This flexibility allows for a more aggressive or diverse investment posture without the usual tax friction that hampers traditional surplus accounts.

3. Offsetting Executive Benefit Costs: Addressing the "What Ifs"


At Schiff Executive Benefits, we often talk about the five "What Ifs" that keep leaders up at night. For insurance executives, two of those questions are particularly relevant:

  • What if our top talent leaves for a competitor?

  • What if the cost of replacing or retiring a senior executive becomes prohibitively expensive?


Executive retention is about Restoring Alignment and Retention. When you offer a robust deferred compensation plan or a SERP, you are creating a "golden handcuff" that aligns the executive's long-term interests with the company's success. However, these plans create a liability on the balance sheet.

iCOLI provides the perfect "match." The tax-advantaged growth within the iCOLI policies generates monthly bookable income that can directly offset the accrual of these benefit liabilities. In many cases, the death benefit eventually received by the company provides a full recovery of all costs associated with the benefit plan, including the "cost of money."

Visual display of leading insurance and financial carriers Schiff Executive Benefits works with

The Importance of a Carrier-Agnostic Approach


If you are an insurance company, you might be tempted to "buy from yourself." While internalizing the business seems logical, it often leads to concentration risk and potential conflict of interest from a fiduciary and regulatory perspective.

This is where the Schiff Executive Benefits team provides unique value. We believe in providing carrier-agnostic solutions. We work with an extensive list of top-tier carriers, from John Hancock and MetLife to Pacific Life and Prudential, to ensure that the iCOLI program is structured with the best possible pricing, transparency, and investment options.

Our process is part of The Perfect Plan®, a comprehensive framework designed to ensure that every executive benefit and capital optimization strategy is integrated, compliant, and performing at peak efficiency. We don't just "sell a policy"; we help you design a strategic asset that fits into your broader financial ecosystem.

Regulatory and Accounting Considerations


Implementing an iCOLI program is not a "set it and forget it" endeavor. It requires rigorous pre-purchase analysis and ongoing administration to meet NAIC and state-specific regulatory standards.

  • Insurable Interest: You must ensure that the executives being insured meet the criteria for insurable interest in your specific jurisdiction.

  • IRC 101(j) Compliance: This is a critical technical standard for iCOLI programs. To preserve the income-tax-free treatment of death benefits, the employer must satisfy the notice and consent requirements before policy issue and confirm the insured falls within an eligible employee class under the statute. Ongoing documentation and coordination with your legal, tax, and HR advisors are essential.

  • FASB/GAAP Compliance: The accounting for iCOLI can be complex, involving the reporting of the Cash Surrender Value (CSV) as an asset and the changes in CSV as other operating income.

  • Transparency: As with any institutional program, transparency in fees, mortality costs, and investment management is paramount.


In practice, that means the compliance work cannot be an afterthought. If notice, consent, and recordkeeping are mishandled, the tax advantages that make iCOLI so attractive can be materially compromised.

We often guide our clients through a ten-step pre-purchase assessment, which includes employee benefit liability calculations, 101(j) review, and financial modeling to ensure the program is right-sized for the organization’s needs.

Why Now? The Point of No Return


The economic environment of 2026 is one of rapid change. With shifting tax policies and a volatile market, the cost of "waiting" is higher than ever. Every year surplus capital sits in a tax-inefficient environment is a year of lost compounding that can never be recovered.

We are seeing more U.S. insurance companies: over 350 at the last count: utilizing iCOLI assets to bolster their financial positions. Some major carriers now hold iCOLI assets exceeding $1 billion. They have recognized that in an unstable financial environment, having a secure, tax-advantaged capital engine is not a luxury: it’s a necessity.

Closing Thoughts: Sit Back, Grab Your Coffee


Navigating the intersection of capital optimization and executive retention doesn't have to be a source of anxiety. It should be a source of confidence. When you align your capital strategy with your people strategy, you aren't just managing a business; you are securing a legacy.

Are you maximizing the potential of your surplus capital? Are your executive benefits structured to withstand the next decade of market shifts?

If these questions are on your mind, we invite you to explore our video library or listen to The Perfect Plan® Podcast for deeper insights into these strategies. Better yet, let’s have a conversation.

Come join us for a consultative review of your current holdings. We’ll help you determine if an iCOLI program is the missing piece in your capital puzzle.

Schiff Executive Benefits contact information and commitment statement

Restoring Alignment and Retention. It’s what we do. It’s what The Perfect Plan® is built for.

Sit back, grab your coffee, and let’s talk about how to make your capital work as hard as you do.